

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HDI Market Set to Grow at 6.98% CAGR Through 2032

HDI Market 2026 Preview: Strategic Signals for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused preview of the HDI (High-Density Interconnect) PCB market designed to equip executives with the essential signals needed for high‑stakes decisions in 2026. This briefing synthesizes macro trajectory, competitive dynamics, cost and regulatory headwinds, and the practical implications for strategy — while deliberately withholding the granular regional and application splits contained in our full HDI Market report to preserve the value of the proprietary dataset.
HDI Market
Why this view matters for 2026 decision cycles
The HDI market has moved from niche to foundational in just a few years. At the macro level, the market expanded from the low‑hundreds of millions in 2020 to roughly USD 215 million in 2025, and our modeling anticipates continued momentum through the forecast window to a materially larger market by 2032 under a roughly 7% compound annual growth rate (6.98% CAGR). That trajectory creates both runway and pressure: it unlocks growth options but intensifies competition for capacity, specialized materials and engineering talent.
HDI Market
For corporate strategists, procurement heads, and private-equity sponsors making 2026 plans, these are the practical implications:
HDI Market
- Capacity choreography matters: Demand growth is steady enough to justify targeted capacity investments, but not uniform — companies that time and localize capacity to match OEM electrification and 5G rollout waves will preserve margin.
- Product differentiation wins: Technical advances in high‑layer count boards, high‑frequency materials and ultra‑fine interconnects are the primary levers for premium pricing and customer stickiness.
- Supply‑chain risk is real: Material cost volatility and the need for specialized equipment and labor raise the bar for supplier qualification and near‑term lead‑time management.
What the full HDI Market report delivers (operationally actionable)
Our HDI Market research is built for execution, not just insight. Key operational deliverables include:
- Forecasting model (2026–2032): scenario-enabled revenue and capacity simulations to stress-test capex and inventory plans under alternative demand and cost shocks.
- Strategic playbooks: tailored decision frameworks for OEMs, board manufacturers and materials suppliers on vertical integration, contract structuring, and strategic partnerships.
- Competitive benchmarking: capability matrices, technology roadmaps and supplier scorecards to align sourcing decisions with target SLAs for yield, cycle time and thermal/electrical performance.
- Commercial intelligence: go‑to‑market segmentation (intentional summary here; granular regional and application-level numbers are reserved for the report) and prioritized channel strategies for different end markets.
- M&A and JV opportunitization: target screens based on capability adjacency, footprint synergies and integration economics — with accretion/dilution modeling for common deal structures.
- Cost and margin playbooks: detailed build-ups for labor, CAPEX, advanced materials and yield scenarios to support pricing, make-vs-buy and offshoring decisions.
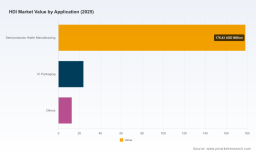
Note: this preview omits the detailed region- and application-level numeric breakdowns and the full company-level share matrix to protect the proprietary value of the underlying market model. Those elements are included in the licensed report and the interactive dashboard.
Market structure and competitive dynamics
Two structural features define the competitive environment today. First, the HDI market is growing but remains relatively fragmented: the three‑ and five‑firm concentration ratios are low compared to many legacy PCB segments, providing room for aggressive consolidation or specialization plays. Second, technological differentiation — particularly in ultra‑high‑density interconnects, high‑frequency laminates and multilayer stack-ups — is the primary route to capture value.
How incumbent and emerging suppliers are responding:
- Specialists focusing on high‑layer-count automotive and industrial HDI (e.g., firms with strengths in multilayer process control) are winning long lead contracts in battery management and power control modules driven by EV adoption and electrified systems.
- Suppliers oriented to telecom and computing demand are capitalizing on increased procurement of high‑frequency boards catalyzed by widespread 5G deployment; these players prioritize low-loss laminates and fine-line lithography capabilities.
- Consumer and mobile-focused vendors continue to push ultra‑high-density solutions where miniaturization and signal integrity are differentiators, but they must manage very tight cost and time-to-market constraints.
Company positioning: a concise competitive read
Below is a high-level strategic read on the core players reviewed in our research. These summaries highlight positioning, capability adjacencies and the near‑term strategic moves that matter for partners and competitors.
- Zhen Ding Technology Corporation (Taiwan) — Strong domain expertise in high‑layer‑count HDI for automotive and industrial electronics. Their engineering focus on multilayer reliability positions them well for EV and BMS contracts where thermal and mechanical robustness are required.
- Unimicron Technology Corp (Taiwan) — Deep engagement in telecom and computing applications. Unimicron’s investments in high-frequency process capability align it to capture incremental demand from 5G base-station and edge-compute equipment suppliers.
- AT&S (Austria) — A European contender with balanced exposure to consumer and automotive segments. AT&S’s breadth makes it a preferred supplier for OEMs seeking regional diversification and integrated supply assurances.
- Ibiden Co., Ltd. (Japan) — Known for expertise in high-frequency and power applications. Ibiden’s material science focus and process control are assets as telecom and power‑electronics buyers demand higher performance laminates.
- TTM Technologies, Inc. (United States) — Industrial and automotive‑market orientation with a U.S. footprint that appeals to government‑sensitive buyers and those prioritizing local content.
- Meiko Electronics Co., Ltd. (Japan) — Automotive and EV-focused; Meiko’s strengths in EV powertrain and high-reliability assemblies make it a candidate for deep supplier relationships with major automakers.
- Samsung Electro‑Mechanics (South Korea) — Leader in ultra‑high‑density interconnects for consumer electronics. Their scale, integrated R&D and proximity to major device OEMs create a high bar for pure-play competitors in mobile and wearables.
These profiles are complemented in the full report by supplier readiness scores, IP/technology roadmaps, and a targeted M&A attractiveness heatmap for potential acquirers and partners.
Drivers, headwinds and strategic implications
Several converging forces will shape 2026 outcomes:
- Electrification tailwinds: EV production surpassed 19 million units globally in 2025, accelerating adoption of multilayer HDI systems in battery management and power electronics — creating durable OEM demand pockets for suppliers who can guarantee reliability at scale.
- Telecom acceleration: Telecom procurement of high‑frequency HDI boards jumped materially during 2025 as 5G densification progressed. Suppliers with validated HF laminates and high-yield fine-line processes are benefiting from multi‑year contracts.
- Material and labor cost pressure: Advanced HDI manufacturing reduces gross material usage in many devices but increases reliance on specialty laminates and precision equipment. Skilled labor and process automation are significant drivers of per‑unit cost and capital intensity.
- Regulatory and sustainability forces: HDI boards are increasingly evaluated for lifecycle energy efficiency in power electronics and renewables — a trend that elevates suppliers who can document efficiency dividends in BMS and inverter applications.
Practical strategic moves for 2026
For executives planning resource allocation and strategic initiatives in 2026, the following moves are priority actions:
- Prioritize tech‑led partnerships: Co‑development agreements with materials or lithography suppliers unlock faster time to advanced stack-ups than greenfield internal development.
- Adopt selective capacity expansion: Prefer modular, geographically targeted investments aligned to OEM clusters rather than broad, undifferentiated scale‑ups.
- Build supplier resilience playbooks: Create dual‑sourcing strategies for critical laminates and embrace nearshoring where lead‑time risk and regulatory content requirements are material.
- Operationalize margin protection: Invest in process automation and yield engineering to offset rising labor and specialty material costs — target top‑decile yields as a competitive moat.
- Use M&A and alliances tactically: Consolidation opportunities exist where technical gaps can be closed quickly and where footprint synergies accelerate access to strategic OEMs in automotive or telecom.
Closing guidance and next step
In an environment where the HDI market is growing at roughly a 7% CAGR and where the total market size is poised to expand meaningfully beyond the mid‑2020s baseline, 2026 is the year to move from reactive capacity responses to deliberate, portfolio-level strategic positioning. Our full HDI Market report converts the high‑level signals in this preview into executable initiatives — including the granular regional and application-level demand models, supplier scorecards, and transaction-ready feasibility analyses that boards and investors need to act with confidence.
For teams preparing budgets, negotiating supply agreements, or evaluating M&A targets in 2026, the choice is straightforward: use a model that blends macro demand realism with bottom‑up operational levers, and resist one‑size‑fits‑all capacity plays. The market is large enough to reward focus and nimble enough to penalize complacency.
Access to the full dataset and the interactive modeling environment is available through the HDI Market report subscription. The licensed package contains the proprietary segmentation detail, unit economics, and company‑level share matrices that support near‑term transaction and procurement decisions.
For detailed analysis of this topic, please visit the official page: HDI Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com