

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Process Gas Compressor Market Set to Grow at 5.5% CAGR

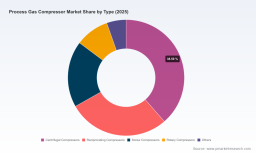
Process Gas Compressors 2026: Strategic Imperatives for Decision-Makers
As companies plan capital allocation and technology roadmaps for 2026, the process gas compressor market presents a blend of steady expansion, regulatory urgency, and selective disruption. PW Consulting's latest market research — built on a 2025 base year and a historical window from 2020–2025 with a forward-looking forecast to 2032 — frames this landscape with rigorous, actionable analysis. At the macro level the market has grown from under USD 6.0 billion in 2020 to about USD 7.8 billion in 2025, and PW’s modeled trajectory now points to roughly USD 11.35 billion by 2032, underpinned by a 5.5% compound annual growth rate (CAGR). These headline numbers capture the expansion dynamic, but the strategic emphasis for 2026 is on how to translate growth exposure into durable competitive advantage amid regulatory tightening, supply-chain turbulence, and the rise of low-emission technology vectors.
Process Gas Compressor Market
Why this research matters for 2026 decisions
-
Capital prioritization: With capital budgets under pressure, procurement and engineering leads need a prioritized view of which compressor technologies and aftermarket services will deliver the highest risk-adjusted returns over a multi-year horizon. Our report converts market trends into invest/delay/exit triggers for typical capital-planning cycles.
Process Gas Compressor Market -
Regulatory risk mitigation: New and evolving regulation on fugitive emissions, energy efficiency, and methane reductions elevates compliance from operational hygiene to a strategic differentiator. The research quantifies the directional impact of EPA and EU measures on equipment sourcing and retrofit timing — enabling procurement and compliance teams to move from reactive to strategic execution.
Process Gas Compressor Market -
Competitive positioning and M&A readiness: The market remains structurally fragmented (our concentration metrics show a low-to-moderate top-player share), creating pockets of consolidation opportunity and technology tuck-ins. The report equips corporate development and strategy teams with a ranked target universe and an integration playbook aligned to 2026 valuation expectations.
Market dynamics shaping 2026 strategy
Three forces will determine winners and laggards next year: regulatory acceleration, technology shifts toward oil-free and hermetic solutions, and supply-chain constraints for critical materials and precision components.
-
Regulatory acceleration: Tightening limits under EPA and EU industrial emissions frameworks, alongside methane-specific mandates, are forcing operators to re-evaluate legacy compressors that leak or rely on oil-lubricated seals. The economics of retrofits, replacements and extended service contracts change materially when compliance timelines are moved forward by regulators — and our scenario analysis outlines how those timelines alter equipment ROI and lifecycle cost.
-
Technology and decarbonization pathways: Demand drivers now include decarbonization use-cases such as CCUS, hydrogen compression, and boil-off gas management at LNG terminals. Demonstrations of high-pressure CO2 compression — including recent multi-stage, geared turbo compressor tests achieving supercritical injection pressures — signal an emerging commercial market for purpose-built units. The report evaluates technology readiness levels and the associated commercialization risk profiles for each use-case.
-
Supply-chain and raw-material volatility: High-grade alloys and precision machined parts remain capacity-constrained in many supplier networks. Price and lead-time volatility for these inputs create execution risk for OEMs and EPCs; our procurement risk matrix helps teams quantify lead-time exposure and suggests mitigation levers such as strategic vendor partnerships, localized manufacturing, and inventory hedges.
What the report contains — practical intelligence for 2026
-
Market sizing and 2026–2032 forecast model (company-level plug-ins): dynamic worksheets you can plug into your financial model to test alternate adoption and regulatory scenarios.
-
Scenario-driven demand stacks: three tiered demand scenarios (base, accelerated regulation, and rapid decarbonization) that translate policy and energy-market shifts into equipment and service demand curves.
-
Competitive benchmarking toolkit: qualitative and quantitative profiles of incumbents and challengers, capability maps for compressor types and service ecosystems, and a “go-to-market” scorecard for each major OEM.
-
Procurement and supply-chain playbooks: vendor risk heatmaps, dual-sourcing templates, and prioritized supplier localization strategies tailored to capital projects commencing in 2026–2028.
-
Technology adoption roadmaps: tactical guidance on when to pilot oil-free and hermetic compressor solutions, when to invest in electrification and variable-speed drives, and how to structure long-term service agreements to capture aftermarket margin.
-
M&A and partnership screening: acquisition screens, synergy checklists, and integration-risk frameworks to identify targets that accelerate decarbonization product lines or provide aftermarket scale.
-
Regulatory impact stress tests: compliance-triggered cashflow sensitivity analyses and a matrix of policy levers that most materially affect equipment lifecycles.
Competitive landscape — actionable takeaways
The competitive field is characterized by specialist engineering houses, heritage reciprocating manufacturers, and increasingly capable turbo-compressor builders. The market concentration metrics in our study indicate that the top three players account for only a quarter of the addressable market — a reminder that scale is distributed and that niche excellence and service leadership remain powerful differentiators.
-
Sundyne: Known for integrally geared centrifugal solutions catering to midstream, downstream, and power-generation customers, Sundyne’s value proposition centers on oil-free, low-vibration operation with an emphasis on hermetic delivery and near-zero emissions. For buyers prioritizing fugitive-emission reduction and total cost of ownership, Sundyne’s packaged systems lower lifecycle compliance risk — an advantage reflected in our buyer decision matrices.
-
Burckhardt Compression: A leader in reciprocating compressor design compliant with API 618, Burckhardt remains the partner of choice for refinery and petrochemical customers requiring high-pressure reciprocating solutions and advanced sealing technology. Our gap analysis shows that Burckhardt’s retrofit and aftermarket capabilities present an attractive margin profile for investors targeting recurring revenue.
-
IHI Corporation: With a product suite that includes geared multi-stage turbo compressors for high-pressure applications, IHI is actively commercializing technology supporting CCUS and other supercritical-CO2 use-cases. A recent demonstration (early 2026) of a multi-stage geared turbo unit achieving 20 MPaG discharge pressure for supercritical CO2 injection signals a step-change in commercial viability for CCUS project compressors. For strategy teams, IHI is a prime example of how R&D leadership against new energy substrates can create a premium growth vector.
Strategic recommendations for 2026
-
Prioritize compliance-forward procurement: Shift from a lowest-capex-first mindset to an emissions-compliance-horizon approach. Use lifecycle-cost metrics that embed regulatory transition risk and potential retrofit windows.
-
Target aftermarket capture: Service, parts, and retrofit kits are a dependable lever to monetize installed bases. Firms that build digital service platforms and spares ecosystems will achieve higher margins and stickier customer relationships.
-
Pursue selective technology partnerships: For firms seeking to enter CCUS, hydrogen, and high-pressure CO2 segments, partnership or minority-investment strategies with proven turbo-compressor innovators can accelerate time-to-market while capping development risk.
-
De-risk supply chains now: Lock capacity for long-lead critical components and explore regional supplier qualification to insulate project timelines. Our procurement playbook includes specific contract structures and inventory thresholds to protect 2026–2028 project pipelines.
-
Use M&A to plug capability gaps: Given the fragmented topology, acquisitions that add hermetic or oil-free manufacturing, specialist sealing tech, or digital predictive-maintenance capabilities offer asymmetric returns against organic development timelines.
What we are not disclosing here — and why
To respect the “preview” nature of this introduction, we deliberately do not reproduce the granular segment share tables, regional revenue breakdowns, or application-level dollar-by-dollar allocations contained in the full report. These core segmentation datasets, scenario workbooks, and proprietary valuation models are accessible through the PW Consulting report platform and are the exact artifacts procurement, strategy, and investor teams will need to execute on the recommendations above.
Next steps for executives
If your team is prioritizing capital projects, regulatory compliance, or M&A moves in 2026, PW Consulting’s full Process Gas Compressor Market research provides the detailed models, vendor scorecards, and executable playbooks to accelerate decision cycles and reduce execution risk. For immediate priorities, we recommend three tactical actions this quarter: (1) run the regulatory stress-test on near-term capex, (2) begin vendor qualification for oil-free and hermetic systems where emissions exposure is highest, and (3) fast-track at least one strategic partner discussion in the CCUS or hydrogen compression domain.
PW Consulting’s analysis is designed to convert market growth and regulatory complexity into concrete project-level decisions. For a guided walkthrough of the dataset and a tailored implications briefing calibrated to your asset and geographic footprint, contact our advisory team to schedule a 60-minute executive session.
For detailed analysis of this topic, please visit the official page: Process Gas Compressor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com