

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ATM market to reach USD 34.4B by 2032 at 4.9% CAGR

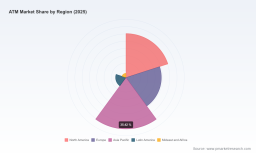
ATM Market Strategic Briefing — PW Consulting (Introduction to the 2026 Research)
As financial services leaders plan capital allocation and operational change in 2026, the ATM estate remains a tangible, high-impact channel — not merely a cash-dispensing artifact of a prior era, but a strategic intersection of cash logistics, branch transformation, payment rails, and digital identity. PW Consulting’s full ATM Market study (base year: 2025; historical window: 2020–2025; forecast: 2026–2032) synthesizes the commercial, technical, and regulatory forces that will determine winners and laggards over the next investment cycle. The market is forecast to expand at a 4.9% CAGR from the 2025 baseline (USD 24.0 Billion), with a clear upward trajectory toward the end of the forecast period. This briefing explains the study’s strategic value for 2026 decision-making and highlights the practical levers enterprise leaders should prioritize now.
ATM Market
Why this study matters for 2026 decisions
-
Capital allocation clarity: With constrained IT and branch budgets, executives need defensible frameworks to prioritize ATM spend across renewals, software, and third‑party managed services. Our study translates market direction into investment thresholds and payback archetypes for different fleet strategies.
ATM Market -
Compliance and risk deadlines: Mandates that took effect in 2025 (notably PCI DSS v4.0, TR-31/TR-34 key management requirements, and tightened TLS expectations) mean hardware and software upgrades cannot be deferred indefinitely. The report maps compliance impact by estate profile and provides implementation sequencing to avoid service disruptions.
ATM Market -
Operational modernization: AI-enabled service resolution, hypervisor-based software stacks, and advanced cash-recycling logic are moving from vendor demos to field rollouts. The study evaluates real-world readiness and quantifies where automation and analytics reduce operating costs and downtime.
-
Vendor and competitive insight: The vendor field has consolidated into a concentrated supplier base. Our analysis helps procurement and operations leaders evaluate supplier roadmaps, commercial models, and integration risks to inform shortlists and RFPs in 2026.
Core market dynamics shaping strategy
-
Measured growth with structural shifts: The market is growing on an aggregate basis at the sub‑6% CAGR noted above, but the shape of that growth is uneven — driven more by upgrades, recycling deployments, and software subscriptions than by linear unit expansion. This creates asymmetric opportunities for software-led vendors and managed-service providers.
-
Regulatory acceleration: PCI DSS v4.0, TR-31/TR-34 key block mandates, and updated industry guidance for TLS profiles have moved compliance from advisory to operational imperatives. The consequence: accelerated software refresh cycles and new cryptographic key management workflows for ATM fleets.
-
“Super ATM” momentum: Industry events in early 2026 showcased a clear trend toward multifunction kiosks capable of deposits, recycling, and enhanced authentication — frequently complemented by AI-driven fraud detection and remote teller integrations. Deployments shift the value proposition from basic cash disbursement to a service node in the omnichannel mix.
-
Cost and automation trade-offs: Cash recycling now represents a material component of operating costs for institutions that deploy it, and automation options (secure cash transfer, depot automation, and authenticated deposit-routing) change whether a branch or back-office should handle reconciliation and cash-in-transit activity.
-
Security and cryptography: The move to mandatory cryptographic best practices and stronger transport-layer protocols is non-negotiable — upgrade schedules must be aligned with certification timelines to avoid network segmentation or transactional failures.
Competitive landscape — practical takeaways
-
Diebold Nixdorf — strong in estate management and AI-enabled fraud detection via its Vynamic platform. Institutions seeking an integrated hardware-software stack should assess trade-offs between vendor-managed analytics and open analytics platforms for portability.
-
NCR Atleos — leading with service-intelligence platforms and field-service optimization. NCR’s recent industry recognition underscores the commercial value of AI-assisted service resolution; banks focused on uptime and SLA-driven contracts should weight this capability heavily.
-
Hyosung TNS / Hyosung Americas — emphasizing branch cash management and biometric authentication. Their product refreshes implement practical automation that can materially reduce teller cash handling, making Hyosung attractive for retail-heavy networks seeking fast time-to-value.
-
GRG Banking — competitive on cost and scope for integrated teller and bill-pay features, particularly in markets where price and local integration matter. Institutions expanding in emerging or price-sensitive markets should include GRG in balanced shortlists.
-
Hitachi Channel Solutions and OKI — differentiated on reliability and high-capacity recyclers. Their engineering strengths fit use cases where volume, counterfeit detection, and anti-skimming are prioritized over modular service models.
-
KAL ATM Software — notable for hypervisor-based software that supports estate analytics and AI fault detection. For organizations pursuing virtualization and rapid application deployment, KAL’s approach reduces hardware lock‑in risk and accelerates multi-vendor estates modernization.
Recent events and implications
-
ATMIA US Conference 2026 highlighted the commercial push toward Super ATMs and ecosystem partnerships — an early signal that vendors and cash logistics players expect mainstream adoption of multifunction devices.
-
Vendor-led announcements and awards in early 2026 demonstrate that innovation is now being monetized through software and managed services, rather than through unit sales alone. Banks should recalibrate procurement value drivers accordingly.
-
Regulatory and standards updates that became effective in 2025 continue to drive near-term technology choices; institutions that treat compliance as a backward-cost rather than a design constraint incur higher remediation costs and integration friction.
What the full PW Consulting report delivers (practical, operational content)
-
Actionable procurement frameworks: vendor scorecards, RFP templates, and outcome-based SLA clauses aligned with 2026 compliance realities.
-
Interactive financial models: TCO and ROI calculators that allow you to model refresh cadence, recycling penetration, managed vs. owned services, and sensitivity to cash-use scenarios.
-
Implementation playbooks: step-by-step migration sequences for cryptographic key management (TR-31), TLS upgrades, and staged software rollouts to preserve availability during transitions.
-
Operating model options: build, buy, or outsource decision trees with break-even horizons and vendor transition risk matrices tailored for different fleet sizes and geographies.
-
Scenario analyses: best-, base-, and stress-case forecasts with clear triggers for advancing capex, accelerating consolidation, or expanding service footprints (e.g., Super ATM pilots).
-
Benchmarks and estate analytics: comparative KPIs and a benchmarking toolkit to evaluate uptime, incident MTTR, cash logistics cost per transaction, and software patch velocity.
How enterprises should use this briefing in 2026
-
C-suite: Treat the ATM estate as a strategic asset class. Use the study’s scenario guidance to set a 3‑year capex envelope and define endpoint objectives (e.g., % of estate with recycling, % on hypervisor stacks, SLA targets).
-
CIO/CTO: Align software modernization timelines with PCI/TR-mandates; adopt hypervisor-first pilots to reduce hardware refresh risk and enable containerized service delivery.
-
Head of Retail/Operations: Prioritize pilot Super ATM sites where deposit density and footfall justify automation; leverage cash-recycling to reduce branch cash handling and redeploy teller labor to advisory roles.
-
Procurement: Reframe RFPs to value outcomes (uptime, fraud reduction, service resolution time) and include clauses for AI model governance, data portability, and cryptographic key custody.
-
Security/Compliance: Fast-track TR-31/TR-34 and TLS upgrades with a vendor-validated timeline; use the report’s implementation playbook to avoid network fragmentation or certification delays.
Strategic scenarios and concentration risks
The supplier landscape is meaningfully concentrated, which creates both strategic advantages (stable vendor roadmaps, integrated offerings) and risks (pricing power, supplier single points of failure). Our competitive concentration analysis quantifies this consolidation and models supply‑chain stress scenarios. The report includes contingency plans for vendor disruption and practical switching-cost evaluations to support negotiation leverage during contract renewals.
Conclusion — the strategic edge for 2026
PW Consulting’s ATM Market study gives leaders the analytical rigor and practical tools needed to convert a stable-but-transforming market into a source of competitive differentiation. Whether the immediate priority is compliance sequencing, cost‑to‑serve reduction, or piloting Super ATMs and AI-enabled service models, the enclosed frameworks support defensible decisions and measurable outcomes. This introduction highlights the strategic contours; the full report contains the granular segmentation, interactive models, vendor scoring, and deployment playbooks you will need to execute confidently in 2026. Access the full intelligence to unlock the detailed splits, benchmark data, and executable templates that operational teams require.
For detailed analysis of this topic, please visit the official page: ATM Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com