

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Paint Market Poised for 4.16% CAGR — Strategic Opportunities Ahead

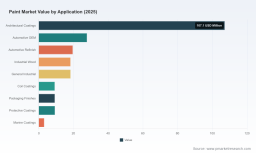
Paint Market 2026: Strategic Preview for Executive Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking, high-conviction preview of our new Paint Market study — a decision-grade intelligence pack designed to support executive teams through 2026 and beyond. Below I summarize the strategic implications that matter most to leaders in coatings, downstream manufacturing, private equity, and procurement. Think of this as the cinematic trailer: we reveal the narrative, the turning points, and the playbook — while reserving the granular, segment-level datapoints for the full report.
Paint Market
High-level market trajectory: what the numbers tell us
The global paint market has moved from recovery into structurally higher demand and premiumization. Using 2025 as our base year, total industry revenue reached USD 221.64 Million (revenue unit: Million), following steady growth from 2020. Our modeled forecast through 2032 projects a compound annual growth rate (CAGR) of 4.16% across 2026–2032, with the market reaching roughly USD 296.46 Million by 2032. The immediate outlook for 2026 shows continued expansion from the 2025 base.
Paint Market
Why this matters: a mid-single-digit CAGR in a commodity-plus-innovation sector implies slower volume-driven expansion but meaningful upside to players that capture value via differentiation — whether through formulation technologies, service models, sustainability credentials, or channel economics.
Paint Market
Market structure and competitive posture
The market remains moderately concentrated. Our concentration analysis shows the top three players control approximately one-third of global revenue, while the top five account for just over 40%. This structure creates a dual dynamic:
- Large incumbents retain scale advantages — R&D budgets, distribution networks, and procurement leverage — enabling defensive price or capacity plays.
- Mid-sized and regional players can exploit local manufacturing proximity, specialized application expertise, and agile product launches.
Because concentration is neither hyper-consolidated nor atomized, the competitive landscape favors targeted M&A, bolt-on capability investments (e.g., low-VOC formulations, digital color services), and commercial plays that combine brand with technical service.
What executives must factor into 2026 planning
- Raw material volatility is a strategic risk: High-grade pigment and titanium feedstock costs increased materially across 2024–2025. This has compressed margins selectively and accelerated procurement hedging and backward-integration discussions. Scenario planning around sustained input inflation is now table stakes.
- Regulatory inflection points are reshaping product roadmaps: Recent amendments to aerosol coatings rules and lead-based paint standards in major jurisdictions have come into force or are staged for compliance timelines through 2026. These changes amplify compliance costs but also create premium niches for certified low-emissions and bio-based formulations.
- Price architecture is re-calibrating: Several leading manufacturers announced across-the-board price adjustments in early–mid 2026 to offset cost pressure and protect supply continuity. Pricing discipline, contract clauses, and transparent pass-through mechanisms will be decisive bargaining levers with large B2B customers.
- Capacity investments are migrating to high-value segments: Recent expansions target aerospace, specialty performance, and decorative capacity with automation upgrades — a clear signal that capital is being redeployed to higher-margin, technically demanding categories.
- Service and digital can unlock margin pools: Digital color platforms, predictive maintenance for applicators, and downstream service contracts are emerging as profitable extensions beyond paint sales.
Report contents: what the full study delivers (practical, action-oriented)
The full Paint Market study is designed as an operational toolkit for 2026 planning cycles. Highlights include:
- Executive summary with decision triggers tailored to CEOs, CFOs, Heads of R&D, and Commercial Leads.
- Top-line macro model (2020–2025 historical; 2026–2032 forecast) including sensitivity scenarios for input-cost shocks, regulatory acceleration, and cyclical demand swings.
- Competitive playbook: profiles and strategic positioning of global leaders, challenger brands, and regional champions, with go-to-market implications.
- Regulatory and standards compendium mapping compliance deadlines, anticipated enforcement risks, and product reformulation pathways.
- Raw material intelligence module: supply-chain maps, price trend drivers, and procurement mitigation options (contracts, vertical integration, alternative chemistries).
- Commercial execution tools: margin-by-channel diagnostics, pricing framework templates, and three ready-to-deploy sales pilots for industrial, architectural, and automotive customers.
- M&A screening framework: target archetypes, valuation multipliers by strategic thesis, and integration risk checklists.
- Technology and sustainability roadmap: product innovation levers, eco-labelling strategies, and digital adoption milestones with estimated ROI ranges.
- Priority actions for 0–12 months, 12–24 months, and 24–60 months horizons aligned to balance-sheet impact and operational feasibility.
- Appendices with model inputs, data sources, and reproducible scenarios — note: granular segment tables are intentionally withheld in this preview to preserve the report’s subscriber value.
Competitive landscape: strategic implications for named players
Our assessment of primary incumbents focuses on strategic posture rather than confidential segment shares. The following captures how capability and recent moves position each firm for 2026:
- Sherwin‑Williams (Cleveland, OH): Deep retail and professional channel strength positions Sherwin‑Williams to defend architectural margins. Expect continued investment in customer-facing services and loyalty mechanics to offset raw-material pressure.
- PPG Industries (Pittsburgh, PA): With a 2026 price adjustment across its portfolio, PPG is prioritizing margin resiliency and supply stability. Watch for contract renegotiations in industrial accounts and intensified focus on high-value coatings.
- AkzoNobel (Amsterdam): Recent capacity and automation upgrades for aerospace and decorative lines indicate a strategic tilt toward selective premium segments. Their R&D and sustainability narrative will be central to European and North American trade wins.
- Nippon Paint (Singapore HQ): Pan-Asian reach and surface-treatment systems create opportunities in high-growth, urbanizing markets. Localized innovation and channel partnerships underpin their expansion strategy.
- RPM International (Wickliffe, OH): A diversified brand portfolio that includes consumer favorites gives RPM defensive revenue streams and cross-selling opportunities as DIY and trade markets evolve.
- Axalta (Wilmington, DE): Automotive and industrial specialization, combined with refinish leadership, offers a hedge versus residential cyclicality but increases exposure to automotive production cycles.
- Jotun (Fornebu, Norway): Strong in marine and protective markets where technical qualification and long-term contracts favor incumbents; expect selective pricing power and niche expansion.
- Asian Paints (Mumbai): Dominant regional brand equity and distribution density enable rapid adoption of premium products in urbanizing markets; partnerships and technology licensing are probable next steps.
- Kansai Paint (Osaka): Japanese specialty and powder-coatings expertise supports OEM relationships; incremental gains likely through technology transfer and service models.
- BASF Coatings (Munster): High-performance solutions geared to automotive and industrial clients mean value capture depends on continuing OEM partnerships and eco-compliant product rollouts.
- Behr Paint (Anaheim): Consumer-oriented channel access and brand recognition position Behr to monetize home-improvement cycles through product innovation and retail collaboration.
Across these players, the strategic moves to track in 2026 are: pricing cadence and transparency, targeted capacity spend in specialty segments, and how each leverages sustainability certification as a commercial differentiator.
Regulation, raw-materials and operations: near-term shocks and structural shifts
- Regulatory updates: Amendments to aerosol coatings and lead-based paint standards in recent years have altered formulation roadmaps and reporting requirements. Compliance timetables require operational and ERP changes that procurement and quality teams must budget for now.
- Input inflation: Price drivers such as titanium feedstock increases materially impact cost of goods sold. Producers who have not secured hedging or alternate suppliers are likely to face margin compression or be forced into sharper price actions.
- Capital allocation: Investments in automated production and strategic capacity — especially for aerospace and specialty coatings — are accelerating. Capital discipline will be rewarded where investments target higher-margin niches and shorten lead-times.
Actionable 2026 playbook — five priorities for executives
- Implement short-term procurement hedges and contractual pass-through frameworks to stabilize margins while negotiations occur.
- Fast-track regulatory readiness programs: align R&D roadmaps with compliance timelines and prioritize product lines by strategic margin and customer risk.
- Pursue targeted capability acquisitions (color tech, bio-based chemistries, digital customer platforms) rather than broad M&A to maximize near-term ROI.
- Segment go-to-market by value: reserve premium service bundles and sustainability-certified SKUs for customers willing to pay, while optimizing cost-to-serve in price-sensitive channels.
- Operationalize a 24-month automation and SKU rationalization plan to capture productivity gains and reduce working-capital exposure.
Why access the full PW Consulting report
This preview outlines the strategic storyline: a mid-single-digit growth market, concentrated but contestable, operating under a new regime of input volatility and regulatory pressure. The full report provides the operational blueprints, scenario models, and the precise, segment-level market tables you will need to quantify revenue impact and prioritize investments in 2026. For commercial bids, M&A diligence, or to stress-test your 2026 P&L, the subscriber report is constructed to be directly actionable.
PW Consulting stands ready to support bespoke briefings, deep-dive workshops, and model customization to translate these insights into a defensible 2026 plan. Reach out through our standard channels to schedule an executive session and obtain the complete dataset and strategic appendices.
For detailed analysis of this topic, please visit the official page: Paint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com