

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flap Disc Market to Hit USD 7,948.29M by 2032 at 5.88% CAGR

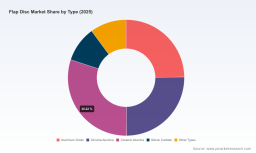
Flap Disc Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As industrial manufacturers and aftermarket specialists plan resource allocation for 2026, the global flap disc market warrants focused attention. Our latest market model shows a steady expansion from the early 2020s into the next decade, with compound annual growth of roughly 5.9%. The market has grown from the low‑billions range in 2020 to an estimated mid‑billions by the 2025 base year, and our forecast indicates continued expansion through 2032. The competitive structure is moderately consolidated — the top three suppliers account for a clear majority share, and the top five widen that control further — creating both barriers and opportunities for challengers and niche specialists.
Flap Disc Market
Why this research matters for 2026 strategic choices
- Portfolio prioritization: Decide which flap disc technologies and material formulations to expand, phase out, or bundle with services to protect margin in an evolving product mix.
- Supply chain resilience: Translate raw material trends and sourcing concentration into purchase strategies that reduce exposure to price and delivery shocks.
- Go‑to‑market design: Optimize channel mixes between distributors, OEM contracts, private label, and direct digital sales to capture end‑user shifts.
- M&A and partnership screening: Identify targets and partners that accelerate capability build (e.g., premium abrasive technologies, regional production nodes, or aftermarket services).
- CapEx and capacity planning: Align manufacturing investments with demand trajectories, technology shifts, and regional capacity needs to avoid over/under‑investment.
Market dynamics shaping the 2026 planning horizon
Three interlocking dynamics are driving the flap disc market today: materials and product innovation, structural shifts in end‑use consumption, and a changing supply‑chain geography.
Flap Disc Market
-
Materials and product innovation: Abrasive formulations and bond technologies have become primary differentiators. Ceramic and zirconia formulations, alongside engineered grain technologies from several global leaders, are enabling higher cut rates and longer life, shifting buyer willingness to pay for performance. Product innovation is less about marginal cost reduction and more about life‑cycle value—fewer disc changes per job, reduced downtime, and consistent finish quality.
Flap Disc Market -
End‑use evolution and automation: Metalworking remains the largest industrial consumer, but application profiles are evolving. Automation in fabrication and finishing, tighter surface specifications in advanced manufacturing, and cross‑industry use cases (e.g., aerospace, automotive, oil & gas) are changing demand elasticities. Where operators value cycle time and process reliability, premium products are gaining traction.
-
Supply‑chain and geographic dynamics: Cost‑competitive OEM production bases have expanded, while established Western brands maintain premium positioning through R&D, branded performance, and distribution networks. Buyers are therefore balancing price, lead time, and performance — a trade space that creates strategic openings for private label makers, regional specialists, and vertically integrated suppliers.
Competitive landscape — what we observed
The market exhibits a two‑tier competitive pattern: global industrial majors and specialized regional manufacturers. Global giants bring scale, branded innovation, and channel reach; regional specialists and Chinese OEMs offer manufacturing flexibility and competitive cost structures.
-
Global majors and premium innovators: Industrial leaders with strong R&D engines and broad distribution channels maintain leadership through proprietary abrasive technologies and brand trust. Their initiatives in engineered grain systems and bonded products create defensible high‑value segments, especially for industrial customers prioritizing throughput and finish consistency.
-
Regional specialists and private‑label producers: European niche manufacturers and private‑label contractors emphasize customization, short lead times, and specialized solutions. These players compete on service, formulation customization, and cooperation with distributors and OEMs for tailored programs.
-
China‑based OEMs and high‑volume suppliers: Suppliers with long OEM pedigrees and export‑focused platforms supply a wide spectrum of demand — from standard Aluminium Oxide discs to branded alternatives. Their role in price competition and global sourcing is significant, especially where buyers prioritize cost or seek supplier consolidation across geographies.
For procurement and product leaders, the implication is clear: compete on a mix of technology, integrated services, and channel economics. Top players protect share through product differentiation and distribution breadth, while mid‑tier companies exploit agility and cost leadership. Our company profiling in the full study maps these distinctions across capabilities, go‑to‑market models, and IP intensity, and includes actionable vendor scorecards for sourcing decisions.
What the PW Consulting report delivers (practical, operational content)
The report is designed as a hands‑on toolkit for executives making 2026 decisions. Highlights include:
- Robust market sizing and three‑scenario forecasts through 2032 built on historical 2020–2025 performance and forward drivers.
- Bottom‑up build methodologies and sensitivity testing so internal teams can re-run models with client‑specific assumptions.
- Vendor benchmarking and competitiveness matrices — covering R&D posture, product breadth, manufacturing footprint, private‑label capability, and channel partnerships.
- Supply‑chain maps and raw‑material cost drivers with contingency playbooks for procurement (hedging approaches, dual‑sourcing tactics, nearshoring triggers).
- Detailed go‑to‑market playbooks for premiumization, private label, and digital channels — including pricing frameworks, margin waterfalls, and sales incentive models.
- M&A and partnership screeners, including valuation heuristics, integration checklists, and early warning indicators for distressed or consolidation targets.
- Practical Excel deliverables: unit economics templates, production capacity planners, and a dashboard for tracking KPIs that matter (yield, cost per cut, downtime effects).
- Executive interviews and primary market intelligence gathered from manufacturers, distributors, and strategic buyers to validate assumptions and capture emergent practices.
Strategic implications — six moves to consider in 2026
-
Segment your portfolio by value‑capture opportunity: Differentiate between low‑margin commodity volumes vs. premium, high‑lifetime products. Reallocate R&D and commercial investment toward product lines where life‑cycle economics justify price premiums.
-
Lock in diversified sourcing for critical inputs: Implement dual‑sourcing or regional buffer capacity for abrasive grains and resin chemistry inputs; quantify the cost of supply interruptions versus the cost of inventory and hedging.
-
Deploy channel‑specific commercial plays: For distributors, emphasize margin structure and co‑marketing; for OEMs, offer bundled service and JIT programs; for industrial end users, package performance guarantees and uptime improvements.
-
Invest in product and process differentiation: Target technologies that deliver measurable throughput or finish improvements. Pilot programs with lead customers can validate value propositions faster than broad rollouts.
-
Evaluate bolt‑on acquisitions to accelerate capability: Seek targets that fill technology gaps, add regional manufacturing touchpoints, or expand aftermarket services. Use the provided M&A screeners to prioritize targets with clear synergies.
-
Embed sustainability and safety into the commercial story: Regulatory and customer pressure is increasing; product formulations and packaging choices that reduce waste or improve worker safety can become points of differentiation in tender processes.
How PW Consulting’s insights accelerate your 2026 planning
This briefing is intentionally selective — it surfaces the macro drivers, competitive shapes, and the types of decisions that will matter next year. The full PW Consulting Flap Disc Market study contains the granular segmentation, company profiles, and the quantitative tables you need to operationalize strategy. If you are building budgets, evaluating capacity investments, or screening M&A targets for 2026, the report provides not just the numbers, but the executable scenarios and playbooks to act with confidence.
To move from directional insight to an executable plan, stakeholders should integrate the report’s forecast and vendor diagnostics into their annual operating model, stress‑test supplier strategies under price and lead‑time shocks, and pilot differentiated product propositions with targeted end‑user segments. For those ready to accelerate, our advisory team can help translate the research into a tailored strategic roadmap, implementation milestones, and KPI dashboards aligned with your risk tolerance and growth ambitions.
Next step
Access the full study for detailed segmentation tables, the complete competitive profiles, and downloadable modeling tools that anchor the recommendations above. PW Consulting’s market intelligence is structured to support the decisive bets companies must place for 2026 and beyond — from portfolio pruning to capacity commitments and commercial transformation.
For detailed analysis of this topic, please visit the official page: Flap Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com