

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sink Market Set for 5.2% CAGR Through 2032

Sink Market 2026: A Strategic Preview for Corporate Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted, executive‑grade preview of our forthcoming Sink Market study. Built on a 2025 base, five years of historical tracking (2020–2025) and a forward view through 2032, this preview surfaces the strategic implications senior leaders must act on in 2026 — while preserving the granular segmentation and transactional intelligence that drive high‑confidence investment and sourcing decisions for subscribers to the full report.
Sink Market
Why 2026 is a Pivotal Year
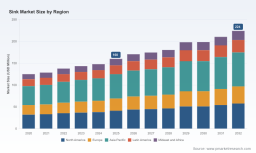
The sink market has moved beyond steady replacement cycles into a period shaped by regulatory tightening, materials innovation and changing channel economics. On a macro basis, the industry has grown from a market size in the low hundreds (Million USD) in 2020 to 160 Million USD in our 2025 base year. We forecast continued expansion through the 2026–2032 horizon at a compound annual growth rate of 5.2%, reaching a projected market size in the mid‑200s (Million USD) by 2032.
Sink Market
Two interlocking dynamics make 2026 especially consequential. First, certification and accessibility standards are tightening in key markets; in the United States, ADA accessibility requirements and NSF food‑contact certifications are being applied with renewed rigor across both commercial and public project scopes. Second, upstream supply considerations — notably recycled stainless content and resin availability for composite sinks — are reshaping manufacturers’ cost structures and ESG positioning. Together, these forces mean product design, procurement contracts and go‑to‑market strategies will determine winners and losers over the next three to five years.
Sink Market
What the Full Report Delivers (Practical, Actionable)
- Market sizing and validated forecasting (2026–2032) with scenario variants that stress‑test demand under alternative macroeconomic and commodity input trajectories.
- Demand drivers and channel playbooks for residential, commercial and specialty applications — including dealer networks, builder purchasing, hospitality specifiers and e‑commerce platforms.
- Supply‑chain heat maps and supplier concentration overlays, highlighting input risk points and near‑term sourcing windows for stainless, quartz and composite resins.
- Regulatory and certification impact analysis (ADA, NSF and analogous standards) with implementation roadmaps for product and manufacturing teams.
- Competitive benchmarking and capability matrices for leading OEMs, plus a watchlist of acquisition targets and private‑label opportunities.
- Price‑elasticity models, margin archaeology and a downloadable financial model to stress test pricing, raw material pass‑through and product mix scenarios.
- Commercial playbooks: route‑to‑market experiments, partnership templates for plumbing and appliance OEMs, and SKU rationalization frameworks to maximize SKU profitability.
Note: this preview intentionally omits the granular regional and application splits that underpin these frameworks. Full segmentation tables, price decks and transaction‑level vendor intel are available in the complete report.
Data‑Driven Insights Every Executive Should Internalize
- Market trajectory and scale: After steady growth over 2020–2025, the market enters a mid‑single‑digit growth phase. The headline CAGR of 5.2% through 2032 masks important variance across channels and materials — a divergence critical to portfolio planning.
- Fragmentation and concentration: The market remains fragmented. Our concentration analysis shows that the top three and top five players together account for under one‑third of industry revenue, signaling meaningful white space for regional specialists and disruptive new entrants with differentiated channels or proprietary materials.
- Material economics are strategic: Stainless steel continues as a backbone material but composite and engineered quartz products are securing share through styling, perceived durability and sustainability narratives. Select product lines already cite post‑consumer recycled stainless content levels exceeding 75% — a factor that both reduces lifecycle impact and introduces new supply dependencies.
- Regulation and certification are commercial levers: ADA accessibility requirements and mandatory NSF certification for food‑contact surfaces in targeted markets carry both compliance costs and barrier‑to‑entry advantages. Manufacturers that embed these requirements early in the design and supply chain capture specification wins in commercial build projects and public tenders.
- Design innovation as differentiation: Workstation sinks, integrated accessory ecosystems and smart integration (sensor taps, platform compatibility) are moving from premium niche to expected features in higher tiers. Product ecosystems that simplify installation and maintenance are winning specification votes with architects and hospitality operators.
- Channel shifts and margin compression: The growing influence of direct‑to‑consumer channels and online showrooms compresses traditional dealer margins but creates opportunities for branded aftermarket accessories, extended warranties and subscription‑style maintenance services.
Competitive Landscape — Profiles and Strategic Postures
The market’s leading OEMs combine legacy manufacturing scale with distinct strategic plays. Below are concise profiles and the strategic implications we examine in the full study:
- Elkay Manufacturing Company (Downers Grove, Illinois, USA — https://www.elkay.com)
Strengths: deep stainless engineering capability and expanding recycled stainless offerings. Strategic implication: Elkay is well positioned to capture buyers prioritizing documented recycled content and tight product certification pathways.
- Kohler Co. (Kohler, Wisconsin, USA — https://www.kohler.com)
Strengths: portfolio breadth spanning stainless, fireclay and luxury quartz, plus embedded ADA and smart integration features. Strategic implication: Kohler’s premium play benefits projects where integrated fixtures and digital features are specifiers’ priorities.
- BLANCO America (Ottawa, Illinois, USA — https://www.blancoamerica.com)
Strengths: granite composite expertise and workstation models. Strategic implication: BLANCO competes on utility and lifestyle‑oriented design, attractive to higher‑end residential and custom builders.
- Franke Group (Schaan, Liechtenstein — https://www.franke.com)
Strengths: diversified material set and workstation innovation with strong presence in integrated kitchen systems. Strategic implication: Franke’s systems approach supports cross‑sell into appliances and plumbing accessories.
- Kraus USA (San Jose, California, USA — https://www.kraususa.com)
Strengths: range includes undermount, farmhouse and workstation sinks with strong value positioning. Strategic implication: Kraus can leverage design trends toward open‑plan kitchens and durable finishes.
- American Standard Brands (Jersey City, New Jersey, USA — https://www.americanstandard-us.com)
Strengths: apron‑front and undermount stainless product lines targeting replacement and retail channels. Strategic implication: well‑placed for mid‑market refurbishment cycles.
- Just Manufacturing (New Berlin, Wisconsin, USA — https://www.justmfg.com)
Strengths: commercial‑grade stainless sinks for institutional and hospitality use. Strategic implication: a natural beneficiary of hospitality reopenings and healthcare facility retrofits, given compliance focus.
- Karran USA (Scottsdale, Arizona, USA — https://karran.com)
Strengths: stainless steel and quartz offerings with design emphasis. Strategic implication: positioned for specifiers seeking hybrid material aesthetics with manageable price points.
- Swanstone (Elk Grove, Illinois, USA — https://swanstone.com)
Strengths: composite drop‑in and undermount sinks with strong dealer relationships. Strategic implication: plays well in renovation channels where installation simplicity matters.
Our competitive scoring model evaluates these firms across product breadth, certification readiness, channel coverage, supply resilience and sustainability credentials. The full benchmark includes vendor scorecards and recommended co‑investment or divestiture options for strategic buyers.
Scenario Planning & Strategic Choices for 2026
- Baseline (Apply the 5.2% CAGR): Continue investment in certification roadmaps, maintain SKU discipline and prioritize channel optimization initiatives that increase direct engagement with specifiers and builders.
- Premiumization Acceleration: If higher‑end remodels and smart integration accelerate, allocate R&D to integrated accessory ecosystems and increase marketing spend to capture specification share.
- Commodity Pressure / Input Shock: If stainless and composite resin costs spike, pivot to vertical integration of key inputs, reprice strategically, and accelerate low‑cost production footprints.
For each scenario the report provides decision matrices that convert market signals into time‑phased actions: where to invest, when to consolidate, and what capabilities to outsource or build in‑house.
Regulatory & Sustainability Imperatives — Immediate Actions
- Embed ADA and NSF requirement mapping into product development cycles for any products sold or specified in commercial and public projects; failure to do so will materially reduce competitiveness in institutional tenders.
- Develop documented recycled‑content claims and supplier attestations. Early movers attesting to high post‑consumer recycled stainless content are differentiating on ESG criteria — and in some cases securing procurement preferences.
- Align warranty and service offerings with lifecycle expectations driven by material choice. Composite and quartz lines require distinct maintenance and service playbooks compared with stainless products.
How to Use This Preview — Next Steps
- If you are preparing 2026 CAPEX or M&A plans: use the scenarios and downloadable financial models in the full report to stress test acquisition multiples and plant investment timing.
- If you lead product or channel strategy: deploy the certification and go‑to‑market checklists to revalidate current roadmaps and prioritize certification spend against expected returns.
- If you are in procurement or operations: request the supplier heat maps and input sensitivity analysis in the full study to lock in supply contracts and hedging strategies for the coming twelve months.
This preview is engineered to help executive teams ask the right questions in 2026. It demonstrates the depth of analysis PW Consulting applies while deliberately withholding the detailed segmentation and transaction intelligence that power near‑term deals and sourcing plays. For the full dataset, segment breakdowns, vendor scorecards, Excel models and the complete strategic playbook, please access the full Sink Market report on our website or contact your PW Consulting representative.
Prepared by the PW Consulting Industry Team — we look forward to partnering with you to turn market insight into decisive action.
For detailed analysis of this topic, please visit the official page: Sink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com