

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Condom Market Poised for 8.42% CAGR Through 2032

Condom Market — 2026 Strategic Preview: What Leaders Must Know Before Their Next Move
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused, decision-oriented preview of our forthcoming Condom Market research — calibrated to the immediate strategic needs of C-suite and commercial leaders planning for 2026. Built on a rigorous base year (2025) and a seven-year forecast horizon (2026–2032), our analysis projects the global market to expand at a compounded annual growth rate (CAGR) of 8.42%. In dollar terms the market grows meaningfully from its 2025 baseline to a materially larger global opportunity by the end of the forecast. This preview outlines why that trajectory matters, which competitive and structural forces will shape outcomes, and the concrete actions executives should prioritize in 2026. True to the “trailer” principle, we demonstrate methodological depth and strategic implications while directing readers to the full report for granular segmentation and proprietary datasets.
Condom Market
Why this report matters for 2026 decisions
- Timing: 2026 is a pivotal year where product innovation cycles, raw-material volatility and shifting consumer preferences converge. Our report isolates the decision levers that produce asymmetric value within that window.
- Resource allocation: With mid-single-digit to high-single-digit growth across the sector, marginal investments in product premiumization, supply resilience and channel automation can yield outsized returns — if directed to the right subsegments and geographies.
- Risk management: Supply-chain shocks and regulatory shifts in key markets have created near-term profit and availability risks. Executives who adopt hedging, dual-sourcing and contractual flexibility will preserve margin and brand trust.
Market dynamics shaping 2026–2032
- Raw-material and input-cost shocks: Recent industry developments underscore that raw-material availability is no longer a background variable. Disruptions tied to geopolitical conflict have led major manufacturers to signal double-digit price adjustments. For manufacturers and private-label players this crystallizes the need for multi-sourced polymer strategies, longer-term supplier contracts and real-time cost-to-serve analytics.
- Product innovation and new materials: Demand for ultra-thin formats, advanced coatings and alternative polymers (including graphene-enhanced and synthetic lines) is rising. This is driving two parallel paths: premiumization for higher margins, and material substitution where latex supply is constrained.
- Sustainability and consumer values: Brands are increasingly judged on environmental credentials. Vegan and biodegradable formulations are moving from niche to mainstream, creating both formulation challenges and premium-pricing opportunities for brands that can credibly substantiate claims.
- Regulatory and clinical differentiation: New approvals for coated and novel-formulation products are accelerating route-to-market complexity. Firms investing early in regulatory dossiers and clinical evidence will gain first-mover advantages in tightly regulated markets.
- Channel evolution: Retail packaging, point-of-sale visibility and e-commerce optimizations remain central. Recent retailer-focused packaging initiatives illustrate how modest SKU and pack innovations can materially improve shelf performance and online conversion.
Competitive landscape — concentration, capabilities and strategic intents
The market is meaningfully concentrated among a handful of global and regional manufacturers. The top-tier producers combine large-scale manufacturing capabilities with both branded and contract-manufacturing exposure, creating a dynamic interplay between branded market-share defense and OEM-driven margin pools.
Condom Market
- Karex Berhad (Kuala Lumpur) commands scale as the industry’s largest contract manufacturer and remains the structural fulcrum for private-label and public-health channels. Karex’s moves — including new synthetic product lines announced for commercial rollouts — materially influence capacity pricing and contract dynamics across the value chain.
- Large FMCG brand owners (owners of legacy, high-recognition brands) remain focused on product differentiation, channel control and broader sexual-health portfolios. Their brand equity enables premium pricing and trade leverage, but they must also manage upstream cost pressures.
- Technology-driven and specialty firms (notably producers of ultra-thin, premium and coated products) are translating material science advancements into commercial propositions. Regulatory certifications for novel coatings and polymers have started to unlock new premium segments.
- Regional champions and vertically integrated manufacturers sustain important local advantages in logistics, regulatory know-how and established trade partnerships — making them prime partners or targets for bolt-on capacity and market access.
Strategic implication: competition is not just about share; it is about capability — manufacturing flexibility, regulatory pathways, material science IP, and channel orchestration. The top tier of players exerts outsized influence on pricing and availability, and mid-tier consolidation is accelerating.
Condom Market
What the full report delivers (practical, actionable content)
Our full-market study is built for executives who need to move from insight to action. Highlights include:
- Proprietary topline and bottom-up market sizing (base year and historical series, forecasting through 2032), with scenario variants keyed to raw-material stress, premiumization uptake and regulatory shocks.
- Supply-chain and cost-to-serve heatmaps, showing where freight, input-cost and lead-time risks cluster — and how these risks propagate to retail availability and margin erosion.
- Competitive scorecards for the primary manufacturers and brands, evaluating manufacturing scale, innovation pipeline, regulatory positioning and channel strength.
- Commercial playbooks for four strategic priorities: product premiumization (materials, coatings, claims), channel expansion (retail vs. e‑commerce vs. institutional), pricing architecture (promotional cadence and contractual hedges), and sustainability roadmaps (certifications, lifecycle claims).
- M&A and partnership shortlists: an executable map of target profiles by capability, geography and valuation tiers, plus an acquisition integration checklist focused on capacity, IP and regulatory transferability.
- Go-to-market frameworks and sample P&L simulations that convert market-share moves into EBIT sensitivity — designed to inform board-level capital allocation decisions.
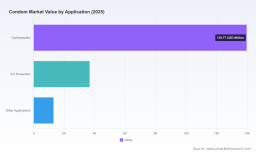
To remain a compact preview, we intentionally withhold detailed segment splits and granular regional revenue tables here; the full report provides those model outputs and interactive dashboards.
Strategic pathways for executives in 2026
- Diversify upstream exposure now. Implement dual- or multi-sourcing strategies for key polymers and coatings, paired with financial hedges and contractual indexation to mitigate the immediate risk of input-price volatility.
- Prioritize material science where price and customer willingness-to-pay converge. Invest selectively in ultra-thin, graphene-enhanced, or synthetic lines that command premium positions, but use staged launches with controlled SKUs to validate acceptance.
- Make sustainability a measurable strategy, not a public-relations exercise. Define a 3–5 year roadmap with measurable KPIs (biodegradability, carbon intensity, vegan formulations) and accelerate low-cost entry points such as eco-packaging and lifecycle labeling.
- Lock regulatory pathways early for coated and novel products. Regulatory certification timelines are a gating factor for premium product launches; securing approvals in lead markets accelerates global rollouts and reduces commercial risk.
- Design channel-specific value propositions. Use retailer co-investment, private-label bundling and direct-to-consumer pilots to test price elasticity, pack formats and subscription offers — then scale the commercial model that delivers the best unit economics.
- Use M&A and JVs tactically to secure capacity or proprietary coatings/IP. Where building capacity is long-dated, partnerships or minority equity stakes can provide immediate supply assurance and strategic optionality.
Scenario readiness — simple stress cases to run immediately
Our report includes three executive-ready scenarios you should model into 2026 planning:
- Raw-material shock: sustained input-cost escalation and constrained supply for 12–18 months — tests pricing pass-through, margin protection and brand elasticity.
- Regulatory acceleration: faster-than-expected approvals unlock premium-coated products — tests commercialization tempo and manufacturing scale-up.
- Sustainability premium adoption: consumer willingness-to-pay for certified eco-products reaches a tipping point — tests SKU rationalization and supply-chain retooling economics.
How to use this preview and where to find the full intelligence
Consider this preview a strategic north star. Use it to align leadership on the immediate bets for 2026: sourcing, product roadmaps, and capital allocation. Our full report — available on the PW Consulting landing page — contains the granular breakdowns, interactive spreadsheets and company-level dossiers required to operationalize these recommendations. There you will find the complete segmentation matrices, the underlying forecasting assumptions, supplier rankings and a downloadable scenario-model workbook.
For boards, business unit heads and M&A teams preparing 2026 plans, the key question is not whether the market will grow — it will — but who captures the margin and resilience premium. Firms that pair material and regulatory foresight with channel agility and purposeful sustainability positioning will be positioned to lead the next growth cycle.
PW Consulting stands ready to support implementation: from rapid supply-chain stress testing to transaction diligence and commercial transformation playbooks. Contact our team to schedule a briefing and unlock the full datasets and execution templates.
For detailed analysis of this topic, please visit the official page: Condom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com