

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Power Banks Market to reach USD 28.85B by 2032 at 6.97% CAGR

Power Banks Market: Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused preview of our new Power Banks Market study — designed to equip executives making critical 2026 decisions. This article highlights the strategic implications of recent market evolution, supply-chain shocks, and competitive moves, and it explains how the full study converts those dynamics into executable choices. Consider this a high-fidelity trailer: we expose the analytical backbone and line-of-sight recommendations while intentionally reserving the granular segmentation tables and proprietary models for the full report.
Power Banks Market
Market trajectory — the headline numbers that matter
The portable power market has transitioned from a utility accessory into a strategic product line for device OEMs, accessory brands and channel partners. On a macro level, the market expanded from a baseline of USD 12,800 million in 2020 to USD 18,000 million in 2025 (base year). Our forecast through 2032 projects the market to approach USD 28,850 million by 2032, growing at a compound annual growth rate of 6.97% over the 2026–2032 forecast period (all figures in USD Million). These topline dynamics underline a sustained, mid-single-digit growth environment where product differentiation, distribution reach and supply resilience will determine winners.
Power Banks Market
What these numbers imply for 2026 strategy
- Scale without hyperconcentration: market concentration metrics indicate a moderately fragmented landscape (CR3 ~35.2%; CR5 ~44.6%). That structure creates space for fast followers to scale, but also rewards leaders who invest in brand, channel depth and technical differentiation.
- Growth is durable but selective: aggregate growth masks important divergence across form factors, charging technologies and enterprise-use cases. The tactical decision for 2026 is not whether to play in power banks — it is where and how to play to capture higher-than-market returns.
- Margin pressure is real: rising upstream costs and tariff/regulatory shifts are compressing input cost variability. Pricing strategies must align with cost-hedging and value-based feature sets rather than simple unit-cost competition.
Key market dynamics shaping 2026 choices
- Technology convergence: Power banks have moved beyond battery capacity as the primary differentiator. Integration of USB Power Delivery (PD), Programmable Power Supply (PPS), GaN-based chargers, MagSafe-style magnetic wireless and bidirectional fast charging are now baseline expectations for premium SKUs. Portfolio architects must weigh incremental BOM costs against the willingness-to-pay of target channels (retail, D2C, OEM bundles).
- Product premiumization and fragmentation: A clear bifurcation is occurring between ultra-slim, lifestyle magnetic wireless units and high-capacity, laptop-grade power banks with 100W+ outputs. This dual structure increases SKU complexity for manufacturers and distributors, making configuration, inventory and channel alignment real operational constraints.
- Raw-material and supply-chain volatility: Battery producers increased prices in response to a recovery in lithium and critical minerals during 2025, and industry forecasts in early 2026 point to further battery-supply inflation (roughly +10% year-over-year in battery input prices as of January 2026 forecasts). Concurrent policy actions — such as steep tariffs on certain Chinese battery feedstocks and export controls on strategic minerals — are amplifying sourcing risk and regionalization pressures. These supply-side shocks demand proactive procurement strategies and potentially localized sourcing or near-shoring.
- Regulatory & geopolitical spillovers: Recent export controls and tariffs affecting graphite and rare-earth materials, along with updated export rules in certain jurisdictions, create both compliance overhead and strategic arbitrage opportunities for firms that anticipate policy shifts and restructure supplier relationships early.
- Channel & use-case diversification: While consumer smartphone charging remains a core volume driver, there is incremental demand for laptop-grade power banks, enterprise field kits, and accessory bundling with premium devices. Companies that build differentiated GTM motions for these channels will extract disproportionate value from otherwise modest market growth.
Competitive landscape — who matters and why
The competitive field is populated by specialized accessory brands, device OEMs and an active cohort of fast-moving Shenzhen innovators. Several names are shaping product and channel benchmarks:
Power Banks Market
- Anker Innovations (Changsha, China — https://www.anker.com): A category-defining player known for high-efficiency battery packs, broad implementation of USB Power Delivery, GaN-enabled chargers and proprietary fast-charge algorithms (PowerIQ + PD). Anker’s strengths are scale in manufacturing, retail visibility and a broad SKU matrix.
- Xiaomi (Beijing, China — https://www.mi.com): With its ZMI line and HyperCharge capabilities, Xiaomi emphasizes bidirectional fast charging and cost-effective engineering, often using aggressive pricing to capture share across emerging markets.
- UGREEN (Shenzhen, China — https://www.ugreen.com): Notable for the Nexode portfolio that blends PD/PPS charging with high-capacity variants and MagSafe-compatible designs. UGREEN’s approach illustrates how third-party accessory brands are pushing premium specs into mid-market price bands.
- Baseus (Shenzhen, China — https://www.baseus.com): Focused on industrial design and convenience features (e.g., retractable cables, GaN integration), Baseus competes on design-led differentiation for retail channels.
- Belkin (El Segundo, USA — https://www.belkin.com): Belkin’s BoostCharge series typifies the premium wireless/magnetic play, combining Qi2 25W wireless capability with slim, brand-forward devices that target OEM partnerships and retail premium segments. Notably, Belkin launched UltraCharge Pro Power Bank 10K with Qi2 25W in January 2026, signalling continued product-up innovation among incumbents.
- Samsung (Seoul, South Korea — https://www.samsung.com): Samsung’s power banks emphasize multi-port support and higher-power outputs (e.g., 45W), leveraging OEM reputational advantage for seamless device integration.
- AUKEY, RAVPower, Mophie : These brands each demonstrate niche specialization — from magnetic wireless designs to 100W+ laptop-capable chargers and MagSafe-focused compact units — underscoring the multiplicity of viable plays within the overall market.
Recent product and market moves to watch
- Belkin’s January 2026 UltraCharge Pro launch reinforces the premium magnetic wireless segment and raises the bar for Qi2-certified, higher-output portable chargers.
- Smaller entrants, such as Proper Hills’ May 2026 ultra-slim alloy magnetic power bank, show continued product innovation in industrial design and a race toward the thinnest, most convenient forms for cable-free use.
- Collectively, these launches signal intensified competition at premium price points and confirm that differentiation is increasingly incremental — centered on magnetic systems, integration with device ecosystems, and form-factor innovation.
What the PW Consulting report delivers (practical contents)
Our full study converts market signals into operational blueprints tailored for three corporate archetypes: OEMs seeking accessory strategies, accessory brands scaling internationally, and investors evaluating M&A or growth-stage opportunities. Key deliverables include:
- Market-sizing model (historical 2020–2025, base year 2025; forecast 2026–2032) with scenario outputs aligned to commodity price and tariff shocks.
- Competitive heatmap with capability scoring (product architecture, channel strength, R&D, margin profile) across leading and emergent suppliers.
- Supplier risk matrix and recommended mitigation levers (dual-sourcing, local assembly playbooks, long-term contracts, strategic inventory buffers).
- Go-to-market playbooks by route-to-market (retail, D2C, telco bundles, enterprise) with recommended SKU rationalization and price-pack architecture.
- CapEx and R&D prioritization guide: tradeoffs between investing in GaN, PD/PPS, magnetic wireless and battery capacity versus software/firmware differentiation.
- M&A and partnership screen: target characteristics, valuation multiples benchmarks and integration risk checklists.
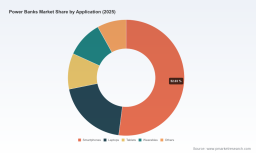
Note: to preserve strategic value for subscribers, the report’s granular segmentation tables (regional and application splits, capacity tiers and battery-type breakdowns) and downloadable models are available only in the full document and interactive dashboard.
Actionable recommendations for 2026
- Reassess sourcing strategy now: With battery-input price volatility and policy-driven tariffs, adopt staged supplier diversification and secure multi-year offtake agreements for critical cells and magnets. Consider vertical tie-ups or minority stakes with cell suppliers if your scale justifies it.
- Prioritize modular product architecture: Design platforms that allow interchangeable power modules (wireless puck vs wired module, different capacity packs) so you can rapidly rebundle SKUs across channels without retooling manufacturing lines.
- Value-based pricing & bundling: Move away from unit-price competition. Bundle fast-charge features, certified wireless capabilities and extended warranties in channel-specific packs that protect margin while simplifying SKU proliferation.
- Channel-led product segmentation: Create distinct roadmaps for OEM co-branded units, premium retail magnetic chargers, and price-competitive mass-market SKUs. Differentiate GTM motions and inventory strategies for each.
- Invest in compliance & IP: Given evolving export controls and tariff regimes, strengthen trade compliance capabilities and secure IP around firmware-based charging optimization to create non-BOM defensibility.
- Prepare financial hedges: Protect margins with commodity hedging where feasible, and model scenario impacts (tariffs, +10% battery costs) on NPV and break-even for new product programs.
- Use M&A tactically: For incumbents seeking rapid capability buildout, focus M&A on technology enablers (e.g., GaN expertise, magnetic coupling tech) or regional distribution specialists to accelerate market access without long organic lead times.
How to use this research in boardroom decisions
For product leaders and CFOs preparing 2026 budgets, this research should be the primary input for capex prioritization, sourcing contingencies and channel incentive design. For corporate development teams, use the competitive heatmap and M&A screen to refine target lists and valuation assumptions. And for operations, the supplier-risk and SKU rationalization sections become the roadmap for manufacturing flexibility and inventory turn optimization.
PW Consulting’s full Power Banks Market report provides the granular segmentation, model access and scenario analyses required to implement the recommendations above. If your team is evaluating product-line pivots, supplier commitments, or M&A targets in 2026, the detailed appendices and downloadable models in the full study will be indispensable.
Next steps
To access the complete analysis, proprietary models and the full set of segmentation tables that underpin the recommendations summarized here, visit PW Consulting’s report page or contact your PW advisor. We can arrange a targeted briefing to walk your leadership team through the scenarios most relevant to your business and to tailor the model inputs to your balance-sheet and production constraints.
In an environment of steady demand growth but heightened supply risk and product convergence, the 2026 strategic advantage will go to organizations that pair disciplined procurement with modular product architectures and channel-specific monetization strategies. The full PW Consulting study turns those imperatives into a prioritized, executable roadmap.
For detailed analysis of this topic, please visit the official page: Power Banks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com