

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
2-Ethylhexanoic Acid Market to Reach USD 1,500 Million by 2032 at 5.12% CAGR — PW Consulting

2-Ethylhexanoic Acid Market: A Strategic Outlook for 2026 Decision-Making
Executive preview
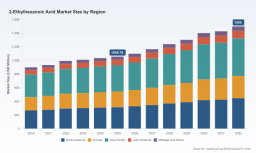
For executives weighing investments, procurement strategies, product portfolio choices, or M&A in 2026, a nuanced understanding of the 2-ethylhexanoic acid (2-EHA) market is now table stakes. PW Consulting’s latest market study—anchored on 2025 as the base year—documents a steady recovery and structurally positive medium-term outlook: the market rose from approximately USD 899 million in 2020 to USD 1,056.8 million in 2025 and is projected to reach USD 1,500 million by 2032, reflecting a blended CAGR of about 5.12% across the forecast horizon. This trajectory is driven by resilient end-market demand for plasticizers, stabilizers, lubricants and specialty intermediates, alongside capacity moves and regulatory drivers that will re-shape commercial dynamics in 2026 and beyond.
2-Ethylhexanoic Acid Market
Why this research matters for 2026 corporate choices
-
Timing of capital decisions: With the market on a mid-single-digit CAGR path, incremental capacity and debottlenecking projects can be accretive if executed with disciplined cost controls and offtake certainty. Our analysis quantifies the implied demand base growth that justifies new-builds vs. strategic partnerships.
2-Ethylhexanoic Acid Market -
Procurement and supplier risk management: Feedstock price behavior—especially propylene dynamics observed in Asia in 2025—has materially influenced production economics. Purchasing teams must translate feedstock scenarios into contractual protections to avoid margin compression.
2-Ethylhexanoic Acid Market -
Regulatory and product stewardship risk: New testing obligations and classification moves in major jurisdictions create compliance-driven costs and potential market access friction. Early movers that embed regulatory-readiness into product development and commercialization will gain a durable advantage.
Market trajectory and structural drivers
The headline numbers conceal important structural shifts. Between 2020 and 2025 the market expanded solidly, reflecting both cyclical recovery and substitution patterns across end uses. Forecasts to 2032 show continued expansion—reaching approximately USD 1,500 million—underscoring a market that is large enough to support multiple global producers yet dispersed enough that regional supply moves and product positioning can create outsized commercial outcomes for first movers.
Key demand drivers we track include: continuing demand for plasticizers and PVC additives in infrastructure and consumer goods, steady consumption in lubricant and specialty chemistries, and niche growth in personal care and pharmaceutical intermediates. On the supply side, technology choices (oxo-process vs. other synthetic routes), scale economics, and feedstock access determine competitive unit costs and the ability to service export markets.
Competitive landscape — concentration and capability implications
The 2-EHA market is neither a pure commodity nor a boutique specialty space. Market concentration metrics indicate moderate aggregation: the top three players control a meaningful but not dominant portion of supply, and the top five increase that share further. This structure creates a marketplace with room for vertically integrated majors, regional champions, and nimble local producers all to coexist.
-
BASF SE — A global integrator with Verbund advantages and recent capacity investments in the Asia-Pacific corridor. The company’s operational breadth offers price and supply resilience; recent capacity commissioning in Malaysia is a pivotal inflection point for regional availability.
-
Perstorp Holding AB — The owner of very large nameplate capacity; its scale is a strategic asset for serving global plasticizer and additives demand with reliability and long-term contracts.
-
The Eastman Chemical Company — A downstream-focused producer where 2-EHA functions as a critical intermediate across lubricants, metal salts, and specialty chemistries. Eastman’s integration affords route-to-market flexibility.
-
OXEA, KH Neochem, OQ Chemicals and other European and Japanese suppliers — These players offer alternative process routes and differentiated product grades; they are important partners for customers seeking consistent technical specifications or localized supply.
-
Chinese producers and regional players — Several Chinese manufacturers and other regional suppliers provide low-cost, high-volume supply for industrial applications and regional markets. Their presence has structural effects on global pricing and spot availability.
For market participants, the implication is clear: scale and integration reduce vulnerability to short-term shocks, but agility and product differentiation can capture margin in applications where regulatory or performance attributes matter. Our full report maps plant locations, route economics and service models—information that is essential when evaluating contracts or potential acquisitions.
Recent industry developments with strategic implications
-
Capacity expansion: A significant ramp in Asia-Pacific capacity was inaugurated in late 2024, materially increasing regional availability and creating new arbitrage pathways. Buyers and competitors must reassess pricing curves and logistics to understand which markets will become net exporters or maintain import dependency.
-
Feedstock environment: Relative propylene price stability in Asia through 2025 helped stabilize production costs for synthetic routes. However, the sensitivity of unit costs to feedstock volatility remains high—scenario analysis is essential for procurement and pricing strategies.
-
Regulatory changes: From a compliance standpoint, recent actions are consequential. U.S. federal testing requirements under TSCA (effective 2026), inclusion on California’s Proposition 65 list for reproductive toxicity (2025), and Oregon’s designation as a high-priority chemical for children’s health (effective 2025) together create a near-term compliance wave that will influence labeling, formulation, and potentially product acceptance in sensitive applications.
-
Trade policy: Introduction of a tariff at a modest MFN rate on the relevant HTS code alters landed-cost math and could influence sourcing footprints, especially for trade lanes where margins are thin.
Operational risks and regulatory playbook for 2026
Regulatory developments are the most immediate operational hazard for many commercial plans. Companies should not treat these as box-ticking exercises; rather, integrate them into commercial strategy through four practical steps:
-
Regulatory impact assessment: Rapidly quantify which SKUs and customer segments are affected, estimate incremental compliance costs and time-to-market impacts, and prioritize mitigation by commercial criticality.
-
Formulation and substitution pathways: Where applications touch consumer products or sensitive end markets, accelerate qualification of alternative chemistries or higher-purity grades to retain customers and protect shelf-space.
-
Supply-chain segmentation: Implement dual-sourcing and tariff-aware routing for material flows that are exposed to newly applied trade measures to avoid single-point disruption.
-
Stakeholder engagement and advocacy: Proactively engage regulators and industry consortia to shape test designs, timelines, and data interpretation—this can materially reduce downstream compliance risk and commercial uncertainty.
What the PW Consulting report delivers — practical, transaction-ready intelligence
The full study goes beyond macro narrative. It equips decision makers with tools and modules that can be applied directly in 2026 planning cycles:
-
Scenario-based demand models tied to end-market KPIs, enabling stress-testing of CAPEX and offtake assumptions under diverse economic and regulatory pathways.
-
Competitive playbooks including plant-by-plant capability mapping, process routes, and likely marginal-cost positions—essential for pricing strategy and M&A target screening.
-
Supply-risk matrices informed by feedstock exposure and trade policy, with actionable mitigation options and sourcing roadmaps designed for procurement teams.
-
Regulatory readiness checklists and cost-estimation templates to translate testing and classification requirements into 12–24 month execution plans.
-
Commercial templates—market-entry scorecards, distributor assessment frameworks and customer segmentation matrices—so commercial teams can convert intelligence into sales outcomes.
How executives should use this intelligence in 2026
At the portfolio level, prioritize three categories of action:
-
De-risk: Secure multi-source supply agreements with contractual protections for feedstock fluctuation and tariff exposure; diversify logistics corridors where practical.
-
Differentiate: Invest selectively in higher-margin grades or services (technical support, spec guarantees) where regulatory or performance attributes create pricing power.
-
Capitalize: Use acquisition or JV strategies to obtain scale in strategically important regions or to secure advantaged feedstock positions—focus on targets where integration yields immediate synergies.
Final takeaway — the strategic premium of intelligence
2026 will be a year in which tactical agility meets structural change in the 2-ethylhexanoic acid market. The growth path is constructive, but regulatory and trade dynamics will reallocate margin and market share. Firms that pair disciplined commercial modelling with pragmatic regulatory readiness and supply-chain redesign will unlock a premium on returns. PW Consulting’s market study synthesizes the quantitative trajectory, competitive anatomy and operation-ready playbooks required to make those decisions with confidence.
Note: This overview is intentionally high-level to illustrate strategic themes. The full report includes granular regional and application breakdowns, plant-level analyses, price and cost curve models, and detailed company profiles that support transaction diligence and procurement contracts. Access the complete dataset and proprietary models on our report page to operationalize the insights presented here.
For detailed analysis of this topic, please visit the official page: 2-Ethylhexanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com