

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Transformer Market Poised for 7% CAGR — PW Consulting Market Insight

Transformer Market 2026: Strategic Imperatives for Executive Decision-Making
Overview
As PW Consulting’s flagship Transformer Market study prepares to guide boardrooms and procurement desks through 2026, the industry faces a rare combination of sustained demand, concentrated supply-side pressure, and policy-driven disruption. Our analysis shows the global transformer market advancing on a steady trajectory from the 2020s into the early 2030s, underpinned by grid modernization, renewables integration, and expanding data center and industrial electrification loads. The market grows at a compound annual growth rate (CAGR) of approximately 7.0% across the forecast horizon, with the base year set at 2025 and scenario coverage through 2032.
Transformer Market
For executives evaluating capital allocation, supplier strategy, or M&A opportunities in 2026, the practical value of this research is threefold: it converts headline market expansion into actionable decision rules; it identifies where material and regulatory shocks will exert tactical pressure; and it translates competitive dynamics into near-term win-sets for incumbent and challenger players alike. This article previews the strategic takeaways—enough to prioritize actions today—while reserving the granular segmentation and vendor scorecards for the full report.
Transformer Market
Why 2026 Is a Strategic Inflection Point
- Demand is broad and persistent. Multiple demand vectors—transmission upgrades, renewable interconnections, electrified industrial loads and hyperscale data centers—are collectively lengthening planning horizons for utilities and large energy consumers. Growth is not ephemeral; it is structural, underpinning multi-year procurement cycles and long lead-time investments.
- Supply constraints and input-cost volatility amplify execution risk. Long lead times for large power units have become the default operating environment, forcing buyers to plan two-to-three years further ahead than typical procurement calendars. Concurrently, key raw materials (notably copper and electrical steel) have experienced step changes in cost that materially affect manufacturer pricing and margin dynamics.
- Policy and trade interventions are re-shaping competitive advantage. Recent regulatory efficiency requirements and trade measures are altering sourcing calculus and creating wedges for local manufacturers and vertically integrated suppliers.
How the Report Converts Macro Trends into 2026 Decisions
Executives need frameworks, not just forecasts. PW Consulting’s Transformer Market study delivers repeatable frameworks that convert the macro narrative into actionable measures across procurement, product strategy, and corporate development.
Transformer Market
- Procurement playbook for long lead-time purchasing. The report maps a multi-year displacement model for long-lead power units, showing when to shift from spot sourcing to structured supply agreements, and which contract features (capacity reservations, index-linked pass-throughs, phased deliveries) materially reduce total cost of ownership under lead-time stress.
- Materials hedging and specification levers. We translate raw-material volatility into hedging triggers and technical levers (core material selection, copper reduction strategies, alternative conductor options) that procurement and engineering teams can use to preserve performance while buffering price exposure.
- Regulatory scenario routing. With updated efficiency standards and trade policy events integrated into probabilistic scenarios, the report prescribes compliance-first and opportunity-first options for OEMs and buyers—i.e., how to cost-effectively transition product portfolios to new efficiency baselines without sterilizing legacy demand.
- Make-vs-buy and localization decisions. Using an operations economics lens, the study highlights the thresholds at which in-region manufacturing, joint ventures, or contract assembly materially improve lead times and margin capture, while accounting for tariff and logistics regimes.
- Merger & acquisition targeting and integration playbooks. The study identifies capability adjacencies and margin pools where bolt-on acquisitions can accelerate product diversification (e.g., medium-voltage specialty, dry-type solutions, grid automation integration), and outlines integration priorities to secure synergies in procurement and engineering.
Report Contents — Practical, Executable Modules
The full Transformer Market report is structured to be immediately operational for strategy teams. It contains:
- Executive dashboards that translate the 2020–2025 historical baseline and the 2026–2032 forecast into procurement planning horizons and CAPEX budgets;
- Scenario-based demand models that stress-test customer segments against combinations of material-price shocks, regulation tightening, and demand surges from renewable and data center projects;
- Supplier and capability mapping (including an indexed competitive scorecard), with strategic recommendations for partnerships and supplier development programs;
- Regulatory impact matrices showing compliance timelines, retrofit risk windows, and incentive-alignment opportunities across major jurisdictions;
- Operational playbooks on inventory strategy, capacity reservation contracts, and conditional sourcing that reduce the risk of project slippage in a long-lead environment;
- Commercial templates—RFP structures, supplier qualification checklists, and negotiation levers tailored to different transformer types and buyer profiles.
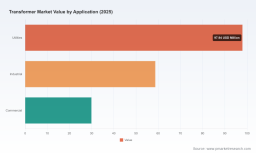
Note: while this preview summarizes the pragmatic modules, detailed regional and application-level splits, as well as vendor share tables, are proprietary to the report and available on the PW Consulting source page.
Competitive Landscape: Who Matters and Why
The transformer industry’s competitive topology blends global engineering heavyweights with regional specialists. Market concentration at the top remains modest relative to other energy equipment markets, with leading triads and quintets accounting for a pronounced but not dominant share of global supply. This creates opportunities for agile OEMs and local champions to carve differentiated positions.
- Global power-system integrators (Hitachi Energy, Siemens Energy, ABB, GE Vernova). These firms are the natural partners for large utilities and grid-scale projects. Their scale advantages include engineering depth, integrated service offers, and global project management capabilities. Recent M&A activity—most notably moves to bolster medium-voltage and specialty capabilities—underscores an active consolidation and capability-acquisition theme among these players.
- Electrical systems and distribution leaders (Eaton, Schneider Electric). Their strength lies in distribution and medium-voltage portfolios, where integration with switchgear, automation and digital monitoring creates higher-value system offers for commercial and industrial customers.
- Regional and niche specialists (Virginia Transformer, ERMCO, Foster Transformer). These companies compete on customization, short-cycle response for domestic markets, and deep service footprints. They are often advantaged when local policies or logistics make near-sourcing the pragmatic choice for utilities and industrial customers.
- M&A and contract activity to watch. Recent noteworthy moves include an acquisition enhancing medium-voltage specialization by a major global player in mid-2026, and contract awards to US-headquartered custom manufacturers that indicate continued demand for localized sourcing in regulated markets. These developments point to a dual strategy among large OEMs: expand specialized medium-voltage capabilities while maintaining strategic local partnerships to capture regulated utility work.
Key Risks and Monitoring Triggers for 2026
Strategic plans should be guarded by a short list of monitoring triggers. The report prioritizes these as early-warning indicators for operational and commercial teams:
- Lead-time metrics. Average manufacturing lead times for large power transformers and GSUs are critical supply-side indicators. Sustained elevations materially affect project timelines and cost profiles.
- Raw-material price bands. Copper and electrical steel remain the dominant cost levers. When price volatility pushes material cost beyond established thresholds, engineering trade-offs and procurement hedges need immediate activation.
- Regulatory changes and trade measures. Efficiency standard updates and tariff actions shift product economics and sourcing incentives; these can create abrupt local preference for certain core materials or compel design changes.
- Order-book composition. A meaningful directional increase in data-center or renewable-related orders signals different product and service requirements than traditional utility work (e.g., faster delivery windows, higher short-circuit ratings, or specialized tap-changer arrangements).
- Concentration and capacity shifts. Capacity additions, plant reconfigurations, or supply-chain bottlenecks among the top suppliers will reprice delivery risk and reshape negotiation leverage.
Executive Playbook — Immediate Actions for 2026
- Recalibrate procurement timelines: move from 12–18 month cycles to 24–36 month planning for large power units; adopt staged purchase agreements for medium-voltage requirements.
- Lock in material-cost governance: implement commodity hedges or index-linked contracts for copper and core steel; build alternative-specification pathways into RFPs.
- Prioritize supplier-development investments in regional partners to shorten delivery gaps and reduce tariff exposure.
- Use targeted M&A to acquire capabilities rather than volume: look for specialty medium-voltage manufacturers, digital monitoring providers, or regional service networks that accelerate market entry without heavy CAPEX.
- Invest in digital twins and condition-based service models to turn aftermarket activities into recurring revenue while lowering total lifecycle cost for buyers.
Conclusion — What You Gain from the Full Study
PW Consulting’s Transformer Market report equips executives with a decision-led map for 2026: it slices through headline growth to reveal the tactical moves that protect margins, secure delivery, and accelerate growth. The public preview above outlines the strategic contours; the full report contains proprietary segmentation, detailed vendor benchmarking, contract templates, and region-by-region scenario outcomes you can deploy immediately. For teams that must balance reliability, compliance, and profitability in a world of longer lead times and rising material costs, the study is designed to be the operating manual for the next procurement cycle.
To access the full set of actionable models, vendor scorecards, and scenario templates, consult the PW Consulting source page for the Transformer Market—where our granular analysis and downloadable tools are available to subscribers and clients.
For detailed analysis of this topic, please visit the official page: Transformer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com