

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chrome Metal Powder Market to Reach USD 324.66 Million by 2032 at 8.1% CAGR

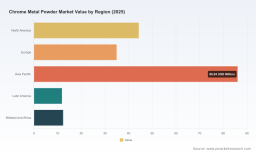
Chrome Metal Powder Market: Strategic Outlook for 2026 — PW Consulting Insight
Executive summary
As senior strategists at PW Consulting, we frame the Chrome Metal Powder market as a compact but strategically critical materials segment at the intersection of advanced manufacturing, surface engineering, and specialty alloys. Our latest study—anchored on a 2025 base year and a 2026–2032 forecast horizon—shows the market continuing a steady expansion with an 8.1% compound annual growth rate through the forecast window. That trajectory, combined with evolving raw-material dynamics and tightening environmental rules, makes 2026 a pivotal year for suppliers, buyers and investors to reset portfolios, revisit sourcing strategies, and accelerate technology and sustainability investments.
Chrome Metal Powder Market
Why this study matters for 2026 decision-makers
-
Timing: The industry is transitioning from a recovery-led phase to structurally higher demand drivers. Decisions taken in 2026 on capacity, contract tenor, and product qualification will set the competitive shape for the next decade.
Chrome Metal Powder Market -
Risk alignment: Input-cost volatility (notably chromite ore) and regulatory pressure on hexavalent chromium emissions mean conventional cost-plus models underprice execution risk. Procurement and finance teams must incorporate scenario-driven premiums for cleaner processing and longer qualification cycles.
Chrome Metal Powder Market -
Opportunity capture: Aerospace, electronics, and powder metallurgy applications continue to demand higher-purity, better-shaped powders. Firms that can combine quality, traceability, and low-emission processing will capture disproportionate margin upside.
Market trajectory at a glance
Using 2025 as our analytical baseline—with historical context from 2020–2025 and forward projection through 2032—our topline view demonstrates a clear growth runway. The market size in 2025 reflects cumulative recovery and incremental adoption across advanced end uses. Projected growth at an 8.1% CAGR to 2032 underscores a consistent multi-year expansion driven by new program ramp-ups, electrification of manufacturing processes, and substitution into higher-value powder metallurgy applications.
Two structural takeaways emerge: first, demand is broad-based across aerospace, electronics/welding, and alloys; second, market concentration sits in a band that allows established players to exert influence while leaving space for specialized or regional entrants. This balance creates strategic fault lines where investment in quality, sustainability, and supply-chain resilience pays off.
Dynamics shaping supply and demand
Understanding near-term supply/demand imbalances requires tracing three linked dynamics.
-
Raw material and pricing pressure — Chromite ore production improved in 2024, but ore-price volatility persists. Late-2025 developments saw notable upward pressure on chromite pricing, amplifying feedstock cost risk for powder producers. Firms with secure offtakes or integrated upstream positions are advantaged; those exposed to spot ore markets will face margin compression unless they convert to value-based pricing or hedge via longer-term contracts.
-
Regulatory tightening — Environmental rules targeting hexavalent chromium emissions are tightening in several major markets, especially in the EU and the UK. Compliance is not optional: manufacturers will need to invest in cleaner processing technologies and end-of-pipe controls. Expect capital expenditure reallocation toward emission abatement and process redesign, which will add to unit costs but also create differentiation for low-emission product grades.
-
End-market sophistication — Aerospace and electronics customers are increasing specification rigor around particle morphology, trace impurities, and supply-chain provenance. Certification timelines are extending and qualification costs are non-trivial; producers that accelerate certification and provide robust technical service capture longer, higher-value contracts.
Strategic implications across the value chain
-
Upstream (ore to feedstock): Vertical integration or long-term procurement is increasingly strategic. Securing predictable ore quality and pricing reduces working-capital volatility and limits exposure to sudden price spikes.
-
Processing (powder manufacture): Investment choices—whether to prioritize low-emission routes, high-purity capacity, or flexible multi-grade lines—determine addressable segments. Those prioritizing low-emission technologies can premium-price products to sustainability-focused OEMs.
-
Downstream (qualification and aftermarket): Offering engineering support, tailored batch traceability, and warranty-backed performance for critical applications creates stickiness. Conversely, commodity-grade suppliers will compete primarily on price and logistics.
What PW Consulting’s report delivers (practical, decision-ready contents)
The full study is engineered for executives and functional leaders who must translate market signals to concrete actions in 2026. Highlights include:
-
Proprietary market model: covers historical performance (2020–2025) and scenario-driven forecasts (2026–2032) incorporating sensitivity to ore-price shocks and regulatory cost pass-through dynamics.
-
Commercial playbook: go-to-market approaches depending on whether you are a scale producer, regional specialist, or technology-focused entrant. Each playbook aligns product strategy, certification roadmap, and channel partnerships to expected customer behavior in 2026.
-
Supply-chain stress tests: portfolio-level stress scenarios and mitigation checklists (supplier diversification, inventory policy, contract structure templates, and hedging alternatives).
-
Vendor scorecards and M&A checklist: an evidence-based assessment framework to screen targets, valuate strategic fit, and accelerate integration for bolt-on acquisitions.
-
Regulatory compliance roadmap: step-by-step capital planning for cleaner processing, emissions monitoring technologies, and expected timelines for compliance in major jurisdictions.
Note: the full report contains granular regional and application-level split tables, price curves, and vendor-level financial proxies. This preview intentionally omits those segmentation figures to preserve the complete analytical value available in the full dataset.
Competitive landscape — what to watch in 2026
The market is contested by a mix of global diversified metals houses, regional manufacturers, and specialist powder suppliers. Competitive advantage will be determined by three capabilities: secure feedstock, process excellence (including low-emission tech), and customer intimacy for critical applications.
-
American Elements (USA) — Strength: positioning in high-purity chromium powders serving research and premium industrial clients. Strategic priority for American Elements should be expanding traceability systems and accelerating product qualifications for electronics customers to protect margin against commoditization.
-
G K Min Met Alloys Co (India) — Strength: cost-competitive manufacturing and local market reach. The strategic pathway is to capture regional welding and alloy demand while selectively investing in higher-spec grades for export markets.
-
Harsco Corporation (USA) — Strength: scale and recent capacity investments targeted at aerospace/industrial segments. Harsco’s near-term play will be to monetize capacity through long-term OEM contracts and to signal reliability during qualification gates.
-
Eramet (France) — Strength: sustainability-focused product positioning. Eramet can leverage cleaner grades to win business where regulatory compliance and ESG requirements are decisive procurement criteria.
-
Tosoh Corporation (Japan) — Strength: strategic partnerships in electronics. Tosoh is well-placed to capitalize on high-purity, high-value electronic applications—continued collaboration with OEMs will be a differentiator.
-
Krebs & Riedel (Germany) — Strength: reputation for high-quality industrial powders. Their strategic bet should focus on premium industrial niches and certification-led contracts.
-
Molybdenum Corporation (USA) — Strength: expertise in powder metallurgy. Opportunity to cross-sell into refractory and specialty alloy customers, emphasizing formulation support and application engineering.
-
KGHM Polska Miedz (Poland) — Strength: portfolio breadth in non-ferrous metals. KGHM can play a role in securing upstream ore flows and integrating supply for European customers confronting emissions constraints.
-
Kronos Worldwide (USA) — Strength: industrial chemicals and processing capabilities. Their pathway is to leverage chemical know-how to offer tailored grades for chemical applications and surface treatments.
-
Jayesh Group (India) — Strength: specialist production for welding electrodes and powder metallurgy. The group is well-positioned to serve domestic markets and to ascend the value curve through process investments.
Collectively, these firms illustrate the market’s moderate concentration: a cluster of established players controls significant share, but differentiated technical capabilities, regulatory compliance, and customer-service models allow newer or smaller players to carve defensible niches.
How executives should use this research in 2026 planning
-
Procurement leaders: adopt a segmented sourcing strategy — lock long-term offtakes for critical feedstock, while maintaining tactical spot exposure for opportunistic buys. Factor in a premium for low-emission processing when qualifying suppliers.
-
Operations leaders: prioritize capital projects that reduce emissions and improve yields. Shorter-term projects that enhance particle-shape control and impurity removal often deliver the fastest payback through margin uplift.
-
Corporate development: use our vendor scorecards and M&A checklist to screen targets that provide either upstream resilience or downstream technical depth—both are defensible strategic plays given current industry dynamics.
-
R&D and product teams: align certification roadmaps to customer timelines; accelerate collaboration pilots with key OEMs to reduce time-to-qualification and claim early-adopter premium positions.
Next steps — where the full intelligence is
This briefing is designed as a strategic trailer: it synthesizes the most consequential market forces and highlights the tactical decisions that will matter in 2026. For practitioners who require the full evidentiary base—comprehensive regional and application-level splits, vendor financial proxies, price-curve scenarios, and the full set of operational playbooks—please consult the complete PW Consulting Chrome Metal Powder Market report. The full dataset is where you will find the actionable granularity needed to build contracts, CAPEX plans, and M&A models with confidence.
PW Consulting remains available to support bespoke scenario modeling, supplier negotiations, or M&A diligence tailored to your organization’s risk appetite and strategic objectives.
For detailed analysis of this topic, please visit the official page: Chrome Metal Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com