

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
IO-Link Market Set to Expand at 22.54% CAGR Through 2032

IO-Link Market 2026 Strategic Preview: Positioning Your Organization for a Decade of Accelerated Adoption
As organizations plan capital allocation and automation roadmaps for 2026 and beyond, IO‑Link moves from niche connectivity option to a foundational element of machine-level digitization. PW Consulting’s IO‑Link Market study (base year 2025) synthesizes five years of historical market tracking with an actionable, scenario-based forecast for 2026–2032. The headline: the IO‑Link ecosystem has demonstrated sustained double‑digit expansion and is set to scale rapidly as OEMs, end users and semiconductor suppliers convert proof‑of‑concepts into volume deployments.
IO-Link Market
Why this study matters to strategic decision‑makers in 2026
-
Timing and scale: IO‑Link has evolved from early interoperability efforts to certified safety and production‑grade deployments. Our study integrates this inflection—capturing a market that expanded materially between 2020 and 2025 and which we forecast to continue growing at a compound annual growth rate consistent with rapid industrial adoption.
IO-Link Market -
Investment prioritization: The report translates macro growth into prioritized investment themes—component ecosystems, master/hub architectures, software layers and services—helping procurement, R&D and M&A teams align budgets to where value will accrue.
IO-Link Market -
Risk mitigation: Emerging regulatory and certification milestones transform technological viability into procurement requirements. Understanding the interplay of standards, certification and interoperability events is now essential to avoid stranded investments.
Market trajectory in high level
IO‑Link’s addressable market has moved from a modest base in 2020 to a substantially larger commercial footprint by 2025, reflecting both increased device availability and accelerated integration into machine designs. Our base‑year analysis (2025) captures this acceleration and the resulting revenue pool, and our forecast extends through 2032 under multiple adoption scenarios. At an aggregate level, the market is forecast to grow at a strong pace over the forecast window, culminating in a multi‑fold expansion by 2032—an outcome driven by converging technical, economic and regulatory tailwinds.
What the report contains — practical, transaction‑ready intelligence
-
Market sizing & multi‑scenario forecasts (2026–2032) with sensitivity to adoption velocity, silicon availability and vertical uptake.
-
Adoption maps and maturational curves for OEMs and end‑users, including illustrative migration pathways from discrete wiring to IO‑Link centric topologies.
-
Operational playbooks: step‑by‑step integration checklists for machine builders, retrofit kits for brownfield upgrades, and commissioning templates that reduce deployment time and fault risk.
-
ROI models and TCO calculators: practical tools that quantify labor and wiring savings, operating efficiencies and payback periods under realistic shop‑floor scenarios.
-
Vendor benchmarking and procurement scorecards: comparative frameworks focused on product breadth, certification posture, ecosystem openness and long‑term support commitments.
-
Regulatory & certification matrix: how recent approvals and test‑center designations change compliance risk and procurement criteria.
-
Go‑to‑market playbook for channel partners and integrators, including partner‑selection criteria and bundled service offerings that capture downstream value.
Key dynamics shaping strategy
-
Cost economics at machine scale: Field studies and vendor disclosures indicate IO‑Link enables substantial labor and wiring savings per I/O point by replacing labor‑intensive harnessing and analogue PLC cards. For procurement teams this translates into lower first‑costs for sensors and reduced lifecycle maintenance.
-
Integration efficiencies: IO‑Link masters and compact hubs materially lower installation complexity. Eight‑port masters and similar modular approaches reduce cabling runs and junction hardware, enabling compact machine footprints and lower total installation cost.
-
Regulatory and safety momentum: The formal certification of IO‑Link Safety (notably TÜV SÜD’s certification of the relevant specification and the designation of test centers) marks a transition from development to production‑ready deployment. Safety‑certified IO‑Link devices remove a key barrier for adoption in regulated industries.
-
Interoperability acceleration: Community events and plugfests are increasing interoperability confidence among vendors and users. These activities reduce integration risk and accelerate vendor‑agnostic deployments.
Competitive landscape — how to interpret supplier signals
The vendor universe spans four archetypes: global automation OEMs, sensor and actuator specialists, semiconductor/transceiver suppliers, and system‑integration/platform providers. Market concentration is moderate—enough to highlight leaders but leave room for differentiated niche suppliers and regional champions. This balance creates both consolidation opportunities and continued competition on product features, integration tools and services.
-
Global automation OEMs (e.g., major multinational automation houses): These players bring scale, systems expertise and channel reach. Their IO‑Link strategies emphasize seamless integration into existing PLC/IPC portfolios, broad device compatibility and long‑term support—an attractive proposition for capital‑equipment buyers seeking single‑vendor reassurance.
-
Sensor and actuator specialists (several established European and Asian vendors): Their advantage is deep product-level differentiation—high‑performance sensors, robust device firmware and domain expertise in targeted verticals. They compete on sensor intelligence, robustness and application‑specific features.
-
Semiconductor & transceiver suppliers (notably established analog/logic vendors): These firms are crucial to scaling cost‑effective IO‑Link devices. Their roadmaps determine how quickly device costs fall and what device capabilities become feasible at scale.
-
System integrators, enablers and niche device makers: Specialized integrators and regional suppliers provide rapid deployment and customization—critical in complex brownfield upgrades or applications with unique form‑factor constraints.
In practice, winning strategies combine elements across these archetypes: platform incumbents securing end‑to‑end value chains, component specialists leveraging device performance to charge premium margins, and nimble suppliers capturing retrofit and localized service revenue.
Notable recent industry developments and their implications
-
Certification and test‑infrastructure: The formal certification of IO‑Link Safety and the designation of test centers materially de‑risk safety‑critical deployments. For OEMs and end users this reduces both technical and procurement risk, enabling IO‑Link to be specified in machine acceptance criteria.
-
Interoperability events and competence centers: Larger, recurring plugfests and newly established competence centers increase transparency and shorten validation cycles—valuable for procurement teams who must validate multi‑vendor stacks before production roll‑out.
-
Community governance: Evolving steering committees and governance structures mean that the IO‑Link ecosystem is maturing. This shift supports longer‑term roadmaps, clearer certification paths and better vendor coordination.
Strategic recommendations for 2026
-
Assess in tiers: Prioritize high‑impact, low‑complexity opportunities (e.g., sensor replacements and localized hubs) to realize early cost and reliability benefits while staging more complex retrofits.
-
Mandate certification: Require safety and interoperability certification in procurement agreements where applicable. This avoids integration delays and provides leverage in supplier negotiations.
-
Partner for integration: If you are an OEM, embed system integrators early in product design; if you are an end user, secure channel partnerships that include commissioning and lifecycle services.
-
Monitor silicon roadmaps: Anticipate price and capability shifts driven by semiconductor suppliers—these will determine which device capabilities become standard across tiers.
-
Use the ROI tools: Apply scenario models and TCO calculators to convert vendor claims into project‑level economics; prioritize rollouts with sub‑three‑year payback at realistic labor‑rate assumptions.
What you will learn from the full report
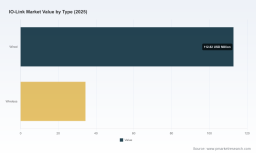
PW Consulting’s full IO‑Link Market study provides the granular segmentation, vendor scorecards, and downloadable decision tools necessary to convert strategy into procurement and product roadmaps. The published preview intentionally presents high‑level directionality and actionable frameworks while reserving the detailed regional, type and application splits for the full report and data package—this is the part that substantiates procurement specs, business cases and M&A target screens.
For executives and strategy teams preparing 2026 budgets, the actionable insight is clear: IO‑Link is no longer an optional connectivity experiment. It is a scalable approach to machine connectivity backed by regulatory approvals, strong economic levers and a maturing supplier ecosystem. Companies that move early to standardize on certified IO‑Link architectures, secure integration partners and align sourcing to silicon roadmaps will capture disproportionate operational and commercial advantage as deployments scale through the latter half of this decade.
To access the complete granular analysis, vendor rankings, and the scenario‑based dataset that underpins our forecasts, request the full PW Consulting IO‑Link Market study and the accompanying decision toolset.
For detailed analysis of this topic, please visit the official page: IO-Link Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com