

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Ultrafiltration Membrane Market to Reach $582M by 2032 at 6.5% CAGR - PW Consulting Insight

Ultrafiltration Membrane Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
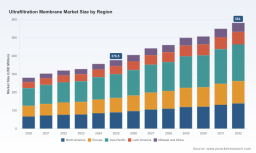
As organizations calibrate capital allocation and product strategy for 2026, ultrafiltration (UF) membranes present a distinct combination of steady growth, technology disruption, and regulatory complexity. Our market model (base year 2025) identifies a multi-year expansion trajectory at a compound annual growth rate of approximately 6.5%, taking total market size from its 2025 level toward materially higher values by 2032 (figures in USD million). This briefing outlines the strategic value the full Ultrafiltration Membrane Market study delivers to senior executives — providing a “trailer” of insights and directional implications while reserving the granular segmentation tables and proprietary vendor scores for the full report.
Ultrafiltration Membrane Market
Why this study matters for 2026 planning
- Investment prioritization: UF is moving from component purchase to integrated system thinking (membrane + process controls + service). Understanding medium-term demand and cost pressure is critical to prioritize R&D, CAPEX, and M&A.
- Product and materials strategy: Material-level dynamics and regulatory signals (notably around fluorinated polymers and PFAS) are reshaping platform choices and supply chains.
- Procurement and supplier risk: Concentration among established vendors and emergent regional capacity shifts create supplier-power swings — a precise sourcing playbook is a differentiator.
- Commercial positioning: Buyers increasingly value service agreements, life-cycle performance guarantees, and low-TCO outcomes over unit price alone.
Market trajectory and core growth drivers
The UF market is characterized by steady, defensible growth driven by multiple structural factors. Municipal water reuse and tightening effluent standards, the expansion of industrial reuse programs (food & beverage, pharmaceuticals, and process industries), and the uptick in decentralized water treatment projects collectively sustain demand. At the same time, improvements in membrane flux, anti-fouling chemistry, and system-level energy efficiency expand addressable use-cases.
Ultrafiltration Membrane Market
Our modeled forecast reflects these dynamics and assumes a steady-state macro environment; it also quantifies sensitivity to two strategic levers relevant for 2026 planning: accelerated municipal investments and a faster-than-expected materials transition triggered by regulation or raw-material supply constraints. Scenario outputs in the full study show how these levers can move 3–5 year horizon outcomes materially for manufacturers and system integrators.
Ultrafiltration Membrane Market
Competitive landscape — what the market structure implies
The UF market displays moderate concentration, with the top three players holding a majority share and the top five commanding an even larger portion. That concentration produces both stability and high barriers for late entrants at scale, but it also opens opportunities for specialists that can offer differentiated materials, local supply, or service models.
- Technology leaders and global integrators: Established firms like Toray, DuPont, and Koch leverage deep materials science or engineered module design to push performance and cleaning-interval metrics. Product launches across late 2025 and early 2026 (e.g., lower-biofouling modules and higher-flux hollow fibers) indicate continued R&D arms races focused on fouling reduction and operational uptime.
- Modular and process specialists: Suppliers such as MANN+HUMMEL, SUEZ/Veolia, and Pall remain attractive partners for large municipal and industrial projects because they pair membranes with systems expertise and global project execution capability.
- New capacity and regional challengers: Recent commercial-scale capacity additions—illustrated by the launch of new manufacturing facilities for innovative membrane types—are shifting cost and delivery dynamics in key markets. These entrants can be selective disruptors, particularly when their capabilities align with regionally concentrated demand.
- Life-science and specialty OEMs: Companies like Sartorius, 3M, and Asahi Kasei continue to hold strength in high-margin bioprocess and sterile filtration segments, where material properties (e.g., PFAS-free PES, certified feedstocks) and regulatory compliance command premiums.
Recent vendor moves and regulatory events to watch (selected)
- Toray launched a lower-biofouling UF module with one of the industry’s smallest nominal pore sizes (Apr 2026), signaling a focus on reuse and tertiary polishing where pathogen and micropollutant control is required.
- DuPont introduced a high-flux hollow-fiber product with improved fouling resistance and longer cleaning intervals (Dec 2025), aimed at reducing operational expenditures for municipal customers.
- Koch expanded its food-grade portfolio with modules optimized for dairy protein concentration and whey processing (Feb 2026), underlining the ongoing segmentation within industrial applications.
- Memsift Innovations commercially launched a new GOSEP membrane and brought significant annual production capacity online (Mar 2025), a reminder that regional capacity investments can rapidly influence supply-side economics.
- Sartorius expanded its bio-circular product offering to supply PFAS-free PES filters using ISCC Plus-certified feedstocks (Jan 2026), aligning with a broader sustainability and regulatory response trend.
- Regulatory noise: a proposed EU restriction on PVDF — a polymer widely used in high-performance UF membranes — introduces material switching risk; separately, tariff exposures on specific manufacturing footprints have influenced competitor sourcing decisions.
Strategic implications and executive actions for 2026
Executives should convert these structural signals into prioritized, time-bound actions across six domains:
- Materials and product roadmap: Begin targeted R&D and test programs for alternative base polymers and ceramic hybrids. Scenario plans should include accelerated qualification timelines if regulatory restrictions on leading polymers materialize.
- Supply chain resilience: Implement dual-sourcing, consider strategic off-take agreements with new-capacity producers, and map tariff/exposure risks by manufacturing node. Short-listing strategic suppliers with proven local capacity will reduce lead-time and price volatility risk.
- Commercial models: Move beyond unit sales toward outcome-based contracts (e.g., uptime guarantees, water recovery performance, lifecycle cost commitments) to differentiate, lock in customers, and stabilize revenues.
- M&A and partnerships: Look for tuck-in acquisitions to fill material gaps (ceramics, PES/PAN technology), secure capacity, or add service capabilities. Partnerships with regional manufacturers can accelerate market entry with lower capital intensity.
- Regulatory strategy: Establish a proactive regulatory monitoring and advocacy function. For manufacturers using polymers under scrutiny, build transition timelines and engage early with regulators and large customers to manage compliance costs.
- Operational pilots: Prioritize pilots that demonstrate reduced life-cycle cost, reduced chemical cleaning frequency, or PFAS-free operations — these are the fastest levers to convert technical advantage into commercial wins.
What the full PW Consulting study contains (operational deliverables)
The complete report is designed as a decision-support toolkit for boardrooms and BU leaders. Key deliverables include:
- Forward-looking market model with transparent assumptions and scenario variants through 2032 (base year 2025; values expressed in USD million).
- Segment and application demand assessments, including demand drivers, growth hotspots, and elasticities (note: detailed segment tables and regional splits are included only in the full report).
- Competitive benchmarking and vendor scorecards with capability matrices, go-to-market vectors, and strategic positioning diagnostics.
- Technology roadmap and IP landscape overview: membrane chemistries, module designs, anti-fouling strategies, and treatment-system integrations.
- Regulatory impact matrix and response playbooks covering material restrictions, PFAS trends, tariffs, and certification pathways.
- Commercial playbooks and negotiation templates for procurement, service contracting, and pilot deployment, plus sample financial models to evaluate life-cycle cost and TCO.
- Case studies and validated operational metrics from municipal, industrial, and food & beverage implementations to accelerate internal decision-making.
90 / 180 / 365-day roadmap for executives
- 0–90 days: Conduct a supplier exposure audit, identify critical materials at risk, and start 2–3 high-priority pilot projects (PFAS-free, higher-flux modules, or food-grade processes).
- 90–180 days: Finalize strategic supplier agreements, implement dual-sourcing where economically sensible, and initiate targeted R&D collaborations for alternative polymers or ceramic integration.
- 180–365 days: Execute approved product roadmap shifts, lock in long-term service offerings, and evaluate acquisition/partnership targets to internalize capability or capacity gaps discovered during pilots.
Conclusion — how PW Consulting helps
For 2026, ultrafiltration membranes are a pragmatic place to commit capital and strategy: growth is reliable, but the value is increasingly in materials choices, systems integration, and commercial innovation—not in simple product scale alone. Our Ultrafiltration Membrane Market study equips leaders to quantify these trade-offs, stress-test scenarios, and translate insights into executable programs. The preview here highlights the strategic contours; the full study contains the granular segmentation, vendor-level scoring, and executable templates you will need to act confidently in 2026.
Next steps
To access the full dataset, vendor scorecards, and model-able scenarios that power the recommendations summarized above, please consult the full Ultrafiltration Membrane Market report on our website or contact your PW Consulting client advisor. The comprehensive intelligence package is designed to be directly actionable for investment committees, product teams, and procurement functions preparing for 2026 execution.
For detailed analysis of this topic, please visit the official page: Ultrafiltration Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com