

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flocculant and Coagulant Market — USD 132M in 2025, 3.95% CAGR (2026–2032)

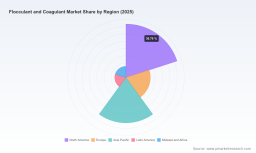
Flocculant and Coagulant Market — PW Consulting Strategic Preview for 2026 Decisions
Executive snapshot
As organizations finalize budgets and capital plans for 2026, the flocculant and coagulant market presents both steady growth and accelerating structural change. Our PW Consulting base-case model — built on audited historicals (2020–2025) and detailed scenario runs through 2032 — projects a mid-single-digit compounded expansion (CAGR ~3.95%) from a 2025 base. By modeling demand drivers, raw-material exposure, regulatory trajectories and supplier positioning, this preview shows where near-term choices (product mix, sourcing, capex and partnerships) will determine competitive positioning for the coming cycle.
Flocculant and Coagulant Market
Market posture and what it means for 2026 planning
-
Scale and trajectory: The market has shown resilient year-on-year growth through 2025 and, under our base-case assumptions, expands modestly through 2032. That trajectory supports selective growth investments rather than broad-based capacity builds — but only for firms that precisely align offerings to evolving regulatory and operational demand pockets.
Flocculant and Coagulant Market -
Concentration and competitive dynamics: Market concentration is moderate; our concentration metrics indicate that the top-three players account for a meaningful portion of supply while the top-five capture slightly more than half of the market value. This structure favors differentiated technology plays, targeted M&A to close capability gaps, and optimized route-to-market execution.
Flocculant and Coagulant Market -
Supply-cost sensitivity: Raw-material and energy cost volatility has become a structural factor. Late‑cycle price pressures and constrained feedstock availability have already influenced procurement strategy and pushed utilities and industrial consumers toward low-dose chemistries and process efficiency programs.
Drivers shaping demand through 2032
-
Regulatory cycles: New drinking-water standards and emerging substance limits are triggering capital and OPEX cycles in municipal treatment systems. Compliance-driven upgrades create recurring demand for both established inorganic coagulants and higher-value specialty chemistries that enable improved contaminant capture and reduced sludge footprints.
-
Sustainability and product innovation: Regulatory frameworks in mature markets increasingly favor biodegradable and lower-environmental-impact chemistries. This is accelerating early commercial adoption of bio‑based coagulants and flocculants, and will stratify supplier roadmaps into legacy commodity streams and higher-margin sustainable variants.
-
Operational economics: Utilities and industrial processors face rising operational inputs. That dynamic drives faster adoption of optimized dosing technologies and formulations that reduce solids generation and downstream disposal costs — an area where chemistry performance, dosing intelligence and service bundles converge to create differentiation.
-
Mining and heavy industry: Commodity cycles and mine remediation programs continue to underpin demand for specialized flocculants. Recent asset transfers and portfolio reshuffles in this segment make it a focal point for strategic buyers seeking scale and IP.
Competitive landscape — who matters and why
The competitive set comprises global chemicals majors, specialized polymer producers and integrated water-service providers. Several strategic archetypes are active:
-
Global portfolio leaders that combine inorganic and organic chemistries with strong channel presence and R&D capability (examples include long-established European and North American firms).
-
Specialist polymer manufacturers with scale in polyacrylamide lines, supplying both municipal and industrial segments and competing on product performance and cost-to-dose.
-
Service-centric integrators that bundle chemistry with equipment, digital dosing and long-term service contracts — increasingly attractive to mid-size utilities seeking capex-light upgrades.
Recent portfolio moves underline strategic intent across the industry: there have been divestitures of mining-focused flocculant assets to specialist players; launches of bio‑based formulations targeted at utility customers; and tactical acquisitions to shore up regional coagulant capacities. These developments compress time-to-market advantages for firms that combine chemistry innovation with local manufacturing and commercial reach.
What the PW report delivers — practical, transaction-ready insight
Our full study is built as an action toolkit for decision makers preparing 2026 plans. Highlights include:
-
Market sizing and forecast to 2032 with scenario sensitivity: base, upside and downside cases that stress-test demand under alternative regulatory and commodity-price paths.
-
Price and cost-to-dose modeling: a working model that links feedstock prices, energy inputs and formulation choices to delivered application costs for typical municipal and industrial use-cases.
-
Supplier scorecards and capability maps: comparative diagnostics across R&D, formulation breadth, regional manufacturing footprint, and service capabilities — designed to inform procurement and partnership selection.
-
M&A and partnership playbook: target screening, valuation heuristics and integration checklists for buyers seeking to accelerate entry into specialty flocculants, expand coagulant capacity, or acquire regional scale.
-
Operational play: dosing optimization, sludge-minimization strategies and retrofit investment cases including sample CapEx/Opex payback templates.
-
Regulatory and sustainability pathways: scenario planning for evolving contaminant standards and biodegradability requirements, and how different product strategies map to compliance and commercial upside.
-
Full methodology and data appendix: transparent assumptions, historical reconciliations and an interactive dataset to support bespoke modeling for corporate planning teams.
Strategic imperatives for executives charting 2026 moves
-
Prioritize product-tiering: Distinguish commoditized inorganic coagulants from higher-margin specialty and bio‑based chemistries. Redirect R&D and commercial resources to offerings that command premium contract terms or reduce client TCO.
-
Hedge feedstock exposure: Implement procurement hedges and dual-sourcing where feasible. Redesign formulations to reduce reliance on increasingly volatile inputs without compromising dose performance.
-
Invest in low-dose and digital dosing solutions: A combined chemistry + controls offering is rapidly becoming a preferred procurement model for large municipal and industrial buyers seeking both cost and compliance benefits.
-
Pursue targeted M&A: Look for tuck-ins that add specialty polymers, local coagulant capacity, or service-led channels — particularly where incumbents have divested non-core assets and created acquisition windows.
-
Build regulatory-forward roadmaps: Anticipate stricter contaminant limits and sustainability rules by accelerating trials and certifications for biodegradable chemistries in key markets.
-
Operationalize circularity and sludge reduction: Quantify client savings from lower-sludge regimes and translate them into bundled commercial propositions — this unlocks higher lifetime value and stickier contracts.
Recent industry moves that matter for 2026
-
Strategic asset reshuffles have reallocated mining and specialty flocculant portfolios among market leaders and specialist suppliers, creating immediate transactional opportunities and altering competitive sets.
-
Major suppliers are accelerating launches of bio‑based chemistries and expanding regional coagulant capacity in response to both regulatory demand and local market consolidation — validating our view that differentiated, regionally localized supply models will win in the coming cycle.
-
Raw‑material tightness and energy cost dynamics reported across late‑cycle 2024–2025 have materially influenced customer preferences for dosing efficiency and sludge‑reduction solutions, compressing adoption windows for higher-performance offerings.
How to use this preview in 2026 decision cycles
Budget holders, procurement heads and corporate development teams should use this preview to frame three immediate actions for 2026 planning:
-
Stress test product portfolios under our three forecast scenarios and identify the top two offerings to prioritize for R&D and commercial pilots.
-
Update procurement frameworks with a feedstock‑risk overlay and initiate contract renegotiations or alternative sourcing pilots where exposure is highest.
-
Align M&A screening criteria to the new competitive geometry — prioritize targets that provide formulation IP, regional manufacturing presence, or access to service-led revenue streams.
Next steps — where to find the granular intelligence
This preview is designed as a strategic orienting tool. The full PW Consulting Flocculant and Coagulant Market report contains the granular segmentation, regional and application detail, pro forma models and supplier benchmarking necessary to operationalize 2026 plans. For boards, corporate development teams and procurement leaders preparing investment decisions, that dataset is the working input for contract negotiations, CapEx prioritization and M&A diligence.
Contact PW Consulting or visit our report page to access the complete dataset, interactive models and executive briefings that translate this market outlook into transaction-ready actions.
For detailed analysis of this topic, please visit the official page: Flocculant and Coagulant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com