

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cold Forging Machines to Reach USD 344.8M by 2032 at 5.41% CAGR

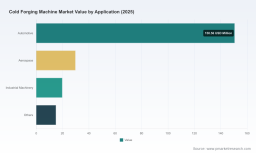
Cold Forging Machine Market — Strategic Outlook for 2026 Decision-Makers
As senior industry advisors at PW Consulting, we prepared this executive introduction to our Cold Forging Machine Market study to clarify why the coming 12–24 months are decisive for suppliers, OEMs, and strategic investors. This briefing highlights high-level market trajectories, the structural forces re-shaping supplier economics and technology adoption, and the practical decision frameworks our full study provides. Consistent with the “trailer” principle, we demonstrate methodological depth while intentionally withholding granular segment tables and proprietary line-item forecasts — these are available in the full report and interactive model.
Cold Forging Machine Market
Market trajectory: what the headline numbers say
The cold forging machine market has shown steady expansion through the recent cycle, rising from approximately USD 163 million in 2020 to about USD 215 million in 2025 (base year). Our modelling — incorporating historical trends (2020–2025) and supply/demand drivers — produces a central forecast that trends toward roughly USD 345 million by 2032 under the base-case path, with an average compound annual growth rate of 5.41% for the formal forecast window (2026–2032).
Cold Forging Machine Market
Two implications follow immediately: first, demand is large enough to support both specialized equipment makers and value-added systems integrators; second, growth is sustainable but not explosive, which amplifies the importance of margin capture through product differentiation, aftermarket services, and productivity gains.
Cold Forging Machine Market
What the report delivers — practical, decision-ready outputs
- Proprietary market model and scenario suite — base-case, upside (high automation), and downside (raw-material shock) variants with downloadable worksheets for sensitivity analysis.
- Investment and CapEx playbooks — payback templates for new lines versus retrofit options and an OEE-led primer to quantify productivity-led ROI.
- Vendor scorecards and technology benchmarking — capabilities mapping across multi-station headers, servo and hydraulic platforms, thread-rolling and secondary forming lines, and Industry 4.0 readiness.
- Commercial and pricing strategies — guidance on long-term supply agreements, spare-parts monetization, and aftermarket service bundles designed to improve lifetime customer value.
- M&A and alliance matrix — target archetypes, integration risk checklists, and transaction value drivers for consolidation or capability buys.
- Regulatory and sustainability assessment — compliance implications for oil-free and low-lubricant systems, energy performance baselines, and emissions considerations for industrial facilities.
These deliverables are built for operational teams and boardrooms: the models are configurable, and the vendor assessments include primary-interview validation and factory-level performance proxies.
Key market dynamics and 2026–2027 decision triggers
- Cost of metals and procurement volatility. Recent price trajectories for structural and coil steel have materially altered unit economics for parts producers. For example, structural steel moved higher in Q2 2026, and reported hot-rolled coil pricing held within a narrow band in mid-2026 — both trends that should factor into vendor and make-versus-buy assessments for capital equipment.
- Energy- and lubrication-driven regulation. A meaningful share of EU machine makers have already moved toward oil-free systems, and a large portion of new machines now incorporate energy-efficient drives and low-lubricant operation. These factors are reshaping specification sheets, maintenance contracts, and compliance timelines for customers purchasing equipment in 2026.
- Automation and digitalization as margin multipliers. Servo-driven infeed, modular Industry 4.0 connectivity, and predictive-maintenance enablement differentiate suppliers in a market where top-line growth alone is insufficient to maintain healthy returns.
- Skill and labour constraints. Cold forging increasingly requires highly skilled operators to manage precision servo systems and maintain throughput. Workforce strategy (training, remote diagnostics, operator-friendly HMIs) is a near-term determinant of realized capacity.
- Market fragmentation with pockets of specialization. Measured concentration metrics point to a market that remains fragmented; this opens opportunities for roll-ups and specialized service providers to capture aftermarket revenue and local support advantages.
Competitive landscape — capabilities to watch in 2026
Our supplier coverage blends legacy OEMs, specialized innovators, and regionally dominant machine builders. The key strategic positions to monitor include:
- Stamtec Inc. — U.S.-based with deep inventory availability for mechanical and servo models, positioning themselves as rapid-delivery solutions providers for press-line needs.
- National Machinery LLC — Expanded capabilities via acquisitions aimed at integrating wire drawing and cold/warm forming lines, strengthening their end-to-end value proposition.
- Hatebur Umformmaschinen AG — Swiss engineering focus on multi-station coldformers and precision automotive components; notable for introducing retrofit servo-infeed options to extend installed-base life.
- SACMA Limbiate S.p.A. — Specialized in headers and thread-rolling configurations for fasteners; strong heritage in high-speed screw and self-tapping part production.
- Kinefac Corporation — Developer of radial forming solutions, visible on the trade-show circuit and active in secondary cold forming niches for automotive and aerospace applications.
- Nedschroef Herentals NV — Focused on modular presses and Industry 4.0 connectivity — a profile attractive to OEMs seeking digital-ready lines.
- Macrodyne Technologies — Strength in hydraulic and servo presses for near-net-shape aerospace and automotive components where tolerances and material utilization are paramount.
- Selected Asian builders (multiple firms) — Regional providers offering competitive price-to-performance and increasing sophistication in intelligent forming equipment and complete production line offerings.
Recent company moves are indicative of broader strategic currents: trade-show commercialization of advanced secondary forming platforms, retrofit kits to extend installed-base competitiveness, and M&A to add upstream or complementary forming capabilities. These are the tactical levers that we expect to drive market reshaping in 2026–2027.
Strategic implications for buyers, sellers, and investors
- Manufacturers and Tier-1 suppliers: prioritize retrofit options and modular automation that lower time-to-value and reduce the need for full-line replacement amid raw-material cost uncertainty.
- OEMs and integrators: invest in predictive maintenance and remote-service capabilities to convert tighter procurement cycles into recurring aftermarket revenue.
- Private equity and strategic acquirers: target niche specialists that provide immediately accretive aftermarket service platforms, Industry 4.0 enablers, or complementary forming processes.
- Procurement and operations teams: build price-hedging and tiered sourcing strategies for steel inputs alongside SLAs that shift maintenance responsibility toward equipment suppliers where feasible.
Practical decision framework — five steps for 2026
- Run a scenario-based CapEx model (available in the full study) to stress-test retrofit versus new-purchase outcomes across three raw-material price cases.
- Shortlist vendors against four pragmatic criteria: precision tolerance capability, servo/energy efficiency, spare-part lead times, and digital-service maturity.
- Quantify aftermarket opportunity: convert improvements in OEE and uptime into a 3–5 year revenue schedule to justify financing options.
- Structure supplier agreements to include retrofit pathways and capacity-flex clauses to reduce total lifecycle cost and technological obsolescence risk.
- Invest in workforce enablement and remote diagnostics to limit the skill bottleneck and to maximize throughput gains from higher-automation equipment.
Why PW Consulting’s study is the right tool for 2026 decisions
Our Cold Forging Machine Market study combines rigorous, reproducible modelling with field-verified supplier intelligence and downloadable decision tools. Methodological strengths include primary interviews across OEMs and end-users, engineering-validated capacity and OEE assumptions, and a transparent scenario framework that quantifies downside and upside risk to capital plans. We deliberately avoid oversimplified “one-size-fits-all” prescriptions; instead, the research equips you with configurable templates and vendor scorecards tuned for your strategic priorities.
To preserve the strategic value of the analysis for subscribing clients, we have kept detailed segmentation tables, per-region and per-application allocations, and the full financial model in the full research package. These components turn the high-level guidance above into executable decision items for procurement, operations, and corporate development teams.
For full access to the downloadable models, comprehensive vendor scorecards, and deep-dive segmentation, consult the complete PW Consulting Cold Forging Machine Market report or contact our industry team to request a tailored briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Cold Forging Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com