

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Green Chelates Market Poised at USD 2,850M in 2025

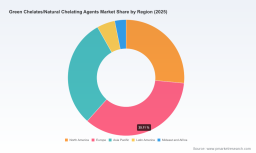
Green Chelates & Natural Chelating Agents: Strategic Outlook for 2026 — A PW Consulting Industry Brief
Executive Snapshot
As companies set strategy for 2026, the green chelates and natural chelating agents market sits at an inflection point where environmental regulation, formulation performance, and raw-material economics intersect. PW Consulting’s latest study (base year 2025; historical series 2020–2025; forecast 2026–2032) documents a resilient industry trajectory driven by substitution of legacy phosphates/EDTA-type chemistries, investments in bio-based feedstocks, and faster commercialisation of readily biodegradable grades. The market expands at a compound annual growth rate (CAGR) of 6.23% over the forecast window, with aggregate market value moving from the mid‑2020s baseline into materially larger scale by the early 2030s. While the landscape remains fragmented (CR3 ~24%, CR5 ~35%), the pace of capacity investments and M&A activity is accelerating competitive consolidation and capability differentiation.
Green Chelates/Natural Chelating Agents Market
Why this research matters for 2026 decisions
-
Timing and prioritisation: Executives need a validated time‑map for product launches, capacity commissioning, and commercial pilots. Our forecast horizon (2026–2032) aligns with short‑ to medium‑term capital planning cycles and regulatory roadmaps that will determine access to major downstream markets.
Green Chelates/Natural Chelating Agents Market -
Risk‑reward tradeoffs: The sector combines technology risk (scale-up, feedstock substitution) and market opportunity (reformulation demand across home care, industrial cleaning, water treatment, agriculture and personal care). The report converts these into prioritised investment scenarios and break‑even logic for 2026–2028 execution windows.
Green Chelates/Natural Chelating Agents Market -
Commercial playbook: Practical channel and pricing guidance, tender participation strategies for water utilities and institutional customers, and SKU rationalisation templates allow commercial teams to translate sustainability claims into margin‑accretive contracts.
-
Regulatory and compliance foresight: With several new biodegradability approvals and certification milestones in 2024–2025, companies need a compliance roadmap to avoid market access delays. The research provides a regulatory decision tree tailored to EU, North American and key APAC regimes.
Report contents — what’s in the toolkit
The published study is purpose‑built to support strategy and execution. Highlights include:
-
Market sizing and demand model (2020–2032) with base‑year calibration and scenario variants (conservative, central, accelerated) reflecting policy-tightening and rapid adoption outcomes.
-
Segment‑level demand drivers and elasticity analysis for principal end‑use clusters (cleaning & detergents; personal care; water treatment; agriculture; food & beverage; industrial processes), with go‑to‑market implications for each.
-
Supply chain diagnostics covering feedstock availability, conversion yields, and cost curves — including the strategic role of amino‑acid feedstocks (e.g., alanine) and its capacity footprint at major production sites.
-
Technology & product benchmarking: biodegradability claims, renewable‑carbon metrics, chelation strength across pH ranges, and laboratory‑to‑plant scale comparators to rate technology readiness.
-
Commercial diligence assets: supplier scorecards, tender playbooks, distributor economics and margin models for contract negotiation and pricing strategy.
-
M&A and corporate development playbook: target screening criteria, valuation levers, integration risk checklists and post‑merger synergies quantification.
-
Regulatory tracker and compliance matrix summarising OECD biodegradability claims, regional registration timelines, and certification pathways that affect market access.
-
Appendices: interview excerpts with procurement leads, formulators, and regulators; a full list of primary and secondary sources used to build the model.
Market dynamics shaping near‑term strategy
Three concurrent forces are reshaping the market and must be central to boardroom conversations in 2026:
-
Regulatory acceleration and sustainability certification. Recent approvals and product certifications in 2024–2025 have materially de‑risked the path to substitution for many downstream formulators. Readily biodegradable claims and renewable‑carbon metrics are now enforceable commercial differentiators; companies that cannot demonstrate credible, certificated sustainability credentials will face procurement exclusion in prioritized customer segments.
-
Feedstock and scale economics. The emergence of amino‑acid based routes (notably alanine‑derived MGDA pathways) and bio‑based GLDA platforms has created multiple viable conversion chemistries. Industry capacity additions announced in late 2024 and 2025 signal a shift from boutique to industrial scale — but feedstock availability and cost volatility remain critical gating factors for margin projection.
-
Consolidation and vertical coordination. The market concentration metrics show a fragmented competitive set; however, recent M&A, certification achievements and capacity expansions indicate an industry consolidating around players that can combine IP, feedstock integration and global distribution. Strategic acquisitions and JV structures are emerging as the fastest route to global market coverage.
Competitive landscape — capabilities and strategic postures
Our competitive map identifies several archetypes among active firms and the way they are executing in 2025–2026:
-
Technology leaders with portfolio breadth: Companies like Nouryon and BASF are leveraging scale and R&D intensity to deliver product families that pair performance with certified sustainability attributes (e.g., high renewable‑carbon content and OECD biodegradability claims). Their moves — from asset certification to targeted acquisitions and new grade launches — are designed to lock in formulators seeking low‑risk substitutes.
-
Specialists focused on selected end‑markets: Firms such as Kemira and Lanxess concentrate on application‑specific solutions (pulp & paper deinking, water treatment or detergent substrates) and compete on regulatory fit, ease‑of‑use and supply reliability rather than broad SKU breadth.
-
Fast‑followers and niche innovators: Jungbunzlauer, Jarchem and a set of regional producers (including Adob, Van Iperen and Actylis) are introducing cost‑effective alternatives targeted at regional formulators and agricultural micronutrient stabilisation, often competing on local service and tailored technical support.
-
Platform integrators and collaboration players: Dow and others are pursuing partnerships and co‑development arrangements to accelerate scale‑up of bio‑based chelating agents for water and industrial applications, emphasising access to established sales channels and large‑scale processing expertise.
Recent industry signals (select events)
-
Certification and product launches in 2024–2025 have validated several green chelate platforms, with leading companies achieving sustainability accreditation and launching 100% bio‑based carbon grades.
-
Strategic M&A and capacity expansion announcements in 2025 indicate an industry preparing for higher volume demand and tighter supply chains; several leading firms strengthened portfolios through acquisition or by expanding production footprints.
-
Regulatory approvals and product classification updates during 2024–2025 have reduced compliance risk for certain biodegradable agents, accelerating adoption in regulated procurement environments.
Actionable recommendations for corporate leaders planning in 2026
-
Prioritise certification before scale. Fast followers can be outcompeted if they cannot document biodegradability and renewable‑carbon metrics; allocate 2026 CAPEX and OPEX to certification pathways (OECD‑type testing, ISCC or equivalent) as a precondition for major customer contracts.
-
Secure feedstock flexibility. Negotiate offtake or backward integration options for amino‑acid feedstocks and bio‑intermediates. Scenario models in the report quantify margin sensitivity to feedstock cost swings and will help procurement prioritise hedging vs spot strategies.
-
Adopt a modular go‑to‑market approach. Use pilot supply agreements, tiered pricing for industrial vs consumer applications, and targeted distributor partnerships in 2026 to build scale without overcommitting fixed capacity.
-
Be selective with M&A: target acquisitions that deliver either feedstock security, regulatory dossiers, or route‑to‑market capabilities. The report’s target screening matrix helps rank opportunities by strategic fit and integration risk.
-
Invest in demonstrable performance data. Beyond biodegradability, purchasers increasingly demand independent performance comparators — complexation strength across pH, chelate stability, and effects on downstream processing. Publish comparable test reports and third‑party validations early.
What the brief does not include — and where to go next
This overview is intentionally curated to provide strategic direction and to flag tactical considerations for 2026. To preserve actionable differentiation and client value, detailed segment tables (regional splits, application share matrices, and granular price curves) have been omitted from this summary. PW Consulting’s full market study contains the complete numerical model, downloadable datasets, supplier scorecards, and transaction playbooks that enable immediate implementation.
Next steps
For executive teams preparing 2026 operating plans, the decision levers are clear: certify product attributes, secure feedstock options, and select a go‑to‑market model that balances scale and flexibility. PW Consulting can provide tailored workshops to translate the report’s scenarios into board‑level capital allocation decisions, supplier negotiations, and M&A target lists. Contact our industry practice to access the full dataset and custom advisory packages that convert this market view into executable 2026 strategies.
For detailed analysis of this topic, please visit the official page: Green Chelates/Natural Chelating Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com