

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 3C Coatings Market Poised for 4.6% CAGR Through 2032

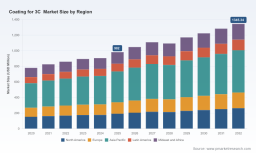
Coatings for 3C Market: Strategic Imperatives for 2026 — PW Consulting Briefing
Executive snapshot
As the 3C (computer, communication and consumer electronics) coatings market enters 2026, PW Consulting’s latest market study positions the segment as a steadily expanding specialty market. Our base-year assessment (2025) values the global market at approximately USD 982 million, with our forecast modelling projecting compound annual growth of 4.6% through the 2026–2032 horizon, driving the market toward the mid‑teens hundreds of millions by 2032 under the central case. For executives making strategic choices in 2026, that trajectory translates into predictable, but differentiated, opportunities—where technology, regulatory alignment and supply‑chain design will determine winners and laggards.
Coating for 3C Market
Why this report matters for 2026 decision-making
- Translating modest growth into differentiated returns. A mid-single-digit CAGR does not imply commodity dynamics. In 3C coatings, product mix, formulation innovation and OEM certification convert volume growth into margin expansion. Our study quantifies where premiumization and cost pressures coexist and provides decision frameworks to capture asymmetric returns.
- Regulatory and sustainability inflection points. Accelerating regulatory pressure (notably low‑VOC mandates from major markets and the growing importance of ISO 14001 and eco‑label credentials) is already reshaping formulation roadmaps. The report maps regulatory risk to product roadmaps and provides compliance-to-profit conversion playbooks—critical for 2026 product launches and supplier qualification cycles.
- Operational resilience in the face of supply shocks. Raw material constraints—most notably powder resin shortages—and rising labor costs across Asian manufacturing hubs are elevating supply risk. Our supplier risk matrix and scenario models let procurement and operations leaders quantify the cost and time trade-offs of nearshoring, strategic inventory, and multi‑sourcing strategies.
- Technology and partnership playbooks. Recent industry moves—such as the January 2026 ink/technology partnership between Xaar and Sokan New Materials and new product introductions like NATOCO’s SELF‑HEALING CLEAR™—demonstrate that co‑development and embedded functionality are accelerating product differentiation. The study provides a roadmap for structuring such partnerships and extracting IP, volume and margin advantages.
What’s inside the PW Consulting study (practical, actionable elements)
- Consolidated market sizing and a seven‑year forecast anchored to our 2025 base year and a 4.6% CAGR, with scenario bands reflecting supply disruptions, faster regulatory ramp, and accelerated premiumization.
- Demand‑driver diagnostics that tie end‑market trends (consumer device form factors, ruggedization needs, aesthetic cycles) to formulation and process requirements.
- Go‑to‑market playbooks for suppliers at three strategic positions: specialized formulators, integrated chemical majors, and contract coaters—each with tailored commercial and operational KPIs.
- Regulatory and sustainability compliance scorecards mapping certification timelines, CAPEX implications, and margin impacts for low‑VOC and water‑based conversions.
- Supply‑chain stress tests and supplier scorecards: powder resin exposure, single‑sourcing risk, logistic pinch points, and labor‑cost sensitivity modelling for Asian manufacturing hubs.
- Investment and M&A frameworks: target screening criteria, valuation benchmarking, and integration checklists to prioritize bolt‑on acquisitions and technology partnerships.
- Commercial tools: price elasticity models, channel and OEM negotiation templates, and a product launch calendar synchronized with certification lead times.
Competitive landscape — who’s shaping the market and why it matters
The 3C coatings space sits between specialty chemistry and high‑volume electronics manufacturing. Competitive dynamics are defined by a mix of global coating majors, regional specialists, and niche innovators. Our report provides a qualitative and strategic assessment of leading players and what their moves mean for market access, technology diffusion and pricing.
Coating for 3C Market
- AkzoNobel N.V. (Amsterdam, Netherlands — https://www.akzonobel.com/en) : Focused on Resicoat and low‑solvent/water‑borne technologies, AkzoNobel’s strength lies in scaling eco‑friendly formulations for OEM shell and component applications. For partners and competitors, this signals the need to accelerate product validation cycles for water‑borne systems and to compete on certification speed and technical services.
- PPG Industries, Inc. (Pittsburgh, United States — https://www.ppg.com/en-US) : With a heritage in surface treatments, PPG’s play is integrated systems—coatings plus pretreatment—favoring customers that demand single‑vendor accountability across appearance and durability. Strategic implication: co‑development and system warranties become differentiators.
- Sokan New Materials Group Co., Ltd. (China — https://en.sokan.com.cn/) : A regional innovator in functional coatings, inks and adhesives, Sokan’s recent January 2026 partnership with Xaar underscores the convergence of printing technologies and coatings for functional aesthetics and sensor integration on 3C surfaces.
- Beckers Group (Berlin, Germany — https://www.beckers-group.com/) : Beckers’ recent sustainability reporting and its coil/industrial coating capabilities point to a volume‑grade, eco‑certified strategy—important for customers balancing cost and environmental claims.
- Musashi Paint Co., Ltd. (Japan — https://en.musashipaint.com/) : With expertise spanning consumer electronics and automotive electronics, Musashi demonstrates cross‑industry technology transfer—valuable for advanced coatings that require higher durability and thermal stability.
- Cashew Company Limited (China — https://www.cashewamericas.com/) : Focused on decorative and protective coatings, Cashew highlights the ongoing importance of finish aesthetics combined with cost efficiency for mass-market 3C products.
- NATOCO Co., Ltd. (Japan — https://www.natoco.co.jp/en/) : Product innovation such as the SELF‑HEALING CLEAR™ in‑mold coating illustrates how added functionalities (self‑repair, scratch resistance) can command price premia and require targeted OEM certification strategies.
- Jiangsu Hongtai Polymer Materials Co., Ltd. (China — https://www.hongtai.com/) : A supplier of high‑end coatings and functional materials; a likely acquisition target for buyers seeking fast access to premium formulations and local OEM relationships.
- Wanhui Paint Co., Ltd. (China — http://www.wanhuipaint.com/) : Specialist supplier of exterior paints for 3C and appliances—highlighting the persistent need for suppliers who can balance cost, color matching and durability at scale.
- Guangdong Haohui New Materials Co., Ltd. (China — https://www.haohuimaterials.com/) : Emphasizes eco‑friendly application solutions; their trajectory is illustrative of the broader market pivot toward compliance‑ready products.
Recent industry signals and what to read into them
- Partnerships between ink/print and coating specialists (e.g., Xaar & Sokan) are accelerating functional printing on 3C surfaces—embedding sensors, haptics and advanced aesthetics. Manufacturers should evaluate co‑development JVs and licensing rather than build everything in‑house.
- New product announcements (such as NATOCO’s self‑healing surface) suggest product differentiation will be increasingly technology‑driven rather than price‑driven. IP strategy, testing pipelines, and warranty frameworks will become competitive battlegrounds.
- Large suppliers publishing sustainability reports (e.g., Beckers) indicate that eco‑claims are shifting from marketing to procurement requirements. Expect customers to require ECO declaration packages as part of supplier pre‑qualification in 2026.
- Regulatory momentum and market share shifts toward water‑based systems are measurable and irreversible in major markets; conversion timelines and certification queues will be strategic constraints for product launches this year.
Five high‑impact strategic moves for 2026
- Prioritize a rapid, certified water‑based portfolio conversion. Customers and regulators are shortening acceptance windows. Build a two‑track roadmap: retrofit high‑volume lines for water‑borne conversion and reserve a pilot line for advanced functionalities (self‑healing, printed electronics).
- Secure raw material continuity and alternative supply routes. Address powder resin shortfalls with contract manufacturing, strategic inventory, and a secondary supplier network. Model margin and lead‑time impacts under three disruption scenarios—our report includes ready‑to‑use models.
- Pursue targeted co‑development with printing/ink technology providers. Functional printing partnerships can unlock higher unit economics and sticky OEM relationships; structure agreements to preserve IP upside while sharing commercialization risk.
- Embed sustainability credentials into the commercial pitch. Make ISO 14001 and eco‑label timelines a part of the sales CPQ (configure‑price‑quote) process to shorten OEM qualification cycles and justify premium pricing.
- Use M&A selectively to buy time and capability. For firms facing long internal development cycles, bolt‑on acquisitions of specialist formulators or regional coating houses can accelerate market access and certification readiness. The study provides a screening checklist tuned to 3C dynamics.
How to use this briefing and next steps
This briefing is designed as a strategic trailer: it surfaces the critical levers and directional numbers that should shape boardroom deliberation in 2026, while preserving the granular segmentation, supplier scores and proprietary models that power executable plans. The full PW Consulting report contains detailed subsegment forecasts, supplier scorecards, raw material exposure matrices, OEM qualification timelines and downloadable financial models—tools that operational teams will need to convert strategy into transactions and capex plans.
Coating for 3C Market
For commercial leaders and C-suite teams preparing budgets, sourcing or M&A activity this year, the actionable elements of our study bridge the gap between market trend and executable project. If your 2026 plan requires clarity on where to allocate R&D dollars, which supplier relationships to harden, or which capabilities to buy versus build, PW Consulting’s full market study offers the scenario‑based answers and implementation templates that shorten decision cycles and de‑risk execution.
Getting the full intelligence
This public briefing intentionally omits proprietary subsegment detail and the granular data tables that underpin our forecasting engine. Access the full Coatings for 3C Market report to obtain the complete dataset, supplier rankings, granular regional and application segmentation, and the downloadable operational models that your teams will need to act in 2026.
For detailed analysis of this topic, please visit the official page: Coating for 3C Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com