

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Indoor LBS Market to Expand at 23.8% CAGR Through 2032

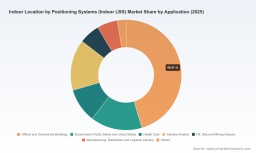
Indoor Location by Positioning Systems (Indoor LBS) — Strategic Preview for 2026
Executive preview
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our latest Indoor Location by Positioning Systems (Indoor LBS) market research. This briefing distils the study’s most consequential implications for enterprise decision-making in 2026 while intentionally holding back the full granular segmentation and proprietary datasets reserved for the full report. Our objective here is to give senior leaders the confident, evidence-backed insight needed to act in 2026, and to show why procuring the full deliverable is a necessary next step.
Indoor Location by Positioning Systems (Indoor LBS) Market
At a macro level, the Indoor LBS market is transitioning from early adopter, siloed deployments to broad-based enterprise adoption. Our base year for analysis is 2025 (USD Million), when the market reached approximately 709.0. With a robust compound annual growth rate (CAGR) of 23.8% across the 2026–2032 forecast window, the market is projected to surpass 900 in 2026 and to accelerate materially through the latter half of the decade as precision positioning, standards maturation, and new spectrum/5G initiatives converge. By 2032 our topline projection reaches into the multiple billions (USD Million basis) — a scale that makes indoor location a strategic infrastructure decision, not a niche add-on.
Indoor Location by Positioning Systems (Indoor LBS) Market
Why this matters for 2026 strategy
- Technology inflection: 2025–26 marks a transition from proof-of-concept pilots to operational rollouts for several enterprise classes (healthcare, manufacturing, logistics, large commercial campuses). Enterprises that wait to define standards and procurement strategies risk higher retrofit costs and vendor lock-in.
- Standards & spectrum are game changers: Industry standards (notably FiRa’s evolving Core specifications) and regulatory moves expanding terrestrial spectrum for metropolitan beacon systems materially change the competitive calculus for both vendors and buyers.
- Integration with network and cloud: Positioning is rapidly becoming a native capability of core enterprise infrastructure (Wi‑Fi, 5G, campus networks, cloud location platforms). Decisions taken in 2026 about network architecture, cloud tenancy, and data governance will influence total cost of ownership and vendor selection for a decade.
- Fragmentation persists but is consolidating: Market concentration remains moderate; the three- and five-firm concentration metrics indicate room for competition and innovation, but also the rise of platform players that can bundle location with broader enterprise services.
Market dynamics shaping vendor and buyer decisions
Several converging technical and regulatory developments are accelerating commercial deployments and altering supplier strategies:
Indoor Location by Positioning Systems (Indoor LBS) Market
- Standards evolution: The FiRa Consortium’s progressive specification releases in 2025 and 2025–26 (Core 3.0 and Core 4.0) introduce hybrid scheduling, improved coexistence in complex RF environments, and expanded certification paths. This improves multi-vendor interoperability and reduces integration risk for enterprise adopters.
- Spectrum & metropolitan beacons: Regulatory approvals and license assignments in lower 900 MHz have enabled expansion of terrestrial beacon architectures. The recent approvals for metropolitan beacon spectrum materially improve indoor/outdoor continuity and vertical positioning in dense urban environments.
- 5G Advanced and dedicated indoor radio: Commercial availability of 5G Advanced location services in early 2026, including indoor radio dot integrations, signals that mobile network infrastructure providers are moving from research to commercial deployments for sub-meter indoor positioning — a potential disruptor for legacy Wi‑Fi and BLE-based approaches.
- Device ecosystem and chipsets: Broad adoption of UWB-capable chipsets and chipset-level FiRa compliance is maturing, enabling device-based high-precision options that reduce per-asset infrastructure costs.
Practical strategic imperatives for enterprises in 2026
For decision-makers, the following imperatives translate market dynamics into executable actions:
- Define location as infrastructure: Treat indoor positioning like power, identity, or networking — include it in architecture roadmaps, budget cycles, and security/compliance frameworks.
- Prioritise interoperability and standards: Insist on FiRa-compliant and standardized interfaces in RFPs to avoid single-vendor lock-in and to maintain a path for multi-technology coexistence.
- Adopt a layered deployment strategy: Combine device-based precision (UWB/UWB-hybrid) where needed with network-based and cloud-native services for scale and analytics. This hybrid approach reconciles precision requirements and economics.
- Plan pilots to validate real-world constraints: Model RF propagation, privacy limits, and operational workflows with controlled pilots in representative facilities prior to enterprise-wide rollouts.
- Factor spectrum and network partnerships into procurement: New metropolitan beacon and 5G capabilities create partnership opportunities (and requirements) with public network operators and spectrum holders.
- Embed data governance: Location data is highly sensitive. Establish consent, retention, anonymization and security controls tied to broader data governance policies before scaling deployments.
What PW Consulting’s full report delivers (practical content)
This preview highlights the report’s practical, decision-grade components designed for enterprise adoption teams, investors, and technology partners. The full deliverable contains:
- Topline market model with historicals (2020–2025) and scenarios across 2026–2032 (base, upside, downside).
- Vendor scorecards and capabilities matrices, including technology stacks, go‑to‑market motions, and strategic fit by enterprise use case.
- Actionable TCO and ROI templates, with deployment cost drivers and sensitivity analyses for competing positioning architectures.
- Implementation playbooks and checklists: procurement templates, pilot design templates, integration testing plans, and security/privacy checklists.
- Use-case playbooks for key verticals (healthcare operations, manufacturing floor optimization, logistics & distribution, retail/hospitality) with recommended technology mixes and phased roadmaps.
- Primary research insights: interview excerpts with CTOs, facilities leaders, and leading vendors, plus on-site RF measurement case studies.
- Regulatory and standards tracker: timelines and impact analysis for FiRa releases, spectrum assignments, and 5G location rollouts.
To honour the “trailer” principle, we present these elements at a high level here; the full report provides the granular segmentation tables, year-by-year forecasts, and downloadable datasets that underpin each recommendation.
Competitive landscape: strategic implications for vendor selection
The market is being shaped by a diverse set of suppliers — from infrastructure incumbents and chipset makers to pure-play RTLS specialists and platform firms. Key strategic positions to watch:
- Zebra Technologies – Strength: mature RTLS solutions combining RFID and BLE with deep vertical expertise in healthcare and manufacturing. Strategic implication: ideal for asset-tracking-led transformations where operational integration with barcode and RFID ecosystems is critical.
- HID Global – Strength: UWB-enabled RTLS following targeted acquisitions, positioning for industrial and smart factory use cases requiring high reliability. Strategic implication: attractive where deterministic, real‑time RTLS performance is a must and where industrial lifecycle support matters.
- Cisco Systems – Strength: integration of enterprise Wi‑Fi and positioning as part of network infrastructure. Strategic implication: favours organisations seeking to fold positioning into existing network refresh cycles and unified management models.
- Ericsson – Strength: 5G Advanced indoor positioning delivered through dedicated RAN and Radio Dot systems. Strategic implication: suitable for large campus or carrier-integrated deployments where mobile operator collaboration is viable.
- NextNav – Strength: terrestrial Metropolitan Beacon System using lower 900 MHz spectrum. Strategic implication: offers unique building-agnostic vertical positioning and indoor/outdoor continuity in urban settings; spectrum ownership is a differentiator.
- HERE Technologies, Google, Apple – Strength: mapping platforms and device ecosystems. Strategic implication: these players dominate location data and user experience layers; partnerships or platform lock-in considerations are strategic for consumer-facing or navigation-led services.
- Qualcomm Technologies – Strength: chipset leadership and FiRa-aligned UWB platforms. Strategic implication: device OEMs and integrators will gravitate to chipset roadmaps, making chipset partnerships central to device-driven strategies.
- CenTrak – Strength: healthcare-focused BLE/Wi‑Fi solutions with clinical workflows in mind. Strategic implication: best-in-class for healthcare providers where clinical compliance and asset/staff tracking are top priorities.
Market concentration metrics indicate a diverse competitive set: leading incumbents command meaningful shares but there is still space for specialized and horizontal platform entrants. This competitive posture means enterprises can and should use competitive procurement to negotiate terms, SLAs, and integration commitments.
Three strategic scenarios for 2026–2028 and recommended moves
- Platform consolidation: Major network and mapping platform vendors integrate positioning vertically. Recommended move: lock in strategic integration pilots with preferred platform and secure portability clauses.
- Standards-driven interoperability: FiRa and other standards enable multi-vendor coexistence, reducing integration friction. Recommended move: mandate FiRa/standards compliance in procurement and prioritize vendors with certification roadmaps.
- Edge-cloud hybrid expansion: Real-time RTLS tied to edge compute for latency-sensitive workflows while cloud analytics scale cross‑facility learning. Recommended move: design an edge/cloud architecture and budget phased investments to distribute risk.
Immediate next steps for 2026 planning
- Run a rapid pilot (90–120 days) focused on a single high-value use case to stress-test RF, workflows, and privacy controls.
- Create a cross-functional steering committee including IT, facilities, security, legal, and operations to govern rollout decisions and budget allocations.
- Issue an RFP that requires standards compliance, open APIs, and a testable SLAs matrix; evaluate vendors on integration risk and roadmap alignment rather than feature checklists alone.
- Engage spectrum/network partners early if considering metropolitan beacon or 5G-integrated architectures.
Closing
Indoor location is no longer an experimental add-on. With the market accelerating from a 2025 base of ~709.0 (USD Million) and a 23.8% CAGR, 2026 is a pivotal year for enterprises to convert strategic intent into governed deployments. The full PW Consulting report equips procurement, technology, and operations leaders with the granular forecasts, vendor scorecards, scenario models, and implementation tools needed to make those decisions with confidence.
For access to the complete datasets, segmented forecasts, and hands-on playbooks that underpin these recommendations, consult the full Indoor LBS market report on our website or contact your PW Consulting engagement lead.
For detailed analysis of this topic, please visit the official page: Indoor Location by Positioning Systems (Indoor LBS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com