

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automatic Car Washer Market to Hit USD 4,359M by 2032 at 6.8% CAGR

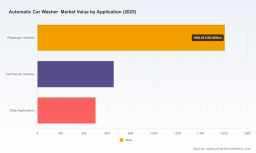
Automatic Car Washer Market 2026: Strategic Outlook and Executive Briefing
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, this introduction distills the strategic implications of our full-market study on the Automatic Car Washer industry for executives planning decisions in 2026. The sector is entering a phase where durable demand fundamentals, regulatory pressure, and rapid technology adoption intersect—creating distinct windows for value creation across equipment OEMs, site operators, service providers, and capital allocators. This briefing highlights the critical macro trends, competitive dynamics, and decision levers that our full report models in detail. Proprietary segment-level forecasts and operator-level financial templates are intentionally withheld here to direct stakeholders to the complete study for deployment-ready intelligence.
Automatic Car Washer Market
Market Snapshot: Growth Trajectory and What It Means
The global automatic car washer market has expanded steadily over the first half of the decade, rising from roughly USD 2.0 billion in 2020 to about USD 2.76 billion in 2025. Looking forward, our base-case outlook projects continued expansion through the 2026–2032 forecast window with a compound annual growth rate of 6.8%, reaching approximately USD 4.36 billion by 2032. That steady, mid-single-digit CAGR reflects a market driven by replacement demand, new installations in high-throughput commercial locations, and incremental technology-driven upselling (connectivity, water recycling, and automation).
Automatic Car Washer Market
Two implications follow for 2026 planning cycles: first, the market scale is sufficiently material to justify bespoke product roadmaps and regional go-to-market investments; second, the growth profile supports propositions—such as managed services, financing-as-a-service, and connected maintenance contracts—that convert market expansion into repeatable revenue streams.
Automatic Car Washer Market
Key Demand and Supply-Side Drivers
-
Regulatory tightening on water discharge and effluent treatment: Environmental standards are pushing operators toward integrated filtration and recycling modules. Our field-level compliance audit data show regulators increasingly require >90% treatment/reuse performance for commercial installations—making water-management capabilities a procurement discriminator.
-
Labor dynamics and operational efficiency: Rising labor costs and the need for consistent service levels are accelerating adoption of fully or semi-automated systems that reduce dependence on manual labor and shrink operating variance for high-volume sites.
-
Technology and connectivity: OEMs that embed diagnostics, remote monitoring, and digital upsell interfaces (membership management, pay-at-pump integration) capture higher lifetime value per installation. Recent new-product activity emphasizes connected gantry and tunnel platforms optimized for uptime and data-driven maintenance.
-
Investment economics: Site development and installation remain capital-intensive and influenced by local permitting, civil scope, and equipment selection. Commercial touchless and automated line investments typically fall into a range that requires disciplined ROI planning, financing structures, and phased deployment options for franchise and retail channel partners.
What Our Full Report Delivers (Practical, Actionable Content)
-
Market sizing and forward-looking forecasts (2026–2032) built from bottom-up installations, aftermarket revenue streams, and service penetration scenarios—presented with sensitivity cases for high-, base-, and low-growth paths.
-
Go-to-market playbooks for OEMs and distributors, including channel economics, partnership archetypes, and service bundle pricing strategies to accelerate adoption in dealer, convenience store, and fleet segments.
-
Capital expenditure and lifecycle cost modeling templates that let operators stress-test equipment choices, water-management investments, and financing alternatives—delivered as configurable tools for site- and portfolio-level planning.
-
Regulatory and sustainability assessment with compliance checklists and specification templates for filtration/recycling systems that meet contemporary treatment thresholds demanded by regulators and major clients.
-
Competitive intelligence dossiers on leading suppliers, plus M&A and partnership scenarios that quantify consolidation benefits and market-entry synergies—designed to support transaction diligence.
Competitive Landscape: Players, Positioning, and Recent Moves
The industry shows a moderate level of concentration: the top three suppliers account for roughly six in ten units by market influence, while the top five control a materially larger share. That structure creates a market where scale advantages—global distribution, aftermarket coverage, and financial capacity—matter, but space remains for differentiated challengers and regional specialists.
-
AUTEC Car Wash Systems (Statesville, NC) – Strengths: high-volume systems for dealerships and convenience-store operators, demonstrated capability in building 24/7 automated sites with integrated retail interfaces. Recent product catalog updates signal a push to standardize offerings across channel segments and accelerate deployment velocity.
-
Istobal S.A. (Barcelona) – Strengths: rollover/gantry systems optimized for uptime and connectivity. Istobal’s trade-show presence and connectivity platform demonstrate an emphasis on North American adaptation of proven European systems and digital maintenance tools.
-
National Carwash Solutions (Ryko) – Strengths: specialization in in-bay equipment, parts, and service networks tailored for commercial and fleet operators. Their integrated wheel-cleaning and remote monitoring capabilities make them attractive to high-utilization fleets.
-
WashTec AG (Augsburg) – Strengths: broad product portfolio spanning gantry and tunnel systems, with recent launches focused on SmartCare Connect and high-throughput turnkey projects. Product launches and contract wins in 2025–2026 underline the firm’s focus on premium, connectivity-enabled offerings.
-
U.S.-based specialists (D&S, Coleman Hanna, Carolina Pride, Prestige, PECO, etc.) – Collectively, these providers compete on local service, turnkey installations, and aftermarket support; they are often decisive in mid-market and regional rollouts where responsiveness and installation know-how matter more than global scale.
Recent developer and supplier activity illustrates where competition is heading: connected maintenance solutions and integrated service contracts; premium gantry/tunnel launches aimed at high-throughput fleets and retail partners; and product catalog refreshes that package equipment with digital revenue management tools.
Strategic Imperatives for 2026 Decision-Makers
-
For OEMs: prioritize embedded connectivity and remote diagnostics as table-stakes features. Product roadmaps should be paired with service ecosystem investments (spare parts logistics, field service training, subscription services) to convert equipment sales into recurring revenue.
-
For operators and site owners: adopt total-cost-of-ownership decision frameworks that value water-recovery, downtime risk, and customer monetization features. Financing options and partner-delivered installations lower entry barriers for growth-oriented operators.
-
For investors and strategics: consolidation opportunities exist in aftermarket service networks, digital platforms, and regional installers. The moderate concentration ratios indicate room for roll-up strategies that can extract synergies through centralized parts procurement and shared service platforms.
-
For policymakers and sustainability leads: engage with manufacturers early on standards for recycle modules and performance verification to align incentives and reduce retrofit costs across existing portfolios.
Why PW Consulting’s Full Study Is Strategic for 2026
Our full report converts the market’s macro momentum into operationally useful intelligence. Beyond headline numbers, it provides:
-
Segment-specific adoption curves and sensitivity analyses that let stakeholders prioritize product investments and geographic rollouts without overexposure to idiosyncratic risk.
-
Operator-level P&L models and financing scenarios that show breakeven horizons under multiple utilization and pricing assumptions.
-
Commercial frameworks for partnerships—OEM/distributor arrangements, per-site managed service contracts, and membership-based revenue schemes—backed by margin and cash-flow modeling.
-
Actionable M&A playbooks and diligence checklists to validate expected synergies and post-deal integration value capture.
Next Steps and How to Use This Intelligence
Use this briefing to align 2026 budgets and strategic priorities: product teams should accelerate connectivity and water-management features; commercial teams should pilot subscription and managed-service offers; investors should prioritize target screens with strong aftermarket footprints and regional service density. If your 2026 plans include new installations, retrofits, or strategic partnerships, the full PW Consulting Automatic Car Washer report contains the granular segmentation, installer-level cost templates, and market-entry playbooks you need to move from strategy to execution.
For access to the complete dataset, regional and application-level splits, operator P&L models, and customizable decision-support tools, please consult our research portal or contact the PW Consulting industry team. The full report is structured to be immediately actionable for 2026 planning and will materially shorten your path from insight to implementation.
For detailed analysis of this topic, please visit the official page: Automatic Car Washer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com