

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phosphoric Acid Market Poised for 4.7% CAGR Through 2032

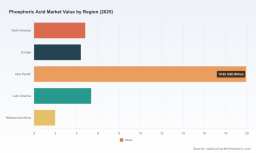
Phosphoric Acid Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As senior strategists assessing industrial chemicals in an era of supply‑side concentration and accelerating demand for higher‑purity chemistries, PW Consulting presents a forward‑looking synthesis of the phosphoric acid market that is built for strategic action in 2026. Between 2020 and 2025 the global market expanded materially — rising from roughly USD 29.5 Billion to USD 36.5 Billion (base year 2025). With a compound annual growth rate (CAGR) of 4.7% embedded in our forecast horizon (2026–2032), the market is projected to continue expanding through 2032 under a mix of structural and cyclical drivers.
Phosphoric Acid Market
Why this study matters in 2026
- Investment clarity: Capital allocation decisions for greenfield capacity, debottlenecking and specialty purification now require an integrated view of market fundamentals, project pipelines, and feedstock risk.
- Commercial positioning: Shifts toward higher‑purity grades (electronic, food, battery) create margin differentiation opportunities but require different asset configurations and supply chain commitments.
- Regulatory and ESG readiness: Environmental constraints (notably phosphogypsum disposal) and critical raw material policies are reshaping the cost of doing business and permitting timeframes.
- Procurement and hedging: Volatility in sulfuric acid and phosphate rock costs demands tactical procurement strategies and supply diversification playbooks to protect margins.
What PW Consulting’s report delivers (practical, implementable content)
- Top‑down market sizing and bottom‑up forecast (2020–2032) anchored to observable price and volume drivers — includes scenario variants for supply shocks and accelerated specialty demand.
- Supply‑chain risk matrix — phosphate rock, sulfuric acid, logistics surcharges, and regulatory chokepoints mapped to likelihood and impact scores.
- Cost‑curve analysis by process route and feedstock intensity, with sensitivity dashboards for sulfuric acid and freight cost shocks.
- Technology and product roadmaps — practical guidance for converting merchant‑grade capacity to purified, electronic and battery grades, and CAPEX/OPEX implications for each pathway.
- Project tracker and impact assessment for announced expansions and greenfield ventures — timing, strategic intent, and near‑term capacity implications.
- Commercial playbooks — contracts, offtake models, tolling options, and price‑indexing strategies for 2026 negotiations.
- Regulatory intelligence — mapped permitting risks, compliance costs, and mitigation levers for phosphogypsum management and critical‑raw‑material policy responses.
- M&A and JV screening tool — acquisition appetite vectors, integration risk checklists, and valuation templates tailored to the chemical value chain.
Note: This introduction intentionally demonstrates the analytical architecture and strategic hypotheses that underpin our study while omitting granular segmented tables and revenue breakdowns — those detailed splits are available in the full report and interactive dashboards.
Phosphoric Acid Market
Market dynamics shaping 2026 decisions
1) Supply chain concentration and raw‑material risk
Phosphate rock supply remains geopolitically concentrated and has become a policy focus. Export restrictions from major suppliers have persisted, triggering procurement stress for downstream producers that rely on merchant feedstock. The European Union’s recent classification of phosphate rock as a Critical Raw Material elevates permitting and supply‑security considerations for plants servicing EU markets. For planners, this means embedding supply‑side contingency into project sanction criteria: longer contract tenors with diversified geographies, inventory strategies, and direct upstream partnerships are now table stakes.
Phosphoric Acid Market
2) Feedstock price shocks and transport surcharges
Recent increases in sulfuric acid and transport costs — with documented supply disruptions and localized surcharges — have materially altered input cost curves. Producers integrated with sulfuric acid manufacture or long‑dated purchase agreements enjoy a cost advantage; non‑integrated merchant suppliers face pronounced margin volatility. Strategic buyers should assess counterparty exposure to these input shocks and when appropriate adopt blended procurement (spot + term) and freight‑pass‑through clauses.
3) Environmental constraints and circularity pressures
Phosphogypsum disposal restrictions, particularly in established wet‑process geographies, are driving plant‑level optimization and investment in phosphogypsum management technologies. Operators that can demonstrate robust waste handling, beneficial reuse pathways, or lower waste intensity will secure faster permitting and stronger social license — a differentiator in M&A and project finance conversations.
4) Demand diversification: fertilizers vs. higher‑purity chemistries
Fertilizers remain the single largest end‑use driver by volume, but premium growth is concentrated in purified, electronic and emerging battery‑grade phosphoric acid. This bifurcation raises strategic choices: scale commodity production to capture volume growth or re‑tool assets and capabilities to target higher‑margin specialty markets. The full report quantifies these elasticity and margin trade‑offs under multiple adoption curves.
5) Project activity and capacity choreography
Recent project moves — new electronic‑grade capacity by established specialty producers, expansion phases by integrated phosphate miners, and announced greenfield investments in new supply regions — are reordering near‑term capacity availability. These developments create both timing risks and selective arbitrage opportunities for incumbent producers and new entrants.
Competitive landscape — who matters and why
Market concentration is moderate: the three‑firm concentration (CR3) and five‑firm concentration (CR5) metrics are meaningful inputs for strategic positioning (CR3 ~42.5%; CR5 ~56.2%), indicating a market where large integrated players co‑exist with regional specialists and niche purified producers. Key firms to watch include:
- Prayon Group — a specialty leader executing capacity expansion into electronic‑grade phosphoric acid to serve semiconductor and advanced electronics demand.
- Jordan Phosphate Mines Company (JPMC) — expanding wet‑process capacity and sulfuric acid integration, illustrating the vertical‑integration route to secure feedstock and lower operating cost.
- Arianne Phosphate Inc. — pursuing battery‑grade purified pathways from high‑purity igneous feedstock, signaling the emergence of battery‑chemical value chains linked to phosphate chemistry.
- Major fertilizer integrators (e.g., Mosaic, OCP, Nutrien, Ma’aden, PhosAgro, EuroChem) — preserving volume leadership while selectively upgrading capacity for specialty downstreams.
- Specialty and food‑grade producers (e.g., Innophos, Solvay, ICL) — competing on product purity, regulatory compliance and customer qualification timelines.
Each of these business models implies different strategic moves: integrated miners prioritize upstream control; specialty producers focus on certification and ultra‑purity processes; commodity players seek scale and logistics optimization.
Recent developments to factor into 2026 strategy
- New electronic‑grade capacity construction by a leading specialty producer signals accelerated demand from semiconductors and AI hardware supply chains, creating a near‑term premium for qualified material.
- Sequential capacity lift‑outs by phosphate miners underline a tide of merchant‑grade availability but with staggered commissioning dates — an important factor for timing market entry and contract negotiations.
- Large greenfield investments in new producing jurisdictions are attracting supplier interest but will take time to reach steady‑state output, leaving supply gaps that can be monetized by agile players.
- Regulatory signals (critical raw material designations, waste disposal limits) are compressing project timelines where compliances are unresolved, and favoring producers with pre‑approved environmental solutions.
Strategic playbook for 2026 (actionable recommendations)
- Secure upstream optionality: pursue medium‑term offtake and tolling agreements with diversified feedstock suppliers; evaluate minority upstream investments to reduce supply risk exposure.
- Prioritize grade diversification: fast‑track feasibility studies for conversion pathways to purified and battery‑grade outputs where customer willingness to pay justifies incremental CAPEX.
- Embed environmental mitigation into project economics: quantify phosphogypsum liabilities and invest in reuse or neutralization options to shorten permitting cycles and reduce contingent liabilities.
- Hedge input exposure: adopt a layered procurement strategy for sulfuric acid and freight, combining term contracts, price collars and dynamic pass‑through mechanisms for major contracts.
- Pursue selective partnerships: partner with specialty players for tech transfers on purification and with miners for feedstock security; use JVs to share capital intensity and regulatory risk.
- Scan M&A for capability gaps: prioritize targets that offer purified processing, near‑market logistics, or solved environmental footprints; use our M&A screening tool to rank opportunities against integration cost multiples.
- Operational resilience: accelerate plant optimization projects (yield improvements, water and waste reduction) to defend margins against raw‑material cost swings.
How to use this report in 2026 decision cycles
Use the PW Consulting phosphoric acid study as both a strategic compass and an operational playbook. The top‑down forecasts and scenario stress‑tests inform capital allocation and pricing strategy; the project tracker and risk matrix enable procurement teams and business development leads to prioritize near‑term actions. For Board and investment committees, the report’s valuation and M&A frameworks supply the tactical criteria required for deal discipline.
We deliberately present this introduction to convey the analytical depth and practical orientation of the work while reserving the granular segmented tables, regional quotas and application‑level revenue splits for the full report and interactive dashboards. For access to the detailed datasets, plant‑level profiles, and the downloadable M&A scoring model, please refer to the report gateway or contact our consulting team for a tailored briefing.
Conclusion
Phosphoric acid in 2026 sits at the intersection of commodity demand stability and specialty upside. Success will favor organizations that combine upstream security, targeted grade upgrades, environmental competence, and agile commercial structures. PW Consulting’s full study equips executives with the directional forecasts, operational diagnostics, and executable playbooks needed to convert 2026 uncertainty into strategic advantage.
For detailed analysis of this topic, please visit the official page: Phosphoric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com