

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PTT Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Polytrimethylene Terephthalate (PTT) Market — Strategic Outlook to 2032: A Practical Brief for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a concise, strategy‑oriented introduction to our full Polytrimethylene Terephthalate (PTT) Market research. This briefing synthesizes the macro trajectory, competitive posture, and near‑term inflection points that should inform boardroom decisions during 2026. It is deliberately diagnostic rather than encyclopedic — we surface the signals that matter to executives and investors while withholding granular segment tables and confidential forecasts to preserve the value of the full report.
Polytrimethylene Terephthalate (PTT) Market
Market snapshot: growth, scale, and trajectory
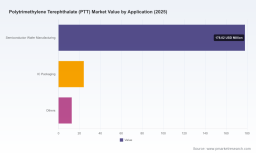
PTT has shifted from a niche specialty polymer to a market with broad industrial relevance across fibers, films, and engineered materials. Using 2025 as the base year, our consolidated model shows steady expansion through the forecasting horizon (2026–2032), underpinned by compound annual growth of approximately 6.98%. The market grew from roughly USD 163 million in 2020 to USD 215 million in 2025 and is projected to increase to about USD 224 million in 2026, culminating at roughly USD 345 million by 2032 under the baseline scenario.
Polytrimethylene Terephthalate (PTT) Market
That growth rate reflects a combination of demand diversification (apparel performance fibers, packaging and films, and selective industrial applications), structural supply investments, and policy‑driven shifts toward bio‑based and circular polymer pathways. At the same time, market concentration remains modest: the three‑ and five‑firm concentration ratios indicate a fragmented competitive field rather than an oligopoly — a dynamic that shapes strategic options for both incumbents and entrants.
Polytrimethylene Terephthalate (PTT) Market
Why 2026 is a turning point
- Regulatory acceleration: Europe’s mass‑balance accreditation for chemically recycled polymers (finalized in January 2026) creates an immediate compliance pathway that PTT producers can use to meet recycled‑content targets. This alters CAPEX prioritization and product claims strategies for market participants targeting regulated value chains.
- Feedstock volatility: Terephthalic acid and 1,3‑propanediol (PDO) feedstock cost pressures continue to shape margins and contract negotiation dynamics. High cost of bio‑PDO in particular is a clear stress point for manufacturers seeking to scale bio‑PTT affordably.
- Industrial realignment: Recent plant rationalizations and strategic collaborations — including plant decommissioning decisions, large integrated biorefinery milestones, and joint development agreements between polymer and chemical firms — indicate that players are realigning supply chains to manage feedstock security and circularity requirements.
- Application pull: Advances in textile performance fibers, specialty films for electronics and packaging, and engineered compounds for performance plastics continue to broaden commercial pathways for PTT even as traditional markets evolve.
What the full PW Consulting report delivers (operational, transaction and commercial utility)
Our full study is designed for execution teams and C‑suite leaders who need to convert insight into near‑term actions. Key, actionable deliverables include:
- Stated demand model (historical 2020–2025 and forward 2026–2032) with scenario variants driven by feedstock price shocks, policy shifts, and application uptake curves.
- Supply‑side mapping and capacity tracker including announced projects, brownfield expansion opportunity sets, and lead times for PDO and polymerization assets.
- Pricing and margin sensitivity matrices that quantify pass‑through under different contract regimes (spot, indexed, long‑term offtake).
- Regulatory and sustainability playbook — practical steps to implement mass‑balance certification, chain‑of‑custody traceability, and recycled‑content claims.
- Commercial go‑to‑market templates for three archetypal players: integrated petrochemical incumbents, specialty polymer innovators, and regional converters/compounders.
- Competitive benchmarking and target shortlist for potential M&A, joint ventures, and vertical partnerships (delivery of a prioritized contact/action list for business development teams).
- Scenario‑based investment case models (NPV, IRR, payback) for greenfield vs. brownfield additions and for feedstock co‑investment (bio‑PDO and depolymerization of PET feedstocks).
Note: to preserve the commercial utility of our models and client value, the briefing intentionally refrains from publishing granular sub‑segment revenue splits, regional percentages, and confidential pricing trajectories — all of which are available in the full report.
Competitive landscape — who matters and why
The PTT value chain features a mix of global chemical majors, specialty fibre manufacturers, regional polymer producers, and compounders. The players below illustrate the portfolio of strategic positions and the moves to watch in 2026.
- DuPont (Wilmington, DE) — Leverages its Sorona® brand and bio‑derived 1,3‑propanediol expertise to compete on high‑value performance fibers and films. Strengths: brand recognition in performance apparel and established commercial supply chains. Consideration: sustaining feedstock economics for bio‑PTT claims while expanding into new high‑margin industrial applications.
- PTT Global Chemical (Bangkok) — Operates integrated PDO‑PTT complexes and has publicly advanced biorefinery capabilities. Strengths: scale advantages and vertical integration that can lower feedstock exposure. Recent milestone: announced progress on a fully bio‑based nylon 6,6 platform in early 2026, signaling cross‑chain ambitions that can strengthen raw material resilience for PTT.
- Teijin Frontier (Tokyo) — Focused on SOLOTEX® PTT fibers with product innovation in stretch and comfort fabrics. Recent development: 2025 product launch for next‑generation stretch fabrics. Strengths: differentiated fiber technologies and close customer relationships in apparel and sportswear.
- Toray Industries (Tokyo) — Pursuing collaboration to scale bio‑based adipic acid and exploring partnerships to secure bio‑feedstock supply for both PTT and nylon families. Strengths: advanced materials portfolio and global textile/electronics channels.
- Asahi Kasei (Tokyo) — Continues to supply PTT variants but has undertaken plant rationalization and optimization, including discontinued operations in some sites. Implication: shifting capital allocation toward higher‑return or low‑carbon projects.
- Shenghong Group & Sinopec (China) — Regional integrated producers with the capability to deploy petrochemical scale into PTT. Strengths: cost competitiveness and local market access; risk: exposure to feedstock swings and policy on bio/circular claims.
- Huvis (South Korea) & RTP Company (USA) — Niche specialists focused on fibers and PTT‑based compounds respectively. They are important strategic partners for converters and OEMs seeking tailored properties or quick market access.
Market concentration metrics are modest, reflecting available runway for consolidation and opportunity for focused differentiation (product or feedstock). Recent activity — collaborations on bio‑feedstocks and rationalizations of underperforming assets — suggests an industry in rebalancing mode rather than a static competitive order.
Practical implications for 2026 corporate strategy
- Secure feedstock optionality: Executives should prioritize contracts and partnerships that provide a mix of fossil‑derived, bio‑sourced, and chemically recycled monomers. Where possible, structure offtake agreements with indexed pricing plus volume flexibility.
- Invest in certification and circular credentials: The European mass‑balance pathway materially changes the economics of recycled monomers. Certification implementation should be integrated into product roadmaps now to preserve market access and premium claims.
- Prioritize applications with structural tailwinds: While apparel and consumer textiles remain important, target industrial niches (e.g., specialty films for electronics and engineered compounds) where performance attributes and higher margins offset raw material costs.
- Pursue targeted vertical bets: Co‑investing in PDO or bio‑refinery assets (alone or via JVs) can materially reduce exposure to feedstock inflation. The PTT Global Chemical example underscores the strategic value of upstream integration.
- Recalibrate capital plans: Given lead times and regulatory changes, prefer staged brownfield expansions with off‑ramp triggers over large single‑stage greenfield builds unless paired with secured offtake and feedstock contracts.
- Explore M&A and alliances: The fragmented structure offers roll‑up opportunities for firms seeking scale and technical partnerships for specialty applications. Look for targets that add either feedstock control, differentiated product technology, or downstream customer access.
How PW Consulting helps — and next steps
Our full PTT Market report supplies the missing pieces required for operationalizing the strategies summarized above: high‑fidelity segment build‑ups, regional demand drivers, supplier scorecards, pricing matrices, and downloadable financial models calibrated for 2026 transaction work. We intentionally withheld detailed segment revenue splits and confidential pricing scenarios in this brief to preserve the strategic value delivered to subscribers and clients.
If your priorities for 2026 include managing feedstock risk, deploying capital into decarbonized feedstocks, repositioning product portfolios toward higher‑margin applications, or running targeted M&A diligence, the full report and our advisory services provide the scenario testing and execution support required to move from insight to implementation.
PW Consulting’s PTT Market study is constructed for practical use by sourcing, strategy, and BD teams — not as an academic catalog. For access to the complete dataset, segmented forecasts, and our executable playbooks, please visit our market page or contact the PW Consulting team to schedule a briefing and model walkthrough.
For detailed analysis of this topic, please visit the official page: Polytrimethylene Terephthalate (PTT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com