

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Printed Battery Market to hit USD 311.2M by 2032 at 8.25% CAGR

Printed Battery Market: Strategic Primer for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic primer designed to equip executives, investors, and product leaders with the context and decision lenses they need for 2026. The printed battery sector is transitioning from lab‑scale novelty to defined commercial pathways. Our latest market model—anchored to 2025 as the base year—shows the market expanding from roughly USD 178.8 Million in 2025 at a 2026–2032 CAGR of 8.25%, reaching an expected market size in excess of USD 310 Million by 2032. These headline numbers frame an industry that is small relative to mainstream battery markets but large enough—and fast‑growing enough—to demand deliberate corporate strategies now.
Printed Battery Market
Why this matters for 2026 decisions
-
Timing of scale investments: With a clear multi‑year growth trajectory, capital allocation toward pilot lines, roll‑to‑roll equipment, or targeted partnerships must be evaluated on a 24–36 month horizon to capture early commercial wins without overbuilding.
Printed Battery Market -
Portfolio prioritization: Printed batteries unlock product architectures (disposable smart labels, wearable medical patches, integrated IoT sensors) that are materially different from conventional cell‑based designs. Product, R&D and procurement teams must decide whether to embed printed cells, co‑design with suppliers, or remain cell‑agnostic.
Printed Battery Market -
Regulatory and end‑of‑life planning: Emerging regulation—most notably tightened European battery requirements—will materially affect manufacturing and reverse‑logistics choices. Compliance should be an explicit gating item in 2026 roadmaps.
-
M&A and partnership scouting: The market is moderately concentrated; the top three vendors account for a majority share and the top five consolidate further, producing a mix of strategic acquisition targets and preferred partners for scale.
Market dynamics at a glance
The printed battery market has demonstrated steady growth from the early 2020s into 2025, reflecting a maturation curve from R&D demos to initial commercial deployments. Our historical series shows progression from the low‑hundreds in total market value in 2020 to the mid‑hundreds by 2025—momentum that underpins our 8.25% forecast CAGR through 2032.
Two structural dynamics dominate near‑term outcomes. First, manufacturing economics: thin‑film and printed battery production requires specialized vacuum deposition and roll‑to‑roll printing equipment, and unit economics today are sensitive to throughput and yield. Second, application pull: printed batteries are finding practical uses where form factor, disposability or extreme thinness matter—logistics smart labels, medical disposables, and next‑gen wearables—rather than as broad replacements for commodity cells.
Key friction points and enablers
-
Raw materials and cost: High production costs and equipment specialization remain principal barriers to mass commercialization. Forecast scenarios in the full study model how material cost reductions, yield improvements, and equipment leasing can alter breakeven points for different production scales.
-
Manufacturing infrastructure: Scale depends on access to roll‑to‑roll lines and thin‑film deposition—capabilities that are capital intensive and concentrated among select contract manufacturers and integrators.
-
Regulatory environment: The European Battery Regulation and similar policy initiatives will tighten manufacturing and end‑of‑life obligations, creating compliance costs and opportunities for firms that can offer certified, recyclable printed solutions.
-
Demand structure: Consumer and medical use cases (smart labels, patches, embedded sensors) are driving demand patterns; success depends on winning early OEM integrations rather than pure direct‑to‑consumer plays.
What the PW Consulting report contains (practical, operational deliverables)
Our full report moves beyond high‑level forecasts to provide the operational toolset decision‑makers need in 2026:
-
A validated market model (2020–2032) with scenario stress tests that quantify the value sensitivity to yield, equipment utilization, and regulatory cost regimes.
-
Technology maturity and roadmap matrices that map chemistry choices (zinc, lithium‑based thin film, others) to performance, manufacturing requirements, and commercialization readiness.
-
Go‑to‑market playbooks for OEMs and suppliers: channel strategies, pilot design templates, pricing constructs, and sample contract language for co‑development and supply guarantees.
-
Capex and Opex benchmarking for pilot versus scale lines, including equipment vendor comparisons, expected time‑to‑breakeven at different volumes, and sensitivity tables.
-
Regulatory impact assessment and compliance checklist—particularly for European requirements—paired with end‑of‑life design guidance.
-
Supplier map and M&A shortlist: due diligence templates, valuation heuristics, and integration playbooks for strategic acquirers and private equity.
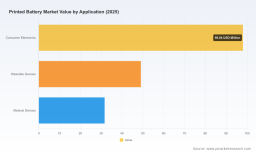
To preserve the commercial value of our IP and to comply with the “teaser” principle, granular regional or application revenue splits and unit economics are intentionally excluded from this primer and are disclosed only in the full report.
Competitive landscape — strategic implications
The competitive set is diverse: from deep‑tech startups with chemistry‑led advantages to incumbent battery manufacturers exploring printed formats. Market concentration metrics indicate a moderate to high level of consolidation: the top three players account for more than half of industry revenue, and the top five capture over 60%—a structure that favors established firms with scale and IP portfolios, while leaving room for nimble specialists to capture niche verticals.
-
Enfucell Oy: Strong positioning in custom thin, flexible SoftBattery solutions—particularly for disposable IoT sensors and cosmetics. Strategic partners should evaluate Enfucell for co‑development where unique form‑factor adhesives and printable laminates are required.
-
Blue Spark Technologies: A clear medical and continuous‑monitoring focus. Their thin, flexible printed cells make them attractive partners for medical device OEMs that need hospital‑grade monitoring with low profile batteries.
-
Cymbet Corporation: Solid‑state thin‑film expertise (EnerChip) creates an asset for embedded energy applications. Firms requiring long shelf life and high integration should consider Cymbet’s profile in selection matrices.
-
Imprint Energy (now part of CCL Industries): Zinc‑poly technology and CCL’s distribution create a route to scale for consumer IoT applications; acquisition signals that corporates may prefer buying proven chemistries rather than building from scratch.
-
FlexEl, Planar Energy, BrightVolt, Ultralife, Jenax, Samsung SDI, NEC Energy Devices, Panasonic Industry, LG Energy Solution, Power Paper: Collectively these firms represent a mix of specialist innovators and large incumbents piloting printed formats. The strategic posture ranges from vertical integration to licensing and pilot partnerships—each path offers different timelines and risk profiles.
For corporate strategists: differentiate between partners you need for near‑term pilots (specialists with rapid integration capabilities) and partners you need for volume (incumbents with manufacturing scale or distribution reach). For investors: look for tech defensibility (IP and material advantages), path to margin expansion (equipment and yield levers), and early revenue validation with repeat customers.
Recent developments you cannot ignore
-
Commercial breakthrough: a U.S. Air Force contract and seed funding win for a 3D‑printed battery firm shows defense interest in novel form factors and can accelerate manufacturing investments (Oct 2025).
-
Corporate pilots scaling: LG Energy Solution’s pilot production for foldable and rollable displays (May 2025) signals mainstream OEMs experimenting with printed formats for consumer electronics integration.
-
Strategic investment: a mid‑2025 VC investment into Jenax for bendable medical batteries underlines medical patches and wearables as priority verticals with payback potential.
Each of these developments reinforces two structural themes we model: (1) strategic customers (defense, consumer electronics, medical) can sponsor scale; and (2) corporate venturing and partnerships will be a principal route to commercial maturity.
Actionable 90‑day checklist for executives
-
Run a focused pilot funding review: allocate capital for 1–2 pilot lines with clear success criteria tied to yield and integration timelines.
-
Map regulatory exposure: identify product SKUs that will cross EU jurisdiction and build compliance costs into your 2026 P&L planning.
-
Engage 2–3 technology partners from different segments (solid‑state, zinc‑poly, thin‑film) to de‑risk chemistry bets and preserve optionality.
-
Initiate supply chain diligence for specialized equipment suppliers (roll‑to‑roll, vacuum deposition) and explore leasing/contract manufacturing options to reduce upfront capex.
-
Prepare M&A scouting: assemble target lists across the specialist/incumbent spectrum using the valuation heuristics in our report.
Closing—what PW Consulting will help you do in 2026
Printed batteries present a classic strategic choice: move early to capture differentiated product advantages and face operational challenges, or wait until the technology commoditizes—risking missed integration windows in high‑value verticals. Our full Printed Battery Market study provides the granular segmentation, cost models, supplier maps, and scenario analyses necessary to make that choice with confidence. If your 2026 roadmap includes pilots, partnerships, or potential acquisitions in printed energy storage, the report turns broad trends into executable actions.
For those ready to translate market momentum into commercial programs, PW Consulting’s industry team stands ready to support prioritized pilot scoping, regulatory planning, and transaction advisory. Detailed segmentation, unit economics and the full suite of operational templates are available in the complete report.
For detailed analysis of this topic, please visit the official page: Printed Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com