

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IC Trays Market Poised for 4.9% CAGR Through 2032

IC Trays Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s senior strategic advisor and chief industry analyst, I present a focused, actionable preview of the IC trays market as you prepare capital, sourcing, and product decisions for 2026. This briefing synthesizes our macro forecast, competitive dynamics, and decision frameworks to highlight where near-term risks and opportunities concentrate — while reserving the full segmented intelligence for the complete report.
IC Trays Market
Why IC trays matter now — and through the 2026 planning horizon
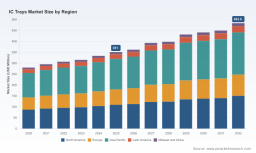
IC trays sit at the intersection of semiconductor packaging, automated handling, and global logistics. After pandemic-era disruptions and a cyclical semiconductor landscape, the IC trays market demonstrates steady expansion: our base-year analysis (2025) positions the market at approximately USD 351 million, growing at a compound annual growth rate (CAGR) of roughly 4.9% through the forecast horizon. By the end of our 2026–2032 forecast window the market approaches the upper hundreds of millions in value, reflecting continued demand from packaging and wafer-level processes, incremental automation adoption, and rising emphasis on material performance and ESD safety.
IC Trays Market
From a strategic planning vantage, the 2026 budget cycle is where procurement teams, operations planners, and product engineers must reconcile three simultaneous forces: modest but steady market growth, supply-chain fragmentation driven by geopolitics and tariffs, and intensifying sustainability and regulatory pressure on material selection and end-of-life handling. Each of these will materially affect supplier selection, inventory policy, and capital expenditure for tray-compatible automation.
IC Trays Market
Key market characteristics that should drive your 2026 decisions
- Stable growth, predictable demand elasticity: The market exhibits sustained growth without runaway volatility — a profile that favors measured capacity investments and collaborative supplier partnerships rather than speculative vertical integration.
- Moderate concentration: The top industry players account for a recognisable share of supply — our concentration metrics indicate a market where three leading firms control a material minority of supply, and the top five expand that position modestly. This structure supports competitive sourcing while rewarding suppliers that demonstrate scale and quality certification.
- Supply-chain sensitivity: Tariffs, evolving disposal and production regulations, and regional policy shifts have a direct, near-term impact on lead times and landed cost. Buyers with single-source exposure or long lead-time stock-keeping are particularly vulnerable.
- Product differentiation through process integration and customization: Firms with in-house resin technologies, mold engineering, and large injection-molding capacities command advantages in lead time and design-tailored trays for automated handling.
Competitive landscape — what the major suppliers signal for 2026
The competitive field mixes global specialists and regionally focused manufacturers. Several archetypes emerge — and each warrants a different strategic response from buyers and investors:
- Full-stack specialists with resin control and high-volume molding capability: These suppliers reduce raw-material exposure and accelerate custom-design delivery. For firms planning rapid design iterations or localized sourcing, partnership with a vertically integrated player shortens time-to-market.
- Catalog and components stockers: Companies that maintain large inventories of standard JEDEC and EIAJ trays are attractive partners for scaled manufacturers prioritizing continuity and rapid replenishment. Their value becomes especially clear under episodic demand surges.
- Custom mold and OEM/ODM partners: Smaller or flexible manufacturers with strong mold-development capabilities are key for differentiated packaging designs or proprietary automation footprints.
Representative firms in each archetype include long-established JEDEC-tray suppliers, high-capacity converters with resin production, and regional specialists focused on customized carrier products. Recent commercial activity (for example, a notable exhibitor presence at a major semiconductor materials trade event in China) underscores supplier emphasis on packaging materials as a strategic offering, not just a commodity component.
Strategic implications and recommended actions for 2026
For corporate decision-makers, the 2026 planning process should convert the market’s steady growth into defensible advantage through five priority workstreams:
- Supplier segmentation and dual-sourcing playbooks: Classify suppliers by capability (catalog stocker, custom molder, vertical resin producer) and assign sourcing strategies accordingly. For critical SKUs, establish dual-sourcing to mitigate tariff or export-control shocks.
- Inventory and contract redesign for geopolitical volatility: Shift from strict just-in-time to a hybrid policy that blends safety stock in low-cost jurisdictions with rapid-replenishment agreements in proximal markets. Negotiate longer-term pricing clauses tied to raw-material indices where possible.
- Sustainability and compliance roadmaps: Incorporate end-of-life regulations and evolving production-disposal standards into supplier scorecards. Favor partners investing in recyclable resin alternatives and traceable waste management to reduce regulatory risk.
- Design-for-handling and automation alignment: Engage early with tray suppliers when designing packaging and pick-and-place systems. Suppliers that offer JEDEC-compliant, ESD-safe trays and collaborate on tooling reduce integration risk and automation downtime.
- CapEx vs. Outsource modelling: Run scenario analyses comparing the total cost of ownership for insourcing critical molding capability versus extended supplier contracts — take into account capital amortization, technology obsolescence risk, and the flexibility premium required by fast product cycles.
How the full PW Consulting IC Trays Market report supports these decisions
The full report provides the operational instruments that turn the above priorities into executable programs. Highlights include:
- Methodology and forecast underpinning: A transparent approach linking historical shipment data (2020–2025) to demand drivers and scenario-based forecasts for 2026–2032, anchored to our 4.9% CAGR central case.
- Supplier diagnostic templates: Standardized scorecards to assess capacity, quality certifications, mold development lead times, ESD compliance, and sustainability indicators.
- Procurement playbooks and contract templates: Negotiation checklists and sample clauses for indexation, volume-flex options, and quality non-conformance remedies.
- Risk heat maps: Region-agnostic visualization tools connecting regulatory, tariff, and transport risk to specific sourcing strategies — intended to support board-level and operational planning without exposing raw supplier numbers.
- Scenario toolkits: A set of rapid-turn calculation sheets to quantify when to shift from stock-and-ship models to localized manufacture under different tariff and lead-time assumptions.
Importantly, while this preview outlines strategic directions, the report’s detailed segmentation tables, regional and application drilldowns, and supplier-level metrics are intentionally withheld here to preserve the competitive value of the primary intelligence set and to drive you to the full dossier for tactical execution.
What to watch in the near term (next 12–18 months)
- Regulatory trajectories: Expect additional national measures concerning production and disposal of polymer-based trays; early compliance planning will reduce rework costs.
- Tariff rebalances and trade policy: Short-term re-routing of orders and spot-price inflation are likely where tariffs are imposed; prioritized sourcing zones will shift accordingly.
- Supplier commercialization moves: Watch for capacity announcements and trade-show activity as indicators of where suppliers are prioritizing investment and which product types will be promoted as higher-margin offerings.
- Automation alignment: OEMs and contract manufacturers embedding tray design into automation spec sheets will favor suppliers capable of rapid tooling and tolerancing adjustments.
How to use this preview in your 2026 planning cycle
- Executive briefing: Use this briefing to align procurement, manufacturing, and product teams on the strategic posture (hedge, localize, or partner) you will adopt for 2026.
- Rapid diagnostic: Run a 30–60 day diagnostic using our supplier scorecard to triage high-risk SKUs and identify candidates for immediate dual-sourcing.
- Board-level scenario planning: Leverage the forecast and risk matrices in capital allocation discussions to evaluate modest capacity investments versus long-term contractual commitments.
- Procurement playbook adoption: Roll out the contract clauses and indexation templates to reduce spot-price and tariff exposure.
Closing — the strategic edge PW Consulting delivers
The IC trays market presents a rare combination of steady demand growth and outsized operational risk driven by geopolitics and regulation. For companies planning in 2026, success will come from pragmatic supplier segmentation, disciplined inventory redesign, and early compliance alignment. Our full PW Consulting report delivers the datasets, supplier diagnostics, and executable playbooks needed to convert this market’s predictability into tactical advantage.
To access the complete market tables, supplier profiles, and the actionable appendices (including the region and application drilldowns that support project-level investment decisions), please consult the full report on our website. The comprehensive dataset and downloadable decision tools are available there for clients planning their 2026 strategies.
For detailed analysis of this topic, please visit the official page: IC Trays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com