

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Flexible PV Cell Market Set to Grow at 13.5% CAGR to 2032

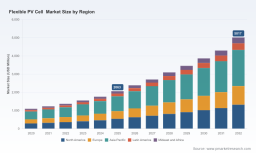
Flexible PV Cell Market 2026: Strategic Preview for Executive Decision-Making
Flexible photovoltaic (PV) cells are transitioning from niche portable-power use cases to a mainstream technology pillar across consumer, industrial and specialized applications. PW Consulting’s latest Flexible PV Cell Market research — anchored on a 2025 base year and covering 2020–2025 historicals with a 2026–2032 forecast horizon — quantifies that acceleration. The market, having grown from roughly USD 1.1 billion in 2020 to about USD 2.06 billion in 2025, is projected to continue expanding at a compound annual growth rate (CAGR) of approximately 13.5% through our forecast window, reaching roughly USD 5.02 billion by 2032. This briefing explains why that trajectory matters for choices you must make in 2026, what forces will determine winners and losers, and how our full report equips executives with actionable pathways while intentionally preserving the granular segment detail that subscribers access on our website.
Flexible PV Cell Market
Why this research is strategically material in 2026
-
Decisive investment window: With the market more than doubling from 2025 levels within the forecast period, 2026 represents a strategic inflection where capacity investments, technology bets, and commercial partnerships either amplify market share or saddle players with stranded assets.
Flexible PV Cell Market -
Margin compression and price volatility: Recent policy shifts and supply impacts are already translating into near-term module price increases. Our scenario modelling shows these shifts compress margins for OEMs and integrators unless they restructure sourcing, long-term purchasing, or move up the value chain.
Flexible PV Cell Market -
Portfolio prioritization: Corporates with multiple energy or mobility initiatives must decide whether to make flexible PV a core business line or a component technology. The right choice depends on technology roadmap, IP position, and go-to-market capabilities — all analyzed in the full report.
Key market dynamics shaping 2026 decisions
-
Robust market growth, concentrated winners to come: The overall market growth (CAGR ~13.5%) creates room for many participants today, yet structural economics point to consolidation over the next 3–5 years. Market concentration metrics indicate a still-fragmented competitive landscape — our CR3 and CR5 analysis highlights that top-tier firms do not yet dominate, leaving white-space for scale plays and differentiated technology leaders.
-
Policy and cross-border trade shocks: A major change in export rebate policy introduced in early 2026 removed long-standing PV module rebates, altering global cost curves overnight. Industry tracking suggests module prices may rise in the near-term relative to late-2025 levels, amplifying input-cost and contract risk for manufacturers and system integrators.
-
Supply-chain and raw-material stress points: Plastic substrates (polymers) remain the primary carrier for flexible cells due to weight and form-factor advantages, but they require advanced barrier coatings to meet moisture and oxygen ingress requirements for durable, field-grade products. Parallel advances in ultra-thin glass are shifting architectural use cases where long-term weathering and optical transmittance are critical.
-
Channel and application evolution: As flexible PV moves beyond portable consumer products, integration into vehicle exteriors, building facades, and aerospace platforms introduces new qualification, certification and lifecycle service needs. These create recurring-revenue opportunities for firms that can pair hardware with installation and warranty services.
Technology trajectories and materials strategy
-
Multiple chemistry pathways co-exist: Companies are pursuing thin-film amorphous silicon, CIGS variants, monocrystalline laminated approaches, and next-gen perovskite stackings. Each pathway carries trade-offs among efficiency, durability, manufacturability and cost. Our technology heat-map benchmarks these options against realistic levelized-cost targets and accelerated aging outcomes.
-
Substrate choice is a competitive lever: Polymer substrates (PET, PEN, polyimide) still dominate applications where flexibility, low weight and cost are critical. However, ultra-thin glass is emerging as a premium substrate for building-integrated and architectural installations where longevity and clarity justify price premiums. The choice of substrate affects lamination methods, encapsulation chemistry, and supplier partnerships.
-
Encapsulation and barrier technology: The durability delta in flexible PV will often hinge on coating and barrier systems rather than raw cell efficiency alone. Firms that integrate or secure proprietary barrier materials and deposition processes gain outsized advantage in warranty-backed, higher-value segments.
Competitive landscape — who to watch now
-
PowerFilm Solar (Iowa, USA) — www.powerfilmsolar.com: A well-established player specializing in thin-film amorphous silicon on polyimide substrates, PowerFilm combines roll-to-roll monolithic integration with ruggedized panels for transportation, defense and portable power markets. Their engineering focus on mechanical resilience and lightweight construction positions them strongly in mission-critical mobile applications.
-
Sungold Solar (Shenzhen, China) — www.sungoldsolar.com: Known for monocrystalline cell-based flexible modules with ETFE/PET laminates, Sungold emphasizes OEM/ODM partnerships across RV, marine and curved-surface installations. Recent certification achievements underscore their push into regulated markets and broadened commercial acceptance.
-
New-space and defense entrants: The acquisition of a radiation-hardened flexible cell manufacturer by a U.S.-based space systems firm in mid-2026 demonstrates strategic verticalization in aerospace applications. Expect more strategic M&A as prime contractors and satellite integrators close capability gaps via targeted acquisitions.
-
Market structure: Despite headline players, concentration measures show the market remains fragmented, with significant opportunities for scale, proprietary materials, or differentiated go-to-market models to shift share rapidly in the coming 24 months.
Operational and financial implications for 2026
-
Capex vs. flexibility trade-off: Large-capacity investments bring unit-cost benefits but also increase exposure to raw-material and policy shocks. We outline staged-capacity strategies and flexible manufacturing footprints that mitigate downside risk while preserving upside optionality.
-
Procurement and hedging playbook: With module price volatility expected through Q4 2026, procurement teams must balance spot buying with longer-term contracts, local inventory buffers, and supplier diversification. The report provides a procurement decision matrix tailored to different company risk appetites.
-
Commercial contracts and warranties: As flexible PV penetrates built-environment and vehicle architectures, warranty terms, certification pathways and lifecycle maintenance become competitive differentiators. We provide templated warranty structures and certification roadmaps aligned to common buyer expectations.
What the PW Consulting report includes (practical toolkit)
-
Detailed market sizing and high-resolution forecasts, with scenario variants reflecting alternative policy and supply-chain outcomes for 2026–2032.
-
Technology and materials assessment across chemistry and substrate options, including accelerated aging tests, process maturity scoring, and commercialization timelines.
-
Competitive benchmarking and vendor scorecards: in-depth profiles, strategic posture, capability gaps and potential acquisition targets.
-
Supply-chain mapping and cost build-ups: supplier tiers, critical inputs, bottleneck risk ratings, and recommendations for strategic stockpiles or nearshoring.
-
Commercial and go-to-market playbooks: channel models for consumer, B2B, BIPV and aerospace segments, plus pricing and margin frameworks.
-
M&A and investment framework: valuation comps, likely acquirers by strategic rationale, and integration checklists tailored to flexible PV technologies.
-
Decision-ready annexes: procurement templates, sample RFQs, certification checklists, and a timeline to align product launches with regulatory and market cycles.
How to use this research to make 2026 choices
-
CEOs and strategy teams: Use the scenario models to stress-test your portfolio and commit capital only against pathways that survive downside pricing and supply disruptions.
-
Product and R&D leaders: Prioritize substrate + encapsulation stacks that minimize total cost of ownership for your target segments, and lock supplier agreements for barrier materials early.
-
Procurement and operations: Layer procurement strategies (spot/term/strategic-sourcing) tied to scenario triggers we define, and evaluate nearshoring options where trade-policy risk is concentrated.
-
Investors and M&A teams: Identify conspicuous consolidation targets — capability-rich but capital-constrained firms — that can be accretive to system-level margins or IP portfolios.
Concluding strategic takeaways
The flexible PV cell market presents a clear, quantifiable growth opportunity — underpinned by a ~13.5% CAGR and an expanding revenue base that more than doubles across our forecast horizon. Yet growth alone does not guarantee profit or sustainability. The next 12–24 months will determine whether companies capture durable commercial moats via materials IP, scale manufacturing, certification competence, or integrated services. For executives setting 2026 budgets and strategic plans, the priority is to translate market growth into defensible economic returns by aligning technology choices, supply-chain architecture and commercial models to realistic policy and price scenarios.
PW Consulting’s full Flexible PV Cell Market report provides the granular segmentation, vendor-level data, and decision tools necessary to operationalize these insights — including the region-by-region, type-by-type, and application-by-application breakdowns that inform roll-out sequencing and investment sizing. For access to the complete dataset, model files and annexes that underpin our forecasts and recommendations, please visit our report page.
For detailed analysis of this topic, please visit the official page: Flexible PV Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com