

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Osteoarthritis Pain Market to Hit USD 16,590M by 2032 (CAGR 5.85%)

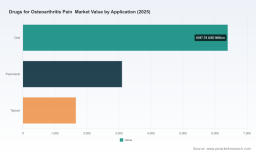
Drugs for Osteoarthritis Pain Market — A Strategic Preview for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, high-fidelity preview of our new market study, Drugs for Osteoarthritis Pain. Grounded in a 2025 base year and spanning a 2026–2032 forecast horizon, the analysis synthesizes historical trends (2020–2025) with forward-looking scenarios. The global market reached roughly USD 11,150 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.85% across the forecast window — a trajectory that lifts the market into the mid-USD 16,000s by 2032 under our central case. This brief explains why that trajectory matters for 2026 corporate strategy, what operational insights the full report delivers, and the high‑impact moves executives should be preparing now.
Drugs for Osteoarthritis Pain Market
Why this report is a 2026 strategic imperative
-
Timing: 2026 will be a pivot year where incremental clinical, regulatory and payer changes consolidate into new access pathways. Companies that align clinical evidence with validated endpoints and payer expectations will capture disproportionate commercial value.
Drugs for Osteoarthritis Pain Market -
Market momentum: A sustained mid-single-digit CAGR signals steady expansion but also intensifying competition for differentiated positioning — particularly for novel modalities and value-added formulations.
Drugs for Osteoarthritis Pain Market -
Portfolio prioritization: Resource allocation decisions made in 2026 (R&D spend, M&A targets, manufacturing investments) will determine 2028–2030 market share dynamics. Our modeling provides the growth envelopes to prioritize investments without exposing the granular splits.
-
Regulatory alignment: Recent guidance and label updates have changed the evidentiary bar for knee osteoarthritis outcomes; the companies that adapt their clinical programs fastest will shorten time-to-reimbursement.
What the PW Consulting report delivers — practical, executable intelligence
-
Robust sizing and forecasting: A verified historical series (2020–2025) and scenario-modeled forecasts through 2032. We present a central forecast (CAGR ~5.85%) plus conservative and upside scenarios tied to plausible clinical and regulatory inflections.
-
Decision-grade playbooks: Tactical guidance for product lifecycle, pricing and access strategies tailored to oral, parenteral and intra-articular channels. Each playbook translates market projections into actionable KPIs for commercial and clinical leads.
-
Regulatory and outcomes mapping: A synthesis of recent FDA and CMS guidance, validated outcome measures and label changes that should be embedded into clinical development plans to de‑risk approvals and reimbursement.
-
Competitive benchmarking: Profiles of the leading companies, their commercial strengths, and likely strategic levers — from portfolio breadth to specialty formulations — to inform M&A, partnership and alliance screening criteria.
-
Supply-chain and raw-material risk assessment: Practical mitigation options for critical inputs (including high‑molecular‑weight hyaluronate supply pathways) and contingency planning for manufacturing continuity.
-
Go-to-market diagnostic: Channels, stakeholder maps and payer negotiation frameworks calibrated to regionally differentiated market access realities (details reserved for the full report).
Competitive landscape — where winners and laggards will diverge
The osteoarthritis pain market is moderately concentrated: the top three players control roughly one-third of the market, and the top five account for just over forty percent. This leaves meaningful room for both incumbent expansion and emerging entrants with differentiated assets.
-
Large diversified pharmaceuticals (e.g., Pfizer, Johnson & Johnson, Bayer, Sanofi) retain scale advantages in manufacturing, distribution, and payer contracting. Their portfolios — heavily weighted to oral nonsteroidal anti‑inflammatory drugs (NSAIDs) — provide durable cash flow but are exposed to price erosion and generic substitution. Strategic responses include line extensions, value-added formulations, and partnership models to extend product lifetime value.
-
Specialty analgesic and consumer-health players (e.g., Haleon) leverage established OTC and Rx distribution channels for molecules like acetaminophen, but will need differentiated claims and evidence to participate meaningfully in higher-margin, clinically-driven channels.
-
Novel mechanism incumbents and developers (e.g., Eli Lilly with duloxetine positioning; AbbVie and Merck with selective COX-2 agents) face a dual task: defending share in traditional channels while investing selectively in biologic and next‑generation local therapies that command premium reimbursement.
-
Smaller innovators and biotech entrants are increasingly important as catalytic agents of disruption. Recent regulatory activity — including multiple fast track designations and IND acceptances for localized, non‑opioid, gene and neurotrophin-targeted therapies — signals a near-term wave of clinical readouts that can recalibrate competitive dynamics.
Regulatory and clinical dynamics to watch in 2026
-
Endpoint convergence: In 2024, CMS issued guidance that crystallized the role of validated knee osteoarthritis outcomes (for example, pain subscales like WOMAC) in regulatory and payer decision-making. Aligning trials to these endpoints shortens reimbursement timelines and reduces the risk of post-approval restrictions.
-
Label and evidence updates: The FDA’s 2024 label updates for select diclofenac products reaffirm efficacy signals for some NSAIDs. This has immediate implications for formulary positioning and comparative-effectiveness narratives.
-
Regulatory acceleration: Fast track designations and accepted INDs for non-opioid, local delivery and biologic candidates indicate an accelerated innovation pipeline. Commercial teams should build surveillance systems to identify candidate readouts and prepare competitive response playbooks.
-
Payer mechanics: Copay assistance and patient support programs continue to be important tools for injectable/corticosteroid access; however, payers are increasingly demanding real-world evidence demonstrating incremental benefit on validated pain measures.
-
Raw material scrutiny: High molecular weight hyaluronate — commonly sourced from animal tissues — remains a systemic supply and sustainability risk. Securing alternative suppliers or synthetic analogues is a practical priority for producers of viscosupplements.
Five priority moves for 2026
-
Recalibrate R&D portfolios around validated outcome measures. Re-design pivotal trials to align with the endpoints that payers and regulators now prioritize, shortening time to reimbursement and preserving premium pricing.
-
Invest in product differentiation that is defensible commercially. Prioritize formulations and delivery technologies (e.g., sustained-release intra-articular platforms, non-opioid local analgesics) that create demonstrable value in clinical practice and reduce head-to-head generic vulnerability.
-
Secure raw-material and manufacturing redundancy. For modalities reliant on animal-derived inputs, establish diversified sourcing and explore synthetic alternatives to mitigate price and availability shocks.
-
Operationalize “readout readiness.” Create cross-functional playbooks that can be deployed rapidly in response to competitor trial readouts or regulatory milestones — covering pricing, contracting, and targeted real-world evidence collection.
-
Adopt an opportunistic M&A watchlist. Given a market structure that is not highly concentrated, small to mid-sized bolt-on acquisitions can be transformative if they bring differentiated mechanisms, delivery platforms, or rights-complementary assets in key channels.
How to use this preview — and where to go next
This preview is intended to equip executive teams and investment committees with the strategic frame needed for 2026 decision cycles. It surfaces the macro growth path (2025 base ~USD 11,150 Million; forecast CAGR ~5.85%) and the regulatory and competitive inflection points most likely to influence near-term returns. To preserve the tactical integrity of our primary research and to ensure clients receive decision-grade granularity, we have withheld detailed subsegment allocations and region/application-level breakdowns from this summary. The full PW Consulting report contains those segmented forecasts, proprietary scoring of opportunity attractiveness by channel and patient cohort, and downloadable financial models ready for executive decks.
To obtain the full report, bespoke briefings, or a tailored scenario workshop for your organization’s portfolio, please contact PW Consulting. Our advisory team will provide the detailed segmentation, sensitivity analyses and playbooks that senior leaders need to convert 2026 market dynamics into measurable competitive advantage.
For detailed analysis of this topic, please visit the official page: Drugs for Osteoarthritis Pain Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com