

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Glucosamine Market to reach USD 1,241M by 2032 at 5.3% CAGR

Glucosamine Market 2026: Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a focused, decision-ready perspective on the glucosamine market that senior executives and corporate development teams must read before finalizing 2026 plans. This article synthesizes the study’s most consequential macro signals — growth trajectory, structural dynamics, regulatory inflection points, and competitive posture — while reserving the granular segmentation and proprietary valuation tables for subscribers of the full report.
Glucosamine Market
Executive snapshot: why 2026 is a strategic hinge year
The glucosamine market is on a steady, mid-single-digit expansion path: our modeling checkpoints the global market at roughly USD 871 million in the 2025 base year with a compound annual growth rate of approximately 5.3% through the 2026–2032 forecast horizon. Under the central scenario, this translates to a market rising toward roughly USD 1.24 billion by 2032. That profile creates a predictable growth runway, but with concentrated tactical risks — supply volatility, shifting regulatory windows across major markets, and pricing pressure on finished goods and raw inputs.
Glucosamine Market
For boards and portfolio managers, 2026 therefore looks less like a speculative bet and more like a year to operationalize growth: secure upstream feedstocks, lock preferred regulatory pathways, and convert brand propositions into differentiated dosage forms and evidence-backed clinical use cases. This preview exposes the strategic levers you must prioritize; the full report contains the detailed allocation and elasticities behind each recommendation.
Glucosamine Market
Market dynamics: what’s driving the next wave of value
-
Demand resilience and product migration: Aging populations in developed markets and rising middle‑class health spending in select emerging economies sustain base demand for joint-health products. At the same time, product innovation — including novel dosage forms, combination formulations (e.g., with MSM, chondroitin), and fortified functional foods — is expanding the total addressable market beyond traditional supplement channels.
-
Raw material economics and supply risk: Bulk glucosamine sulfate from Asian shellfish sources has historically traded in a band between approximately €12 and €20 per kilogram depending on harvest cycles and logistics. Short-term supply disruptions tied to shellfish availability and shipping create a measurable production risk (our supply‑side stress tests indicate downside pressure on global production in the vicinity of 0.8% under acute disruption scenarios). For procurement teams, this creates an imperative to hedge supply through multi‑sourcing, long‑dated contracts, or investments in alternative feedstock technology.
-
Regulatory and commercialization tailwinds: Changes in notification processes in major jurisdictions — notably the FDA’s revised dietary supplement notification procedures in March 2024 — have compressed product launch timelines and lowered friction for innovative dosage forms. Additionally, recent approvals from China’s National Medical Products Administration for glucosamine sulfate products (2025–2026) open a clinical-adjacent pathway in one of the largest joint-health prescribing markets, shifting the competitive gravity toward firms that combine regulatory expertise with local market access.
-
Reimbursement and care-economics constraints: Public payor coverage for joint-related interventions continues to lag inflation; hospital surveys suggest reimbursement dynamics cover roughly $0.83 for every dollar of nominal spend in related care segments. That gap increases pressure on manufacturers to demonstrate cost-effectiveness and secure formulary placements or bundled-care inclusion where possible.
Competitive landscape: structure, players, and strategic postures
The market is meaningfully fragmented: the largest few players account for roughly a quarter of global market share, leaving substantial room for regional specialists, ingredient suppliers, and vertically integrated producers to gain. From a strategic standpoint, six archetypes dominate the competitive map and inform best-response options for incumbents and new entrants alike:
-
API and ingredient suppliers (e.g., Cargill, Koyo Chemical, Cellmark, Spectrum Chemical): These players control scale, quality certifications, and supply reliability — the primary bargaining chips in an industry where raw material consistency matters for finished‑product claims. Their strategic moves (capacity additions, sustainability sourcing, contract pricing) directly influence COGS for finished-goods manufacturers.
-
Regional and therapeutic-focused pharmaceutical firms (e.g., Fusen Pharmaceutical, Zhuhai Rundu): Recent regulatory approvals for glucosamine sulfate formulations in China underscore a shift — these firms are pursuing clinical positioning for glucosamine in osteoarthritis treatment, effectively blurring the line between nutraceutical and therapeutic markets in jurisdictions with permissive regulatory frameworks.
-
Large branded nutraceutical consumer companies (e.g., NOW Foods, Schiff Nutrition, Nutramax, Amway, Glanbia): These operators leverage broad distribution networks, brand trust, and multi-channel retail strategies to convert ingredient availability into high-margin finished goods. Their playbooks emphasize formulation differentiation, clinical substantiation, and retail slotting.
-
Supply-chain innovators and speciality producers (e.g., TSI Group, Panvo Organics, Zhejiang Aoxing): Niche producers focus on alternative feedstocks, marine biotechnology, or high-purity API for clinical use. They are natural partners or acquisition targets for larger ingredient firms seeking resilience or bio‑innovation capabilities.
-
OEM/contract manufacturers and private-label specialists (including several Chinese producers and select Western CMOs): These firms enable rapid commercial scale‑up for brands lacking internal manufacturing. Their cost competitiveness makes them central to market expansion in price-sensitive channels.
-
New‑model entrants combining tech and supply (emerging marine biotech players): These firms emphasize sustainability claims, traceability, and premium pricing — attractive for brand portfolios targeting conscious consumers and for payors seeking documented provenance.
Importantly, the recent regulatory approvals by major Chinese firms in 2025–2026 will accelerate national commercialization and create export opportunities for firms that can meet GMP and NMPA post-approval obligations. That makes 2026 a battleground year for partnerships, licensing, and selective M&A.
What the PW Consulting report delivers (operational highlights)
The full study — designed for strategy teams, M&A groups, and procurement managers — translates headline forecasts into executable workstreams. Key deliverables include:
- Stamped market sizing and a demand model calibrated to population aging, channel migration, and product substitution dynamics (base year 2025; forecast 2026–2032).
- Scenario analysis and sensitivity matrices showing P&L impacts of ±25% swings in raw input pricing and ±1.5 percentage point shifts in reimbursement metrics.
- Supply‑chain heatmaps and risk-ranked supplier lists with mitigation playbooks (contract structures, dual-sourcing thresholds, and onshore buffer economics).
- Regulatory playbooks for the US, EU, China, and selected APAC markets — including dossier templates, clinical evidence requirements for therapeutic claims, and accelerated notification pathways for supplements.
- Competitive profiles and capability assessments for the primary companies in the space, plus an M&A target scoring model based on strategic fit, cultural alignment, and integration complexity.
- Commercial go-to-market blueprints: channel‑specific pricing, retail-pack innovation, and evidence-based physician engagement strategies where therapeutic positioning is pursued.
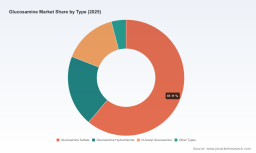
Note: the report contains full segmentation by geography, product type, and application — those discreet splits and proprietary unit economics are intentionally withheld from this preview to protect subscriber value and to encourage direct access to the full dataset.
Immediate strategic recommendations for 2026
-
Procurement and supply: Secure at least one multi-year supply agreement with a primary API supplier and onboard a qualified secondary supplier from a different geography. Consider partial forward purchasing to cap exposure to the historical €12–20/kg swings and build a small strategic inventory buffer for Q2–Q3 2026.
-
Regulatory and clinical alignment: If targeting therapeutic positioning in China or similar jurisdictions, fast-track dossier preparation and local pharmacovigilance infrastructure. For supplement-focused brands, use the FDA’s streamlined notification pathways to introduce differentiated dosage forms quickly while documenting comparative outcomes to aid future reimbursement discussions.
-
M&A and partnership playbook: Prioritize targets that offer either supply resilience (alternative feedstock, marine biotech) or routable local regulatory capability in China and other fast-growing markets. Given fragmented share structure, opportunistic acquisitions at reasonable multiples can rapidly scale market presence.
-
Commercial execution: Invest in clinical evidence generation that aligns with payor value propositions — cost-effectiveness analyses and real-world evidence pilots strengthen bargaining positions with healthcare purchasers and specialty retailers.
Conclusion — from insight to action
By 2026, glucosamine will still look like a classic nutraceutical growth story on the surface: steady demand, mid-single-digit CAGR, and ongoing product innovation. Underneath, however, the industry will be reshaped by supply-chain decisions, regulatory approvals in strategic jurisdictions, and a competitive mix that rewards both scale and niche technical capability.
PW Consulting’s full Glucosamine Market report equips you with the granular inputs and playbooks necessary to convert that macro growth into margin and market share. For detailed segmentation tables, supplier-level pricing forecasts, and the full set of scenario models referenced above, please consult the complete study on our website — the tactical levers you execute in 2026 will determine whether you capture share or simply participate in a growing, but increasingly contested, market.
For detailed analysis of this topic, please visit the official page: Glucosamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com