

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medium Voltage Ring Main Units Market to Hit USD 344.8M by 2032 (6.98% CAGR)

Medium Voltage Ring Main Units: Strategic Imperatives for 2026 — A PW Consulting Market Primer
Executive snapshot
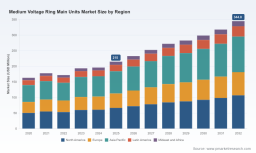
The medium voltage (MV) ring main units (RMUs) market is entering a pivotal phase as utilities, infrastructure developers and industrial buyers move from pilots to procurement scale in 2026. Our PW Consulting industry model — anchored on a 2025 base year and a seven‑year forecast horizon (2026–2032) — shows the global market expanding from a 2025 size of approximately USD 215.0 Million to an anticipated USD 344.8 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.98% through the forecast period. Historic market dynamics (2020‑2025) reveal resilience, with cyclical rebounds and technology-driven refreshes shaping demand profiles.
Medium Voltage Ring Main Units Market
Why this report matters for 2026 decision cycles
-
Regulatory inflection points are forcing strategic choices now. Strengthened F‑gas rules in the EU and similar policy signals globally have accelerated buyer preference for SF6‑free RMU designs and low‑GWP alternatives. Suppliers and buyers delaying a definitive product strategy risk sudden compliance costs, longer lead times and procurement disruptions when tenders explicitly require zero‑GWP solutions.
Medium Voltage Ring Main Units Market -
Supply‑chain realism: SF6 scarcity and rising constraints on fluorinated gases have changed component sourcing economics and elevated the value of design flexibility. Manufacturers that have validated alternatives (clean‑air, fluoroketone, hydrocarbon blends, solid dielectrics) and secured supply relationships are positioned to protect margin and delivery reliability. For buyers, contract clauses around refrigerant substitution, end‑of‑life handling and secondary market responsibilities are now table stakes in 2026 RFPs.
Medium Voltage Ring Main Units Market -
Digital convergence: RMUs are no longer purely electro‑mechanical assets. Mainstream adoption of IEC 61850‑compatible communications, local protection relays with self‑powering options, and edge analytics for fault isolation is changing total cost of ownership. Early movers in smart RMU deployments are already capturing service revenue, improving network reliability and compressing outage durations — outcomes that should shape CapEx vs OpEx tradeoffs in 2026 budget cycles.
-
Market structure influences strategy: The MV RMU sector remains relatively fragmented, with the top players not yet dominating the market concentration landscape. That fragmentation creates opportunities for mid‑market consolidation, private‑equity participation and regional champions that combine manufacturing scale with application‑specific innovations (e.g., wind‑farm RMUs, tower‑mounted units, or compact urban modules).
What PW Consulting’s full study gives you (practical, actionable content)
This market primer is a selective preview of a comprehensive practice playbook our full report delivers to executive teams preparing 2026 roadmaps. Highlights from the full study include:
-
Demand forecasting and scenarios: A base forecast reconciled to 2020–2025 history and three alternative scenarios (policy‑tight, technology‑shift, and delayed investment) for 2026–2032 that quantify risk to revenue and inventory planning.
-
Procurement playbook: Tender language templates, specification checklists (including environmental, interoperability and cyber‑security clauses), and comparative lifecycle cost models to evaluate SF6‑free versus conventional RMUs under realistic operational profiles.
-
Technology roadmap and validation framework: A decision tree for selecting insulation technologies (clean‑air, solid dielectric, alternative gases), evaluation protocols for field trials, and failure‑mode analysis covering sealing, arc‑interruption and condition‑based maintenance challenges.
-
Commercial and pricing intelligence: Win/loss drivers, dealer‑channel dynamics, aftermarket revenue pools and price sensitivity analysis to support 2026 commercial negotiations and margin planning.
-
M&A and partnership heatmap: Target profiles and value levers for bolt‑on consolidation — including regional manufacturers, specialized component suppliers (vacuum interrupters, compact GIS modules), and digital‑services integrators.
-
Regulatory and standards tracker: An interpretation engine mapping upcoming regulation changes to practical compliance steps, certificate timelines and retrofit pathways.
Note: The full study contains granular splits by region, type and application to support deployment‑level planning. This primer intentionally omits those finer breakdowns to protect proprietary modelling insights — access to the full dataset and interactive dashboards is available on our source page.
Competitive landscape — positioning and strategic moves to watch
The RMU vendor field is characterized by differentiated product portfolios, regional manufacturing footprints and an accelerating pivot to SF6‑free and smart offerings. A short synthesis of strategic positions:
-
ABB (Zurich, Switzerland) — Strong in compact GIS RMUs and indoor/outdoor modular systems; notable for SF6‑free air variants and a recent investment commitment to capacity and R&D for higher‑voltage GIS RMUs. Expect ABB to leverage scale, engineering depth and channel relationships to defend premium segments.
-
Schneider Electric (Rueil‑Malmaison, France) — Combines high installed base scale with smart RMU productization and IoT connectivity; recent large commercial wins underline momentum in specifying SF6‑free units for urban distribution. Schneider’s global footprint and software ecosystem make it a preferred partner for utilities targeting digitalized distribution networks.
-
Eaton (Dublin, Ireland) — Emphasizes vacuum interrupters and smart‑grid readiness. Eaton’s SF6‑free developments and secondary‑distribution focus align with utilities seeking retrofitable solutions and staged modernization programs.
-
Siemens (Munich, Germany) — Investment in regional capacity and a focus on clean‑air insulation and AI‑enabled fault detection position Siemens to capture projects where reliability and digital services are procurement priorities.
-
Regional and emerging players — Manufacturers such as CHINT, Lucy Electric, C&S Electric, CG Power, Liyond, Orecco and others are capturing demand through cost‑competitive local manufacturing, product variants optimized for specific applications (e.g., wind farms, tower‑mounting), and growing intelligence in protection and fault‑isolation features. Recent dispatches and contract wins illustrate that these firms are increasingly competitive in both domestic and export markets.
Collectively, the competitive field is moving toward three converging themes: SF6‑free standardization, digitalization of protection and communications, and manufacturing agility to manage lead times. These themes should guide supplier selection and partnership strategies in 2026.
Strategic moves to prioritize in 2026
-
Adopt a dual‑track product strategy: certify a compliant SF6‑free platform for imminent tenders while retaining retrofit pathways for legacy inventories. This balances regulatory compliance with capital efficiency.
-
Lock down critical component supply: focus on vacuum interrupter capacity, fluoroketone and solid‑dielectric suppliers, and critical sealing materials. Consider long‑lead framework agreements to hedge scarcity and price volatility.
-
Accelerate smart RMU pilots into commercial rollouts: target network segments where IEC 61850 communications and edge protection materially reduce outage costs; use pilot ROI to justify scale deployments in 2027 budgets.
-
Revisit aftermarket economics: service contracts, condition‑based maintenance subscriptions and managed‑services models are tangible ways to monetize digital upgrades and offer lower TCO to buyers.
-
Pursue selective M&A and alliances: prioritize targets with localized manufacturing, validated SF6‑free technologies, or digital‑services capabilities to close capability gaps quickly and economically.
How PW Consulting helps
For executive teams preparing 2026 procurement cycles, the full PW Consulting MV RMU study combines quantified forecasts, scenario stress tests, supplier benchmarking and executable procurement tools. The report is built to move councils of CFOs, CTOs and procurement directors from debate to decision with confidence and minimal rework.
Next steps
This primer surfaces the essential strategic imperatives for 2026, while reserving the granular segmentation and interactive modelling that underpin deployment‑level decisions. For access to the full forecast dataset, regional and application splits, supplier scorecards and downloadable RFP templates, please consult the full report on our source page — the data you need to convert 2026 uncertainty into a competitive advantage.
For detailed analysis of this topic, please visit the official page: Medium Voltage Ring Main Units Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com