

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lubricating Grease Market to Grow at 4.6% CAGR Through 2032

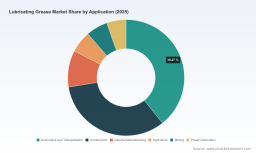
Lubricating Grease Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s market intelligence team presents a strategic preview of the global lubricating grease market that frames the near-term (2026) decision horizon against a full 2026–2032 forecast. The market reached an estimated USD 6.85 Billion in our 2025 base year and, under our central scenario, expands at a compound annual growth rate of 4.6% across the forecast window. By 2032 the market is projected to approach the upper single-digit billion-dollar range. This preview highlights the decision levers, competitive moves, regulatory inflection points, and supply-side dynamics that will determine winners and losers in 2026—while reserving full segment-level tables and granular figures for the published report and interactive data portal.
Lubricating Grease Market
Why this matters in 2026
-
Timing of transition: 2026 is a tipping year for formulation and supply-chain adjustments. Recent regulatory actions and voluntary phase-outs have accelerated demand for PFAS-free and renewable formulations—forcing product roadmaps, qualification cycles, and procurement contracts to re-align within planning horizons that many organizations use for capital and procurement decisions.
Lubricating Grease Market -
Margin pressure and cost pass-through: Input-price normalization for several key raw materials has reduced short-term volatility, but structural cost pressures remain for specialty thickeners and additive packages. Companies that can model and execute selective price realization while protecting demand resilience will preserve margins and fund R&D shifts.
Lubricating Grease Market -
Concentration and competitive dynamics: The market sits at a moderate concentration level with the top global suppliers controlling a majority share. This creates an environment in which scale advantages (supply security, R&D, branded aftermarket access) coexist with targeted opportunities for regional specialists and formulation innovators.
Key structural dynamics shaping 2026 strategies
-
Regulatory reconfiguration — PFAS and food-contact rules: A cascade of regulatory actions in 2024–2026 (including national prohibitions and expanded PFAS restrictions in major jurisdictions) has moved PFAS risk from “emerging” to “operational.” Procurement teams must now incorporate regulatory deltas into approval matrices, and product teams must validate alternatives within shortened timelines. Our fieldwork shows that lead times for requalification in critical end-markets have compressed; companies that front-load compliance testing will avoid aftermarket disruption in 2026.
-
Raw-material normalization, with caveats: Lithium hydroxide and other inputs saw stabilization trends through 2024, reducing near-term commodity shock risk. That said, supply-security risk remains for niche additives and renewable ester feedstocks. Scenario planning that includes supplier outage and rapid substitution pathways will be table stakes for procurement and operations teams.
-
Customer and application shifts: End-market maintenance strategies (predictive maintenance, extended drain intervals) and OEM specification policies are evolving. These forces favor premium and specialty greases in certain vehicle fleets and industrial fleets, while commoditization pressure persists in high-volume, low-differentiation segments.
-
Innovation vectors: PFAS-free, bio-based esters, and lithium-complex alternatives have moved from lab demonstrations to commercial launches. Early adopters are seeking formulations that deliver parity in performance at acceptable TCO changes—creating room for value-based pricing and bundled service propositions.
Competitive landscape — what the frontrunners are doing
-
Integrated majors (e.g., global petroleum and energy companies): These firms leverage global distribution, formulation portfolios, and aftermarket channels. Recent capacity investments aimed at food‑grade and high-temperature products reflect a strategy to protect established B2B contracts and meet compliance-driven demand in regulated geographies.
-
Specialty lubricant manufacturers: Companies focused on high-performance and niche greases are playing a two-track game: protecting industrial-grade, heavy-duty accounts while introducing PFAS-free and bio-based SKUs to capture premium positioning. Product launches that align with REACH-like restrictions are a visible example of strategic timing.
-
Regional producers: Capacity expansions in key industrial markets aim to secure cost-competitive supply for local heavy industries. These moves reduce logistics exposure for large accounts and create price flexibility in regional tenders.
-
Market concentration implications: With more than half of market value held by the leading three players and a roughly two-thirds share by the leading five, competitive behavior will continue to shape access to OEM channels, specification influence, and the speed of new-product ramp-up.
Recent strategic moves to watch
-
Targeted capacity expansions for food-grade and high-temperature greases—these respond directly to demand shifts tied to food-safety compliance and industrial thermal applications.
-
PFAS-free product introductions using renewable esters—this is the first wave of commercially scaled formulations intended to meet REACH and national PFAS restrictions while minimizing performance trade-offs.
-
Regional capacity growth for high-temperature lithium greases serving heavy industries—a supply-side response to steel, cement, and similar sectors that require high-durability formulations.
What PW Consulting’s full report delivers (operational highlights)
-
Segmented demand model: Annualized, SKU-level demand projections across 2020–2032, with sensitivity bands reflecting regulatory, price, and technology scenarios. (Note: detailed regional/application splits and underlying unit-volume tables are available in the full dataset.)
-
Price and margin playbook: Scenario-based analyses that quantify cost-pass-through possibilities, margin resilience thresholds, and commercial levers for value capture.
-
Supplier and input-risk map: A prioritized view of raw-material supply risk, including alternative-sourcing pathways, contract hedging guidance, and lead-time mitigation actions.
-
Regulatory compliance toolkit: A practical matrix mapping jurisdictional PFAS and food-contact requirements to likely engineering and testing implications, with an estimated qualification timeline for product teams.
-
Competitive benchmarking and M&A heatmap: Comparative analysis of product portfolios, channel footprints, R&D intensity, and likely strategic targets should consolidation accelerate.
-
Go-to-market playbooks: Segment-specific commercialization strategies for premium, specialty, and cost-competitive product lines—covering OEM engagement, aftermarket distribution, and digital services for predictive lubrication.
Actionable guidance for 2026 planning cycles
-
Prioritize regulatory-aligned SKUs: Create an accelerated R&D and qualification pipeline for PFAS-free and REACH-compliant formulations. Time-to-market in 2026 will confer specification advantages in safety-conscious and regulated customers.
-
Reassess procurement contracts with embedded flexibility: Negotiate clauses that allow for additive substitution and capacity reallocation without punitive penalties—this is critical if regional restrictions require rapid reformulation.
-
Targeted capacity investment, not blanket expansion: Align capital expenditure to the segments where premiumization and specification lock-in are most likely. Use regional demand overlays to prioritize plants that serve regulated or high-growth geographies.
-
Corporate development discipline: Evaluate M&A and partnership opportunities that accelerate access to PFAS-free chemistry, renewable ester feedstock, or specialty thickener technology—prefer deals that compress certification lead times with key OEMs.
-
Commercial model evolution: For premium specialty greases, consider bundling formulation assurance, on-site lubrication audits, and drain-interval analytics to shift the conversation from price to total lifecycle cost.
Methodology and robustness
Our findings draw on a blended methodology: bottom-up demand modeling calibrated to 2020–2025 historicals, primary interviews across OEMs, formulators, and distributors, and a scenario overlay that tests regulatory, price, and technology shocks. The central forecast uses a 4.6% CAGR for 2026–2032; alternative scenarios stress-test that trajectory against accelerated regulatory tightening and faster-than-expected adoption of bio-based chemistries. The report articulates assumptions, confidence intervals, and a replicable model that clients can use for internal sensitivity analysis.
Why PW Consulting’s intelligence is strategically different
-
Operational orientation: Beyond market sizing, our deliverables are designed to be executable—roadmaps include R&D timelines, procurement triggers, and suggested contract language for risk-sharing.
-
Competitive triangulation: We map not only what incumbents are selling, but how product portfolios, distribution networks, and recent capacity moves interact with regulatory momentum to create transient advantages.
-
Decision-grade scenarios: Each recommendation is backed by scenario-specific playbooks that translate market movement into discrete decisions for 12–36 month planning cycles.
Next steps — where to get the full intelligence
This strategic preview intentionally surfaces the high-level trends, competitive behaviors, and actionable implications for 2026 decision-making while withholding core sub-segment tables and granular monetized breakdowns to preserve the value of our full dataset. The complete report and interactive dashboard provide country- and application-level splits, SKU- and pack-size models, supplier scorecards, and downloadable scenario models to support budgeting, capex, procurement, and M&A diligence.
For executive briefings, tailored scenario runs, or access to the full dataset and supporting Excel models, visit the PW Consulting research page associated with this study. Our advisory team is prepared to run a client-specific 12–36 month roadmap that aligns product, operations, and commercial priorities with the regulatory and supply dynamics described above.
For detailed analysis of this topic, please visit the official page: Lubricating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com