

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Interface Bridge ICs Market to Hit USD 2.52 Million by 2032 at 2.8% CAGR

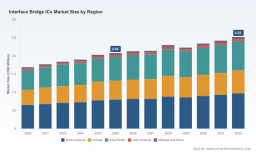
Interface Bridge ICs Market: Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused briefing designed to equip senior executives and strategy teams with the judgement frameworks and tactical prompts they will need in 2026. This preview synthesizes the structural drivers, competitive dynamics, and pragmatic levers that will matter most to players across the value chain — semiconductor vendors, system OEMs, Tier‑1 suppliers, and procurement organizations. It intentionally showcases analytical depth while withholding the granular segmentation tables and microdata that underpin our full study, so that you are compelled to access the complete report for transaction‑grade intelligence.
Interface Bridge ICs Market
Market at a glance: trajectory, scale and concentration
The Interface Bridge ICs market has demonstrated steady, low‑single‑digit expansion through the first half of the decade. Our base‑year assessment (2025) sits on a continuous historical series from 2020–2025 that shows measured growth from the market’s 2020 level to 2025, and a conservative outlook through our forecast window of 2026–2032. The market is projected to grow at a compound annual growth rate (CAGR) of approximately 2.8% over the forecast period.
Interface Bridge ICs Market
Put simply: this is not an explosive, high‑growth market; it is a mature segment characterized by incremental volume and value expansion tied to steady demand in consumer, industrial and automotive subdomains. That stability creates a particular type of opportunity — one where margin optimization, platform consolidation, and differentiated system integration are often more valuable than attempting to chase volume alone.
Interface Bridge ICs Market
Concentration is high. Our measured market concentration suggests that the top three suppliers capture roughly nine out of every ten dollars of market revenue, and the top five players account for essentially the entire market that we measured. This level of consolidation creates both barriers and levers: it elevates the strategic importance of supplier relationships and IP licensing, while making distributor, aftermarket, and niche offerings attractive corners for innovators and challengers.
Dynamics shaping 2026 strategy
- Demand steady, but structural shifts matter. Growth is driven by gradual refresh cycles in consumer electronics, incremental electrification and zonal architectures in automotive, and steady industrial automation upgrades. New system architectures (e.g., zonal controllers, camera clusters, and multi‑sensor clusters) change interface requirements more than they change raw volume.
- Supply and cost pressures remain a tactical concern. Our market conversations and industry price checks indicate notable price differentials between commodity bridge ICs and higher‑grade equivalents. For example, authentic commodity USB‑to‑serial bridge devices are available at deeply economical unit prices compared with legacy premium parts — a factor that influences BOM decisions and supplier selection for cost‑sensitive assemblies.
- Integration and protocol convergence. Vendors are pushing highly integrated solutions (driverless operation, USB‑C/PD support, multi‑channel bridging) that compress board area, software maintenance burden, and certification risk for OEMs. The result: competitive advantage accrues to suppliers who combine silicon capability with reference firmware and packaging optimized for system adoption.
- Regulatory and automotive qualifications. Automotive and industrial safety certifications raise the entry bar; suppliers with proven roadmaps to AEC‑Q and functional‑safety readiness are able to command both premium pricing and longer‑run contracts.
What our full report delivers (operationally focused)
Our full Interface Bridge ICs report is designed to be immediately actionable for commercial, product and M&A teams. Highlights include:
- Validated market sizing and scenario models (historical 2020–2025; forecast 2026–2032) with configurable assumptions so you can stress‑test price erosion, content per unit, and adoption curves.
- Supplier scorecards that combine technical capability, qualification maturity, supply reliability, and commercial posture — presented to support vendor shortlisting and dual‑sourcing design decisions.
- Use‑case profitability maps and BOM impact calculators to quantify margin and NRE implications of choosing different bridge architectures across representative end products.
- Procurement playbooks and negotiation levers tailored to both commodity and higher‑value bridge IC segments, including recommended contract terms, lead‑time hedging, and quality auditing checklists.
- Risk heatmaps covering supply constraints, IP exposure, and compliance timelines, with recommended mitigation measures for each risk bucket.
- Deal and partnership playbooks for potential M&A or strategic alliances — including target archetypes and price/earnings sensitivities (redacted here for brevity; fully detailed in the report).
These operational assets are designed to remove friction between strategy and execution: they let product leaders plug market economics directly into their roadmap prioritization, and they give procurement teams negotiation tools grounded in contemporary supplier economics.
Competitive landscape: who matters and why
The market’s high concentration means that a small number of established incumbents set technological norms and supply terms. Key players we profile include global diversified semiconductor groups, targeted interface specialists, and regionally strong manufacturers. Below is a synthesis of strategic positioning and near‑term implications for each.
- Toshiba (Tokyo, Japan) — Strengths: diversified portfolio across display, camera, HDMI bridge and I/O expansion for mobile and automotive IVI. Strategy implication: Toshiba’s breadth makes it a preferred partner for OEMs seeking component consolidation across multiple interface modalities and vehicle clusters.
- Silicon Labs (Austin, USA) — Strengths: driverless, highly integrated USB‑to‑UART bridge ICs (recent CP2102C family). Strategy implication: their push into single‑chip USB‑C solutions reduces BOM complexity and firmware overhead, making them attractive to embedded systems integrators seeking rapid time‑to‑market.
- FTDI (Glasgow, UK) — Strengths: high‑performance USB bridge ICs, multi‑channel MPSSE, Type‑C/PD and automotive‑grade showcases. Strategy implication: their demonstrated commitment to automotive roadmaps positions them well for safety‑critical applications where graded components matter.
- NXP Semiconductors (Eindhoven, Netherlands) — Strengths: discrete bridge solutions for zonal architectures and automotive networking. Strategy implication: NXP’s systems heritage makes it an anchor vendor for tier‑1s standardizing zonal ECUs and network gateways.
- Texas Instruments (Dallas, USA) — Strengths: high‑speed data conversion bridge ICs for industrial and automotive. Strategy implication: TI’s strength in analog/mixed signal and system certification is a differentiator where signal integrity and EMC compliance are constraining factors.
- Microchip Technology (Chandler, USA) — Strengths: USB‑to‑serial bridges for cost‑sensitive embedded designs. Strategy implication: Microchip is an attractive choice for high‑volume lower‑complexity designs focused on unit‑cost efficiency.
- Holtek (New Taipei City, Taiwan) — Strengths: regional manufacturing of USB‑UART bridge devices and competitive serial conversion offerings. Strategy implication: holistic supply alternatives for system integrators needing diversified sources in APAC.
Recent industry movements underline the strategic themes above: Silicon Labs’ launch of a CP2102C class device with USB‑C and driverless operation (March 2025 announcement) is a reminder that integration reduces system BOM and software maintenance costs. FTDI’s prominent automotive display at Embedded World 2026 highlights that automotive qualification and PD support are now table stakes for suppliers vying for vehicle‑grade wins.
One tactical market noise item to flag: commodity supply pricing demonstrates how much BOM choice matters. Industry checks indicate widely different unit price points between authentic commodity parts and legacy premium devices; this spreads procurement strategy across “cost‑first” and “qualify‑for‑lifecycle” mindsets.
Strategic implications and recommended actions for 2026
For management teams planning capital allocation, product roadmaps, or supplier strategies in 2026, we recommend prioritizing the following actions:
- Reassess BOM segmentation: Establish a two‑track BOM strategy (commodity vs. qualified premium) and define clear decision gates for channeling volume into each track based on lifecycle, safety requirements, and aftermarket economics.
- Accelerate supplier qualification where differentiation matters: For automotive and industrial segments, urgently qualify 2–3 alternative suppliers to reduce single‑vendor exposure and to secure favorable lead times and pricing.
- Capture integration value: Where possible, migrate to integrated bridge ICs that reduce board complexity and firmware overhead. Calculate TCO impacts over a three‑year horizon before committing to legacy discrete architectures.
- Lock in long‑lead supply for specialized parts: For vehicle programs or industrial platforms with long certification tails, negotiate multi‑year capacity commitments with clear quality SLAs and escape clauses tied to certification delays.
- Explore product adjacency via partnerships: For suppliers and OEMs, consider technology partnerships that bundle silicon with reference firmware and test suites to lower customer adoption friction.
- Monitor price elasticities and substitute availability: Implement a rolling procurement dashboard that flags sudden unit‑price deviations in commodity bridges; rapid swaps to alternative parts can materially protect gross margins.
- Use market concentration to your advantage: If you are a buyer, leverage incumbent dependence on a few large customers to secure preferential terms; if you are a potential entrant, seek white‑space niches created by incumbents’ focus on large OEMs.
How to use PW Consulting’s full report
The full Interface Bridge ICs Market report expands each of the sections summarized above into transaction‑grade modules. If you are preparing to:
- negotiate supplier contracts for a high‑volume program, the supplier scorecards and procurement playbooks will supply the model inputs and sample contract language;
- evaluate an acquisition or strategic investment, our valuation scenarios and comparable transactions matrix provide calibrated price bandwidths and synergy estimates;
- optimize a product roadmap, our BOM impact simulators and adoption curves can be integrated with your P&L models to show margin and NRE trade‑offs;
- create a resilience plan, our risk heatmaps and mitigation playbooks will accelerate action planning and cross‑functional coordination.
We deliberately withhold granular regional and application breakouts, as well as the detailed price curves and per‑supplier revenue splits, from this preview. These items are included in full in the report package and are the precise datasets you will need to execute negotiations, commit to supplier qualification, or structure an acquisition mandate.
For teams focused on 2026, the choice is binary: proceed with ad hoc decisions based on supplier conversations and partial benchmarking, or equip yourself with calibrated models and supplier intelligence that materially reduce execution risk. PW Consulting’s Interface Bridge ICs Market report is built for the latter. Contact our research desk to request access to the full dataset and tailored advisory engagement options.
— PW Consulting, Strategic Industries Practice
For detailed analysis of this topic, please visit the official page: Interface Bridge ICs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com