

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrofluoroether Market to Grow at 6.98% CAGR Through 2032

Hydrofluoroether (HFE) Market: Strategic Imperatives for 2026 Decision-Makers
Executive summary
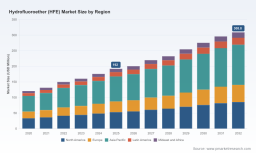
The Hydrofluoroether (HFE) market stands at an inflection point entering 2026. Underpinned by regulatory shifts, material cost dynamics, and a pronounced reshaping of supplier footprints, the sector is forecast to grow at a compound annual growth rate (CAGR) of 6.98% over the 2026–2032 horizon. With a 2025 market base of approximately USD 192.0 Million and a projected market exceeding USD 300 Million by 2032, HFEs are transitioning from niche specialty fluids into a strategically significant component of high-value value chains — notably semiconductors, precision cleaning, and heat-transfer applications.
Hydrofluoroether (HFE) Market
Why this research matters for 2026 strategy
- Actionable foresight: Buyers, producers, and investors face short decision windows in 2026 as capacity expansions and product substitutions accelerate. This research turns macro trends into tactical choices about sourcing, qualification timelines, and contracting.
- Risk triage: Supply-side consolidation, raw-material volatility, and fast-evolving regulatory acceptance of HFEs are compressing lead times and elevating price and availability risks. Strategic risk-mitigation plans must be embedded into procurement and R&D roadmaps now.
- Opportunity mapping: The redistribution of volumes following major exits from legacy suppliers is creating openings for both incumbents and challengers. The report quantifies where and how such openings are most accessible without disclosing client-sensitive segment minutiae.
Market trajectory — what the headline numbers mean
Using 2025 as the base year, the market expanded steadily through the 2020–2025 historical window before entering a rescaling phase driven by regulatory realignment and supplier rebalancing. At a near-7% CAGR over the forecast period, HFEs will continue to outpace many traditional solvent and thermal-fluid markets, reflecting a structural premium for low-global-warming-potential (low-GWP) chemistries in regulated and high-performance applications.
Hydrofluoroether (HFE) Market
For decision-makers, the arithmetic translates into three practical implications:
Hydrofluoroether (HFE) Market
- Qualification and adoption cycles that were previously "nice to have" are now strategic gating items; delayed qualification risks forfeiting share to faster-moving suppliers.
- Capex and capacity decisions made in 2026 will influence supply balance through most of the forecast period, making timing of expansion a lever of competitive advantage.
- Price normalization should be expected as new capacity comes online, but not uniformly — premium, high-purity HFEs tied to semiconductor-grade specifications will retain margin resilience.
Key dynamics reshaping the industry
- Regulatory accelerants: The enforcement of the Kigali Amendment and tightening F-gas frameworks have materially reduced the runway for high-GWP HFCs, accelerating the qualification of HFEs in cleaning and thermal roles. Complementary approvals under programs such as EPA SNAP and select EU pathways continue to lower adoption friction for HFEs in electronics manufacturing.
- Supply-side upheaval: Strategic exits from PFAS portfolios by legacy players have created a multi-hundred-million-dollar annual redistribution opportunity. This has catalyzed rapid capacity decisions among regional and specialty producers, altering supplier selection matrices for OEMs and EMS providers.
- Raw-material pressure: Upstream feedstocks such as acid-grade fluorspar have experienced price and availability stress driven by competing demand (notably EV battery supply chains), contributing to an elevated cost base — analysts observed double-digit percentage increases in recent years. Sourcing strategies and backward integration choices will increasingly determine margin profiles.
- Market concentration: The sector exhibits notable concentration — the top three suppliers account for roughly two-thirds of market share, while the top five approach approximately four-fifths. This structure creates both stability for large-scale buyers and vulnerability to single-supplier disruptions.
Competitive landscape — who matters and why
The competitive map is a mix of diversified multinationals, regional volume players, and niche specialists. Key firms to watch wield different strategic plays:
- 3M — Historically a leading supplier through its Novec engineered fluids, 3M completed its PFAS manufacturing exit in 2025. The exit realigned account relationships across OEMs and contract manufacturers, and has prompted customers to accelerate requalification programs. 3M’s withdrawal is a structural catalyst for supplier switching rather than a temporary market hiccup.
- Solvay — A specialist in engineered and perfluorinated fluids, Solvay remains strategically positioned through product breadth and application know-how targeted at semiconductors, batteries, and high-purity cleaning. Its engineering and customer-services capabilities make it a preferred partner for complex qualification projects.
- Daikin Industries — An integrated fluorochemicals player with strong capabilities in thermal fluids and solvents. Daikin’s vertical integration and global logistics footprint support long-term supply assurances, an important differentiator for large-scale industrial customers.
- AGC Chemicals — Focused on semiconductor and precision electronics spaces, AGC leverages specialized product lines and close relationships with Asian electronics manufacturers, making it a go-to for cleanroom and process-critical applications.
- Kaneko Chemical — Emerging as a tactical supplier of replacement HFEs, Kaneko has been active at trade shows promoting drop-in alternatives, signaling an offensive strategy to capture share vacated by major exits.
- Chinese producers (e.g., Shandong Huaxia Shenzhou, Juhua Group) — High-volume players are scaling export-oriented capacity to meet industrial cleaning and electronics demand. Their competitive advantage rests on cost and scaling speed, though customers rate them variably on high-purity credentials and qualification lead times.
Collectively, these firms illustrate divergent strategic responses: consolidation and premium positioning by large multinationals; niche product development and rapid commercialization by specialized suppliers; and capacity-led market entry by volume-oriented producers.
What the full report delivers (practical, actionable content)
- Scenario-backed demand modeling: Multiple demand scenarios through 2032, with sensitivity to regulatory stringency, raw-material price swings, and supplier capacity trajectories, enabling stress-tested procurement and investment planning.
- Risk heat maps: Supplier, geography, and application-level risk assessments that translate into prioritized mitigation actions (dual-sourcing thresholds, inventory policy changes, and qualification sequencing).
- Competitive playbooks: Comparative analysis of incumbent and challenger strategies, identifying partner archetypes for OEMs, regional distributors, and toll manufacturers.
- Commercial templates: Negotiation and contracting frameworks tailored to HFE supply dynamics — including ramp clauses, quality acceptance criteria, and supply continuity remedies suited to the sector’s concentration profile.
- Technology and adoption roadmaps: Practical timelines for qualification of HFEs across cleaning, heat-transfer, and solvent use cases, aligned with capital-planning cycles for semiconductor fabs and industrial operations.
Strategic implications and recommended actions for 2026
- For buyers (OEMs, contract manufacturers): Initiate a prioritized requalification pipeline now. Focus on securing conditional supply agreements with at least two qualified suppliers for critical grades and incorporate staged inventory drawdown clauses tied to supplier ramp performance.
- For suppliers (incumbents): Differentiate through application engineering services, end-to-end qualification support, and transparent roadmap communications. Where feasible, consider backward integration or long-term resource agreements to insulate margins from raw-material volatility.
- For challengers and regional players: Target narrowly defined "drop-in" replacement opportunities and co-invest in validation programs with customers; commercialization speed and certification support will beat price in many semiconductor-related wins.
- For investors and M&A teams: Prioritize assets that combine technical know-how with customer access in regulated verticals. The current redistribution of volumes creates attractive acquisition and partnership windows, but regulatory tailwinds mean execution risk remains elevated.
Why read the full report
Our study balances quantification with practical counsel: it maps the next seven years of HFE market evolution, translates headline growth into prioritized actions, and provides the operational instruments required to convert strategy into outcomes. We deliberately surface the levers and trade-offs — while reserving detailed proprietary segment datapoints and supplier-commercial matrices for the full report to preserve the integrity of client-grade intelligence and to drive direct engagement.
Next steps
For executives planning 2026 sourcing, investment, or R&D cycles, delaying decisions into H2 2026 will compress optionality. Use the report to lock in qualification timelines, align procurement levers with capex plans, and stress-test supplier arrangements against regulatory scenarios. To access the complete dataset, segmentation breakdowns, and downloadable commercial templates, please consult the full Hydrofluoroether (HFE) Market study — it is the operational companion you need to turn the market’s momentum into a competitive advantage.
For detailed analysis of this topic, please visit the official page: Hydrofluoroether (HFE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com