

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Engine Filter Market to reach USD 344.8 Million by 2032 at 5.5% CAGR

Engine Filter Market 2026: Strategic Signals for Executive Decision-Making
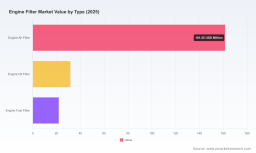
As PW Consulting’s lead industry analyst, I present an executive preview of our comprehensive Engine Filter Market study — an evidence-based briefing tailored to inform the strategic decisions you must make in 2026. The global market for engine filtration has moved from recovery into structural expansion: it rose from roughly USD 160–170 million in 2020 to about USD 215 million in 2025, and our forecasting baseline points toward nearly USD 345 million by 2032, representing a compounded annual growth rate of approximately 5.5% across the forecast window. That trajectory is more than arithmetic; it encodes shifts in regulations, technology, customer economics, and supply-chain risk that will determine winners and laggards over the next three to five years.
Engine Filter Market
Why this research matters for 2026 choices
- Timing of investment: 2026 is a hinge-year. Firms that finalize product roadmaps, allocate capex for filtration-media upgrades, or secure long-term supply agreements in 2026 will enter 2027 with differentiated cost structures and product performance.
- Portfolio prioritization: With steady market growth but rising input volatility, companies must choose whether to prioritize lightweight/high-efficiency air media, oil filtration innovations, or fuel-filtration robustness. Each choice has distinct margin and channel implications.
- M&A and partnership windows: Consolidation pockets are opening at supplier and aftermarket tiers. Our study identifies where bolt-on acquisitions and technology partnerships are likely to accelerate scale and system-level integration.
- Regulatory alignment: Tighter emissions regimes and durability mandates will make filtration a compliance-embedded cost center for OEMs — creating opportunities for suppliers who can demonstrate validated, certified performance improvements.
Core market signals — what the numbers imply
The headline growth rate (≈5.5% CAGR) and the projected near-term uptick reflect multiple, interacting drivers rather than a single demand impulse. On the demand side, stricter emissions and fuel-efficiency targets are expanding the technical requirements for air and oil filtration across both legacy internal combustion platforms and hybrid powertrains. On the supply side, raw material volatility — especially in specialized polymers and synthetic fibers used for filter media — is increasing unit cost uncertainty. The combination produces a market that is growing steadily but that rewards technical differentiation, supplier resilience, and creative commercial models (e.g., subscription-based aftermarket services, performance warranties tied to filter refresh intervals).
Engine Filter Market
Key dynamics shaping 2026 planning
- Material and input risk: Price swings for engineered polymers and nonwoven media are forcing firms to re-evaluate sourcing strategies. Expect near-term hedging, dual-sourcing, and selective backward integration experiments targeting critical media inputs.
- Labor and manufacturing constraints: Labor scarcity and increasing localization of production create a premium for automation investments and modular, scalable manufacturing footprints that can be deployed rapidly to serve OEM contracts.
- Regulatory and environmental pressure: Emissions regulation and public concern about particulate pollution are propelling filtration performance standards — not only for tailpipe compliance but for lifecycle durability. Products that can demonstrably reduce particulate ingress and maintain engine fuel-efficiency will command price resilience.
- Lightweighting and system-level engineering: The drive to reduce vehicle mass and improve fuel economy implicates filter design: lower mass without performance sacrifice is now a strategic product attribute.
- Aftermarket dynamics: Environmental and regulatory drivers are increasing aftermarket replacement demand, while digital diagnostic platforms are enabling smarter aftermarket replacement cycles and value-added services.
Competitive landscape — strategic positioning of leading players
The market exhibits a balance between established filtration specialists and large powertrain/OEM-affiliated suppliers. Our competitive analysis of major participants reveals distinct playbooks worth benchmarking.
Engine Filter Market
- Parker Hannifin Corporation (Baldwin Filters): Positions through high-performance pleat-protection technologies and broad channel-flow/element portfolios. Their advantage lies in industrial-grade contaminant removal designs and channeling aftermarket reach into fleet maintenance networks.
- Mann+Hummel (MANN-FILTER): Competes on engineered air filtration that is calibrated for full service-interval protection and combustion efficiency. The firm’s strength is OEM alignment and validated service-part performance standards.
- Cummins Inc. (Fleetguard): Leverages heavy-duty powertrain knowledge to deliver advanced membrane and cartridge filtration solutions tailored for high-hour engines, where uptime and predictable life cycles are critical for total cost of ownership.
- MAHLE GmbH: Distinguishes itself with aftermarket air filters engineered for extreme particulate capture and sealed designs that address long-tail durability concerns — a compelling proposition for premium and commercial vehicle segments.
- Robert Bosch GmbH: Integrates premium oil and air filtration media technologies with systems thinking — blending natural and synthetic media to achieve efficiency gains and downstream wear prevention.
Across these vendors, the competitive axes are: filtration efficiency vs. cost, system integration capability vs. modular aftermarket offerings, and manufacturing scale vs. niche technical leadership. The market rewards providers that can credibly demonstrate both validated performance improvements and supply-chain reliability.
What PW Consulting’s report delivers — practical, decision-focused content
This study is built for executives who need to move from insight to implementation. Key deliverables include:
- Concise market-sizing and baseline-trend analysis (2020–2025 historical review, 2026–2032 forecast) that anchors strategic assumptions for budget cycles and M&A valuation.
- Scenario modelling that translates input-cost volatility and regulatory tightening into four plausible revenue and margin trajectories — each with trigger points and early-warning indicators.
- Go-to-market playbooks for OEM, fleet, and aftermarket channels: pricing frameworks, warranty constructs, and subscription/service models that preserve margin while accelerating install-base capture.
- Supply-chain stress tests and sourcing blueprints: recommended hedging ratios, candidate geographies for nearshoring, and a supplier scorecard to evaluate media and component partners.
- Technology and innovation roadmaps: media-development priorities, validation protocols, and R&D investment sequencing to meet both emissions and lightweighting goals.
- Competitive benchmarking and M&A heatmap: where scale or technical IP are most valuable, and how to structure deals to extract integration synergies quickly.
- Operational playbooks for manufacturing scale-up and automation: ROI models, capex phasing recommendations, and labor-redeployment plans aligned to demand inflection points.
Note: the report contains detailed segmented tables and granular scenario outputs for type, application, and regional splits — these are intentionally reserved for the full report to preserve analytic value and to enable tailored briefings for decision-makers. The overview here is designed to surface directional insight and strategic implications while directing teams to the full dataset for transaction-level decisions.
Strategic imperatives and recommended actions for 2026
- Short-term (next 12 months): Lock in multi-year supply agreements for critical filter media; commence high-priority automation and quality-control investments; pilot subscription models for high-mileage fleet customers to stabilize aftermarket revenue.
- Medium-term (12–36 months): Invest in lightweight media R&D that demonstrably meets both efficiency and durability targets; negotiate OEM co-development agreements that embed your filters into service schedules; evaluate targeted bolt-on acquisitions to secure media IP or regional distribution footholds.
- Long-term (36+ months): Build integrated system offerings (filter + sensor + service) that monetize lifecycle data; scale modular manufacturing cells near key OEM clusters to reduce logistics costs and improve responsiveness; pursue strategic partnerships with powertrain OEMs to be specified on next-generation engine platforms.
How to use this briefing with your board and investors
Frame 2026 capital requests and strategic initiatives around three testable hypotheses: (1) media-cost volatility will remain a primary driver of margin pressure unless mitigated through sourcing or process innovations; (2) regulatory and environmental demands will increase technical specifications, allowing premiumization for validated performance; (3) lifecycle-service models will unlock higher margin and recurring revenue if supported by diagnostic data and reliable logistics. Our full report includes metrics and decision gates that map these hypotheses into budget asks and KPI dashboards.
Next steps
The high-level signals above are sufficient to start re-prioritizing R&D, procurement, and commercial initiatives for 2026. For teams preparing investment proposals, M&A diligence, or product roadmaps, PW Consulting’s full Engine Filter Market report provides the granular segment forecasts, competitor scorecards, and scenario outputs necessary to finalize decisions and presentations. To obtain the full dataset and a personalized briefing that maps findings to your P&L and strategic timetable, visit the report landing page or contact our industry practice lead for a confidential workshop.
For detailed analysis of this topic, please visit the official page: Engine Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com