

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Swimming Pool Treatment Chemicals Market—USD 1,602.9M by 2032, 4.7% CAGR (2026-32)

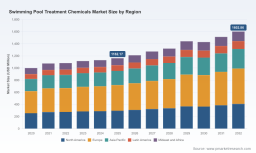
Swimming Pool Treatment Chemicals Market: Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise strategic briefing designed to orient senior executives, corporate strategists, and investment committees as they set priorities for 2026. Our new market study (base year 2025; historical series 2020–2025; forecast period 2026–2032) synthesizes primary research, supplier intelligence, and scenario modelling to translate market movements into actionable corporate choices. At the macro level, the global swimming pool treatment chemicals market expanded from roughly USD 1,000 million in 2020 to about USD 1,162 million in 2025 and is modelled to reach approximately USD 1,603 million by 2032, implying a steady compound annual growth rate of 4.7% across the forecast window. This trajectory frames the decisions companies must make this year: defend margin, secure feedstock, and differentiate product portfolios for sustainability-led demand.
Swimming Pool Treatment Chemicals Market
Why this study matters in 2026
-
Timing and inflection. 2026 is a pivotal year: near-term cost pressures that began in 2024–25 (tariffs, raw material tightness, and vendor-led price moves) are intersecting with longer-term demand growth and product innovation. Companies that act now will either lock in advantaged cost structures or concede margin and share.
Swimming Pool Treatment Chemicals Market -
Predictable, but not uniform, growth. The market’s 4.7% CAGR masks important heterogeneity in growth drivers, margin dynamics, and channel economics. Strategic responses must therefore be surgical—targeted to product families and channels—rather than broad-based.
Swimming Pool Treatment Chemicals Market -
Regulatory and supply shocks are persistent. New tariffs and trade remedies introduced in 2025 created a structural repricing of imported raw materials; in parallel, selective feedstock shortages (for example, observed tightening in cyanuric acid supplies in late 2025) are already producing quarter-over-quarter price volatility. These dynamics increase the value of scenario-planning and hedge strategies that we include in the full study.
Executive summary: High-conviction strategic takeaways
-
Prioritize procurement and inventory strategies. Distributor behavior in 2025–26 (pre-purchasing, extended inventories, and selective price pass-throughs) has created both risk and opportunity for manufacturers and retailers. Companies that combine dynamic pricing, frictionless order fulfilment and measured inventory accumulation can protect margin while avoiding stockouts.
-
Differentiate on chemistry and sustainability. Product launches in 2025—most notably biodegradable formulations and efficiency-optimizing platforms—signal a buyer shift toward low-environmental-impact offerings. This is an R&D, branding and go-to-market imperative: marginally higher formulation costs can be justified if supported by clear consumer benefit and channel placement.
-
De-risk feedstock exposure. Tariffs and trade rulings enacted in 2025 have reallocated sourcing economics. Firms should stress-test contracts against tariff and input-price scenarios, establish near-shore or multi-sourcing options, and consider longer-term vertical integration where scale permits.
-
Use distribution as a strategic asset. Global and regional distributors that control logistics and SKU assortment hold leverage. Strategic partnerships, exclusive formulations and data-sharing agreements with distributors will be decisive for rapid market access and category control.
-
M&A and portfolio pruning are on the table. Moderate market concentration metrics in our analysis indicate room for consolidation that creates scale benefits without triggering excessive anti-trust friction. M&A targets will often be regional formulators with unique chemistries or distribution-led assets that bring complementary channel reach.
Competitive landscape: how the leading firms are positioning
The report includes a granular competitive assessment of the full incumbent and challenger set. Below are synthesis-level observations on the strategic posture of core players and the tactical moves that matter to competitors and investors:
-
Clorox Company — consumer-brand R&D and sustainability. Clorox leverages consumer trust and broad retail reach. Its 2025 launch of biodegradable pool chemicals signals a deliberate pivot to capture sustainability-led premiumization among homeowners and retail partners. Strategy: expand shelf-ready SKUs, invest in brand education and secure premium placement in retail assortments.
-
Pool Corporation — distribution & margin management. PoolCorp’s 2025 inventory growth and early-2026 commentary on pricing illustrate a distributor-led response to vendor cost increases: pre-buying to offset supplier price hikes and opportunistic pricing. Strategy: manufacturers should view PoolCorp both as a customer and a competitive barometer—collaborate on promotions, rebates, and joint inventory planning.
-
BASF SE — formulation efficiency and B2B innovation. BASF’s 2025 platform for optimizing chlorine efficiency highlights the technological frontier: small formulation gains can materially reduce customer dosing and total cost of ownership. Strategy: pursue co-development agreements with pool operators and commercial customers to prove dose efficiency and lock in enterprise contracts.
-
Specialist manufacturers (BioLab, Haviland, Robelle, ICL, Solvay, Lonza, Olin, Westlake) — focused value propositions. These firms compete on formulation expertise, feedstock integration and regional distribution relationships. Strategy: niche companies should double down on channel exclusives and guard formulation IP while exploring bolt-on acquisitions to widen portfolios.
Recent developments that change the playbook
-
Distributor inventory dynamics: Pool Corporation reported elevated inventories through 2025 driven by pre-purchasing ahead of vendor price increases and has signalled modest pricing benefits in early 2026 as a result of mid-season pricing actions. Expect distributors to continue to use inventory and pricing levers to manage margins in the near term.
-
Product innovation: Notable 2025 product introductions include biodegradable chemistries and formulation platforms that improve chlorine efficiency. These innovations change procurement conversations: buyers will trade up for demonstrable operational savings and environmental credentials.
-
Tariffs and trade measures: A series of tariff actions and trade rulings in 2025 have reweighted the economics of imports for key feedstocks. Companies that delayed localization or dual-sourcing strategies are now exposed to outsized input-cost shocks.
-
Feedstock volatility: Tightening in cyanuric acid markets in late 2025 produced measurable quarter-on-quarter price movement—an indicator that even relatively small shifts in specialty chemical availability can ripple through pool chemical formulations and retail pricing.
What the full PW Consulting study contains (practical, decision-ready content)
We deliberately keep this briefing high-level to protect the commercial value of the detailed analysis. The full report—designed for direct use in board and C-suite planning—includes:
-
Top-down and bottoms-up market sizing (2020–2032) with reconciled data sources and sensitivity tables.
-
Segment-level forecasts by product family and end-use application, plus premium and discount scenarios (note: segment-level figures are reserved for the full report).
-
Supplier and distributor scorecards with capability matrices, margin waterfall models, and CR3/CR5 concentration analysis to support M&A and partnership screening.
-
Raw-material stress tests and tariff-impact simulations with recommended procurement and hedging strategies.
-
Commercial playbooks for manufacturers, distributors and retailers—pricing levers, SKU rationalization, trade promotion optimisation and digital retailing strategies.
-
M&A pipeline and valuation comparables, including an actionable shortlist of targets for scale, formulation IP and channel expansion.
-
Executive dashboards—ready-to-use slides and scenario tables for your 2026 planning session.
How to use these insights in a 90-day planning cycle
-
First 30 days: Run a procurement stress-test—map your top five feedstock exposures, run the tariff scenarios we provide, and negotiate supply commitments or dual-sourcing clauses to cap downside.
-
Days 30–60: Revisit your product portfolio. Use our value-mapping tool to identify SKUs that should be prioritized for sustainable reformulation, price promotion, or retirement. Align sales incentives with high-margin, high-differentiation products.
-
Days 60–90: Engage distribution partners with a joint action plan. Propose pilot programs for inventory optimization, co-branded sustainable lines, or exclusive assortments. Simultaneously assess M&A targets short-listed in the report.
Final note: the “trailer” approach
This briefing showcases the strategic depth and immediate applicability of our market study while intentionally withholding granular segment and supplier-level figures to preserve the report’s decision-making value. If your 2026 plan depends on precise product-family forecasts, country-level pricing curves, or supplier margin decompositions, PW Consulting can provide the full dataset, modeling files, and a short advisory engagement to translate analysis into executable plans.
Next steps
-
Access the full study to obtain the detailed segmentation, supplier scorecards, scenario models and executive dashboards that support urgent 2026 decisions. PW Consulting also offers rapid workshops (2–4 weeks) to tailor the study outputs to your portfolio and to co-create go-to-market or M&A plans.
For detailed analysis of this topic, please visit the official page: Swimming Pool Treatment Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com