

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Food & Beverage Metal Cans Market to Reach USD 581.0M by 2032 at 7.3% CAGR

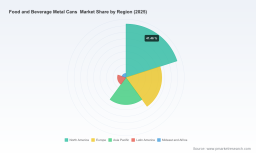
Food and Beverage Metal Cans Market: Strategic Preview for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a concise, high-impact introduction to our new Food and Beverage Metal Cans Market study. This preview is built to support executive decision‑making through 2026 by laying out the macro trajectory, key market dynamics, competitive posture, and the practical levers that will determine winners and laggards in the coming investment cycle. Think of this piece as a cinematic trailer: it demonstrates the depth and utility of our analysis while selectively withholding the granular segmentation that resides in the full report.
Food and Beverage Metal Cans Market
Why this study matters for 2026
The metal cans market for food and beverage is transitioning from defensive cost management to offensive market capture. Our analysis shows the market’s recent base-year size (2025) and a multi-year recovery and growth arc driven by shifting consumer preferences, sustainability mandates, and supply‑side investment. Under a 7.3% compound annual growth rate through our forecast window, the market is modeled to expand materially from the 2025 base toward the end‑of‑horizon value in 2032 — a trajectory that transforms the shape of strategic options available to manufacturers, converters, brand owners, and investors entering 2026.
Food and Beverage Metal Cans Market
For corporate leaders planning 12–36 month moves, the implications are immediate: capital allocation, sourcing strategy, capacity timing and placement, and sustainability investments must be choreographed against a market expanding at mid‑single‑digit CAGR with episodic raw‑material and regulatory shocks. Our report is designed to convert those implications into executable decisions and measurable KPIs.
Food and Beverage Metal Cans Market
Macroeconomic and structural takeaways
- Market momentum: After a period of volatility in the early 2020s, demand stabilizes at the 2025 base and resumes a steady growth path through the forecast. That baseline is the point from which strategic investment analyses and scenario planning should be constructed for 2026 decisions.
- Concentration and competition: The sector shows a high degree of concentration among a small group of global leaders. Our market-concentration metrics indicate a substantial portion of supply is controlled by top-tier firms, creating both barriers and strategic openings for challengers with focused regional or technical advantages.
- Cost pressure dynamics: Recent policy and commodity moves have reintroduced raw‑material volatility into cost models — most notably through tariffs and rapid aluminum price movement in early 2026. These forces are reshaping procurement, hedging, and pricing strategies.
- Regulatory and safety trends: Product‑level compliance (including migration toward BPA‑non‑intent linings) and recycling targets are moving from optional to table stakes. Brands and suppliers who accelerate compliance while preserving cost competitiveness will win shelf‑space and public trust.
What the full report contains (practical, transaction‑ready content)
This study was built for pragmatic use by strategy teams, procurement, M&A groups, and plant operations heads. Its content is organized into modules that transition from diagnosis to execution:
- Market framework and methodology: transparent assumptions, scenario templates, and sensitivity tools you can apply to internal models.
- Demand and supply mapping: end‑market drivers, consumption models, and a granular supplier/capacity matrix (note: detailed regional and application splits are exclusively available in the full report).
- Cost and margin analytics: input‑cost pass‑through models, aluminum/steel price impact scenarios, and producer margin decomposition for different product architectures.
- Sustainability and regulatory playbook: compliance timelines, recycling economics, and product redesign roadmap with estimated payback windows for lightweighting and liner innovation.
- Competitive landscaping and benchmark profiles: strategic positioning, capacity footprints, recent investment activity, and capability heatmaps for leading suppliers.
- M&A and partnership compass: deal precedents, valuation drivers, integration risk checklist, and target selection framework for bolt‑on and scale plays.
- Commercial and go‑to‑market tools: account segmentation frameworks, channel economics, pricing playbooks, and SKU rationalization templates to accelerate margin capture.
- Operational playbook: line‑level productivity benchmarks, capex sequencing models, and workforce transition plans for new lines and technologies.
Competitive landscape — forces shaping the top tier
The competitive field is characterized by several global incumbents with differentiated strengths. Our full profiles synthesize publicly reported moves, strategic positioning, technology strengths, and short‑to‑medium‑term expansion plans for each major participant.
- Global sustainability and scale leaders emphasize aluminum lightweighting, high recycling content, and custom formats to capture beverage growth. Their strategic playbooks pair R&D with consumer packaging partnerships to protect share while enabling premium pricing.
- Producers with deep steel capabilities and heritage food can competencies are optimizing for shelf stability and can‑end reliability, targeting legacy food customers where structural margins are defended by switching costs and regulatory approval pathways.
- Regional champions and trusted converters are leveraging lower local cost bases, proximity to beverage and food clusters, and service speed to win incremental contract volumes from multinational brand programs expanding into new territories.
Notable recent developments that frame the near‑term competitive environment include capacity investments and facility expansions by major players, targeted earnings outperformance from efficient operators, and industry‑wide recycling initiatives that are both reputation and demand drivers. These developments are catalysts for supply rebalancing and pricing normalization in select corridors.
Dynamics and headwinds to 2026
- Tariff and trade friction: Industry participants have reported elevated cost impacts from tariff regimes, prompting immediate procurement strategies and medium‑term lobbying and supply‑chain reconfiguration. Firms must decide whether to accept margin compression, pass costs to customers, or reposition production footprints.
- Aluminum price volatility: Rapid price movement in the first half of 2026 underscores the need for dynamic hedging and flexible procurement contracts. Firms without active commodity hedges or purchase options risk margin erosion.
- Regulatory safety norms: Adoption of BPA‑non‑intent linings is nearly universal in developed markets — a compliance baseline that raises technological and cost expectations for suppliers and reinforces the role of trusted manufacturing partners.
- Sustainability as competitive currency: Recycling drives and circular‑economy metrics are increasingly material to brand value and purchase decisions. Producers with demonstrable closed‑loop programs and transparent CO2 accounting will unlock differentiated commercial terms.
Strategic actions for decision makers in 2026
Based on our integrated market model and client engagements, we recommend a set of prioritized actions for companies taking decisive steps this year:
- Reframe capital plans through scenario lenses — commit to flexible, modular capex that can be ramped or mothballed based on three‑to‑six month demand probes. Avoid single‑point capacity bets without validated offtake agreements.
- Rearchitect procurement: diversify alloy supply, layer long‑term and spot exposure, and build strategic partnerships with upstream refiners to mitigate tariff and price volatility.
- Accelerate sustainability investments that generate commercial benefit — e.g., lightweighting with immediate cost offsets, or certified recycled content that supports premium placement and retailer scorecards.
- Use M&A defensively and offensively — consider bolt‑ons that fill geographic gaps, strengthen technical capabilities (liner/bonding technology), or provide immediate scale in high‑growth beverage segments.
- Deploy pricing governance: develop index‑linked clauses and transparent pass‑through mechanisms that protect margins while maintaining commercial defensibility with brand partners.
- Institutionalize scenario planning and rapid decision protocols — in a market where commodity and policy shocks recur, governance speed is a competitive advantage.
How PW Consulting’s deliverables accelerate execution
Clients using this report receive a toolkit that converts analysis into action: configurable financial models, commercial negotiation playbooks, capex sequencing charts, and a short‑list of acquisition targets and partner profiles. We map each strategic recommendation to KPIs you can track across 6, 12 and 24 months — from EBITDA bridge scenarios to fill‑rate improvements and sustainability milestones.
Importantly, the full market study contains the granular regional and application splits, unit‑level economics, and product‑type elasticity matrices that are intentionally withheld from this preview. Those datasets are the operational intelligence you need to size investments, renegotiate supply contracts, and model acquisition candidate synergies with precision.
Final note — decision timing and next steps
For boards, CFOs, and commercial leaders planning 2026 actions, timing is now a strategic input. The combination of market growth, concentrated supply, and episodic raw‑material shocks means the next 12 months will present windows for advantaged capacity entry, defensive consolidation, and contractual resets. Our full report is designed to reduce the execution risk for those moves by providing the segment‑level economics and actionable playbooks that this preview intentionally omits.
To access the complete intelligence pack — including the detailed regional and application breakdowns, supplier scorecards, and the transaction playbook — please visit our report landing page or contact PW Consulting’s metal packaging practice. This preview establishes the strategic frame; the full study furnishes the precision instruments you will use to act.
For detailed analysis of this topic, please visit the official page: Food and Beverage Metal Cans Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com