

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: CBE Market to Hit USD 2,080.79M by 2032 at 5.5% CAGR

Cocoa Butter Equivalent (CBE) Market — Strategic Preview for 2026 Decisions
As organizations enter 2026, the Cocoa Butter Equivalent (CBE) market is transitioning from cyclical volatility to structurally higher strategic importance within confectionery and adjacent ingredient value chains. PW Consulting’s latest market study (base year 2025) synthesizes macro trajectories, supplier capability mapping, regulatory pressure tests and commercial playbooks that senior leaders will need to navigate uneven cocoa markets, sustainability mandates and evolving formulation windows.
Cocoa Butter Equivalent (CBE) Market
Why this study matters for 2026
-
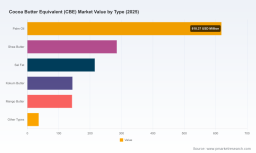
A clear macro growth trajectory: The global CBE market expands from a 2025 base of USD 1,441.2 Million and, at a CAGR of 5.5% through our 2026–2032 forecast period, approaches a materially larger market by 2032. That trajectory signals both rising demand elasticity for alternative fats and an expanding addressable market for specialty and sustainable CBE grades.
Cocoa Butter Equivalent (CBE) Market -
Concentration creates leverage points: Market concentration metrics (CR3 ~45.2%, CR5 ~58.1%) indicate meaningful scale advantages for a small set of integrated suppliers, but also leave room for mid-sized specialists and differentiated entrants to capture premium niches—especially where sustainability, traceability and non-lauric/low-trans variability matter.
Cocoa Butter Equivalent (CBE) Market -
Regulatory guardrails and reformulation constraints: Existing legislative frameworks — including provisions embedded in the EU's chocolate standards — continue to define permissible substitution ceilings and disclosure requirements. These rules, combined with growing allowances for compliant formulations, shape viable commercialization pathways for higher-substitution CBE products.
-
Risk-accelerators in supply and pricing: Recent commodity dynamics (e.g., firm palm stearin pricing into Q1 2026 and persistent cocoa origin uncertainty) are already shortening procurement lead times and accelerating manufacturer interest in formulation hedges and blended CBE strategies.
What PW Consulting’s preview reveals (and intentionally withholds)
This article is designed as a strategic “trailer”: it surfaces the analytical framing, high-level findings and decision-useful levers while intentionally reserving detailed split-level datapacks and proprietary scenarios for the full report. You will see the market scale and growth direction here; the full competitive maps, regional and application-level share tables, and price-elasticity matrices are accessible only in the complete deliverable.
-
Included here: high-level market sizing, expected trajectories, industry dynamics, competitive archetypes, and actionable strategic options for 2026.
-
Reserved for the full report: granular regional and application breakdowns, supplier-level pricing curves, formulation performance matrices, and downloadable vendor diligence templates.
Key industry dynamics shaping 2026 decisions
-
Supply tightness and raw material pressure. Palm stearin markets showed firm upward trends through Q1 2026 driven by origin tightness and recovering downstream demand. Procurement teams must assume higher baseline cost curves and model hedging vs. reformulation trade-offs accordingly.
-
Cocoa volatility as a catalyst. Ongoing West African cocoa sourcing uncertainty has intensified reformulation incentives across confectionery manufacturers—raising the strategic value of proven CBE solutions that deliver consistent melting, snap and mouthfeel properties.
-
Sustainability and traceability are non-negotiable. Buyers and brand teams are elevating requirements for zero-deforestation sourcing, smallholder engagement credibility and third-party traceability. Suppliers with audited supply chains and verifiable smallholder programs command access to premium customers and longer contract tenors.
-
Regulatory nuance matters. While established chocolate standards set substitution ceilings, regulatory pathways and permissible formulation schemas allow innovation where local cocoa butter and dry cocoa solids criteria are met—opening windows for technically compliant, higher-inclusion CBE formulations in targeted markets.
Competitive landscape — archetypes and tactical implications
The CBE field is populated by vertically integrated agribusinesses, specialty fats processors, and regional refiners. Each archetype presents distinct strategic trade-offs for buyers and investors.
-
Global integrators (scale + integration). Large, integrated players leverage feedstock integration, broad product portfolios and sustainability programs to offer reliability under stress. Their advantage is supply continuity and bundled services—useful for multinational confectioners prioritizing continuity over marginal cost improvements.
-
Specialty fats leaders (product performance). Firms focused on exotic fats and premium shea/palm blends win in high-substitution and premium confectionery where mouthfeel and processing window fidelity are critical. These suppliers are often the first choice for reformulation projects requiring tight thermal behavior and enrobing performance.
-
Regional refineries and challengers. Mid-sized producers and regionally anchored refiners can be agile on commercial terms and quicker to co-develop bespoke grades. They often partner with brands seeking differentiated sustainability narratives tied to origin and community impact.
Representative companies covered in our analysis include a mix of these archetypes—whose recent moves highlight where priorities are shifting:
-
AAK AB (Malmö, Sweden): Investing in enrobing-grade CBE solutions designed for higher-substitution formulations—an explicit response to cocoa price pressure and customer reformulation demand.
-
Bunge Limited (White Plains, NY): Positioning premium shea-based CBEs for branded and premium confectionery use-cases.
-
Wilmar International and Musim Mas (Singapore): Leveraging specialty fat platforms and smallholder sustainability partnerships to secure feedstock and compliance credentials.
-
Manorama Industries (India) and FGV IFFCO (Malaysia): Expanding refining capacity and promoting premium non-lauric, trans-free grades—signaling supply-side responses to rising confectionery demand.
-
Olam and Cargill: Emphasizing sustainable, integrated supply options that pair CBE availability with broader chocolate and ingredient ecosystems.
Recent developer actions and their strategic read-across
-
New product launches focused on higher-substitution enrobing grades indicate a manufacturer preference for turnkey formulations that minimize process disruption during reformulation.
-
Capacity expansions in shea and exotic fat refining point to anticipated demand not just for volume, but for specialty differentiation tied to provenance and sustainability narratives.
-
Partnership renewals and joint ventures emphasize two simultaneous priorities: securing high-purity feedstock and amplifying credible smallholder sustainability pathways.
Actionable frameworks for 2026 decision-makers
Below are pragmatic levers and decision frameworks that the full PW Consulting study operationalizes. Each is accompanied in the full report by templates, scoring rubrics and scenario-model inputs.
-
Procurement playbook: A three-horizon approach—stabilize (short-term hedges and contract clauses), optimize (blend portfolios and dual-sourcing), transform (vertical partnerships and strategic equity in feedstock).
-
Formulation matrix: A decision tree balancing organoleptic tolerance, manufacturing constraints (e.g., conching and enrobing windows) and regulatory envelopes—used to determine candidate CBE grades and substitution ceilings for pilot programs.
-
M&A and partnership screen: A weighted scorecard that prioritizes supply security, sustainability credentials, technical IP and geographic diversification—useful for rapid target triage in an active consolidation cycle.
-
Sustainability roadmap: Staged investments in traceability, verification (RSPO, third-party audits), and farmer engagement programs—each mapped to expected margin and contract length outcomes.
-
Risk scenario engine: Commodity shocks, regulatory tightening, and geopolitical supply disruptions are stress-tested against P&L and service-level KPIs to establish contingency triggers for switching suppliers or accelerating reformulation.
How companies should prioritize in 2026
-
Consumer brands: Fast-track pilot programs for higher-inclusion formulations where permissible, tied to consumer sensory testing and transparent labelling to avoid reputational friction.
-
Ingredient suppliers: Invest selectively in traceability and premium specialty grades while building scale in cost-competitive feedstocks to defend against margin compression.
-
Private equity and investors: Look for targets with defensible technical IP, sustainable sourcing premium, and repeatable commercial contracts—the combination that re-rates multiples in consolidation cycles.
What you will find in the full PW Consulting report
-
Detailed market model (2020–2032) with scenario outputs and sensitivity analyses for raw material cost, substitution rates and regional demand shifts.
-
Granular competitor dossiers and a supplier capability matrix with technical performance, capacity overlays, and sustainability scoring.
-
Regulatory mapping by jurisdiction and practical compliance playbooks for higher-inclusion formulations.
-
Commercial negotiation templates, sample RFP language, and a formulation-ready laboratory checklist for industrial-scale pilots.
-
M&A and investment due-diligence checklists tuned to CBE-specific operational and sustainability risks.
For executives making 2026 capital, sourcing or R&D decisions, the PW Consulting CBE study is designed to convert market complexity into a prioritized set of near-term actions and multi-year strategic bets. Our public preview has shared the market arc, competitive themes and pragmatic frameworks—while the full analysis contains the granular inputs, segmented demand matrices and vendor-level pricing models necessary to operationalize these recommendations.
Next steps
Clients seeking to integrate these insights into 2026 planning cycles should define one of three engagement scopes with PW Consulting: a 4–6 week rapid procurement and formulation playbook; a 10–12 week commercial and M&A diligence program; or a bespoke transformation roadmap combining technical co-development with supply-chain investments. The complete report and interactive datasets provide the drill-down detail required to implement any of these options.
Contact PW Consulting to obtain the full CBE market study and the accompanying data pack for execution-ready insights.
For detailed analysis of this topic, please visit the official page: Cocoa Butter Equivalent (CBE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com