

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Office Furniture Market Poised for 7% CAGR Through 2032

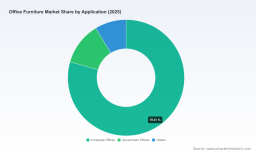
Office Furniture Market: 2026 Strategic Outlook and Action Playbook
As organizations reconfigure workplaces for hybrid productivity, sustainability and wellbeing, the office furniture market is shifting from a commoditized supply chain to a strategic enabler of workplace transformation. PW Consulting’s latest market study — anchored on a 2025 base year with a historical window covering 2020–2025 and a forecast horizon through 2032 — synthesizes market-scale dynamics, supplier positioning and regulatory headwinds to equip executives with decision-grade intelligence. At the macro level, the global market expands at a compound annual growth rate (CAGR) of 7.0%, rising from a mid‑tens-of-billions baseline in 2025 and projected to exceed one hundred billion USD by the early 2030s. This report is designed to inform capital allocation, sourcing strategy, product roadmaps and M&A decisions across 2026 and beyond.
Office Furniture Market
Why this study matters for 2026 decisions
-
Timing: 2026 is a breakpoint year. Organizations are moving beyond pilot hybrid models to multi-year workplace strategies; procurement cycles shifting now will lock in vendor relationships and capital investments for the next 3–7 years.
Office Furniture Market -
Scale and velocity: The market’s steady growth trajectory (7.0% CAGR over the forecast window) means both predictable demand and attractive runway for players that can differentiate on design, sustainability and service economics.
Office Furniture Market -
Complex risk overlay: Trade policy changes, raw material volatility and labor cost inflation are converging. Our report translates these dynamics into scenario-adjusted cost impacts and procurement playbooks to preserve margin and delivery certainty.
-
Competitive positioning: The sector shows meaningful concentration among leading global vendors. Understanding where incumbents deploy capital, product innovation and distribution is critical to designing effective competitive responses or partnership strategies.
Snapshot — what the numbers mean
The report places hard market-scale data at the center of strategy. After a recovery-and-consolidation phase through 2024–2025, the sector projects robust expansion in absolute market size through 2032. That trajectory underpins three strategic realities for leaders in 2026: (1) demand is large enough to support premiumization and service-led business models, (2) growth is sufficiently broad-based to justify targeted geographic and vertical playbooks, and (3) sustained expansion enables larger players to accelerate consolidation while providing nimble challengers space to specialize.
Key market dynamics shaping 2026
-
Workplace architecture and service models: Buyers are prioritizing modularity, ergonomic health, and technology integration. The migration to subscription and managed workplace services (Workplace-as-a-Service) is accelerating, changing total cost of ownership math and after-sales revenue potential.
-
Sustainability and circularity: Procurement teams increasingly evaluate lifecycle impact and end-of-life recovery. Demand for recyclable materials, take-back programs and certified supply chains is becoming a procurement prerequisite rather than a differentiator.
-
Supply-chain and input-cost pressures: Steel, copper and other commodity inputs remain primary cost drivers for manufacturers and fit‑out contractors. Added to this are tariffs introduced through 2025–2026 — including retained Section 232 duties and new lumber/furniture import levies — which materially affect landed cost and supplier selection strategies.
-
Labor and project delivery: Labor shortages and rising labor costs in key markets continue to inflate fit‑out budgets and extend project timelines. Companies that embed prefabrication strategies, modular install teams and digital coordination reduce schedule risk and protect margin.
-
Standards and compliance: Regulatory updates — such as the IRS’s revised Workspace Furniture and Equipment guidance effective mid‑2025 — alter tax treatment and compliance responsibilities for employers and contractors. Our report maps these changes to procurement checklists and capital planning templates.
-
Industry signals: The active calendar of trade shows and standards forums (e.g., Furniture Contract Expo 2025, BIFMA 360 in February 2026, and Furniture Manufacturing Expo in mid‑2026) points to renewed product innovation and channel activity entering 2026, delivering vendor roadmaps and partnership opportunities.
Competitive landscape — who matters and why
The market displays moderate concentration: the top three players account for a material share of global revenues, and the top five command a clear majority position. This structure creates a two-track competitive environment—large incumbents that compete on integrated systems, scale manufacturing and contract channels, and flexible challengers that compete on design differentiation, speed-to-market and pricing.
-
Steelcase Inc. (Grand Rapids, Michigan): Globally scaled designer and manufacturer with deep capabilities in ergonomic seating, systems and workplace strategy services. Strengths include channel reach in corporate and contract markets and ongoing investments in sustainability and circular business models.
-
Herman Miller, Inc. (Zeeland, Michigan): Leader in design-centric, ergonomics-focused product lines with strong brand equity and growing services around workplace strategy and interiors. Notable for premium positioning and sustainability credentials.
-
Knoll, Inc. (East Greenville, Pennsylvania): Premium modern design ethos, focused on architect and designer channels. Competitive advantages include integrated furniture systems and a strong presence in creative and tech-oriented workspaces.
-
HNI Corporation (Muscatine, Iowa): Multi-brand manufacturer with broad product portfolio spanning seating, storage and workstations, and established institutional and commercial channels. Scale manufacturing and portfolio breadth are key differentiators.
For buyers and investors, the practical implication is clear: incumbents will continue to consolidate access to large corporate contracts and enterprise services, while mid-sized and emerging vendors will find runway by specializing in sustainability, rapid customization, and regional manufacturing footprints to mitigate tariff exposure.
What PW Consulting’s report delivers — the playbook components
This study is intentionally practical. It combines forward-looking market sizing with templates, models and case studies to support rapid execution:
-
Demand forecasts and scenario maps covering 2026–2032, with sensitivity to occupancy rates, capex cycles and service adoption.
-
Supplier benchmarking and capability matrices that evaluate manufacturing scale, innovation pipeline, channel strength and sustainability credentials.
-
Procurement playbooks including RFP templates, TCO calculators (capital + service models), and risk mitigation checklists addressing tariffs and commodity volatility.
-
Product and go‑to‑market blueprints for premiumization, modularization and subscription services, complete with price-positioning guidelines and channel activation models.
-
Operational guidance for manufacturing and fit-out partners on prefabrication, labor strategies and digital project coordination to compress timelines and control costs.
-
Regulatory and compliance annexes mapping IRS guidance, tariff schedules and standards activity (BIFMA developments), translated into procurement and accounting implications.
-
Executive dashboards and appendices: methodology notes, data tables and the underlying market model (interactive versions available online for subscribers).
Strategic moves for 2026 — recommended priorities
-
Reassess sourcing geography now: With new tariffs and persistent commodity pressure, nearshoring and regionally diversified manufacturing reduce landed-cost exposure and delivery lead times. The report provides supplier selection algorithms to operationalize this trade-off.
-
Embed services into offers: Convert one-time sales into recurring revenue through managed workplace services, refurbishment and furniture-as-a-service options — improving lifetime value and client stickiness.
-
Invest in modularity and prefabrication: Reducing on-site labor requirements mitigates labor-cost risk and shortens project schedules. Our case studies quantify the margin uplift from these investments.
-
Prioritize sustainability as a procurement filter: Lifecycle claims, take-back programs and certified materials are increasingly non-negotiable for enterprise buyers; integrating these into product roadmaps preserves contract access.
-
Prepare tariff and commodity hedging playbooks: The report includes scenario-adjusted P&L impacts and recommended contractual protections (indexation clauses, multi-sourcing) to shelter margin.
-
Use standards and events as intelligence sources: Vendor roadmaps unveiled at industry trade shows and standards forums often signal where design and specification decisions will migrate — leverage these windows for timely product updates or partnership moves.
How to use this study in board-level planning
Boards and executive teams can use the report as the backbone for strategic planning cycles in 2026 by:
-
Running 3‑way scenarios (conservative, base, upside) against the report’s demand model to stress-test capex and procurement pipelines;
-
Applying the supplier benchmark to shortlist candidates for strategic partnerships or M&A targets, prioritizing capabilities that close current capability gaps;
-
Deploying the procurement playbook to renegotiate long-term contracts with indexed pricing and delivery protections; and
-
Allocating R&D and product investment to areas quantified in the study as having the highest value capture (e.g., ergonomic tech integration, circular product lines, and managed services).
PW Consulting’s study is deliberately thorough in its macro and operational analysis while remaining compact and execution-focused. To honor the “trailer” principle and preserve the commercial integrity of the research, this introduction highlights the analytical approach and executive value without reproducing the report’s full segmentation tables and granular regional/application breakdowns. Those detailed datasets, interactive dashboards and supplier scorecards are available on the report landing page and are essential for transaction-level decisions and model recalibration.
Next steps
If your 2026 agenda includes RFPs, vendor consolidation, capital allocation to workplace transformation, or exploring subscription-based revenue models, this report provides the analytical backbone and practical tools to move from strategy to execution. Access the full dataset and interactive models on the PW Consulting report page to unlock the complete segmentation tables, regional and application-level forecasts, and detailed supplier benchmarks that underpin the recommendations in this briefing.
For detailed analysis of this topic, please visit the official page: Office Furniture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com