

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Human Fibrinogen Market to Hit USD 316.93 Million by 2032 at 5.7% CAGR — PW Consulting

Human Fibrinogen Market: A Strategic Preview for 2026 Decision-Makers
As health systems and biopharma leaders refine portfolios and capital allocation plans for 2026, the human fibrinogen market has moved from a niche therapeutic category to a strategically significant segment within hemostasis and perioperative care. This preview synthesizes the macro trajectory, regulatory inflection points, supply-chain realities and competitive dynamics you need to factor into short‑ and medium‑term decisions. It demonstrates the kind of analytic depth PW Consulting deploys across our full report while reserving the granular proprietary splits and model outputs for subscribers and clients.
Human Fibrinogen Market
Macro trajectory and what it means for strategy
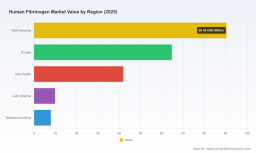
Our base-year sizing (2025) places the global human fibrinogen market at approximately USD 215 million, up from roughly USD 163 million in 2020. At a compound annual growth rate (CAGR) of 5.7% over the forecast window beginning 2026, the market is projected to expand meaningfully through 2032. This steady expansion reflects a combination of broadened clinical indications, product presentation innovations, and incremental adoption across surgical and emergency care pathways.
Human Fibrinogen Market
For corporate strategists, the implications are straightforward: the market is large enough to justify dedicated commercial and manufacturing investment, but concentrated enough (CR3 ~62%, CR5 ~75%) that scale, regulatory footprint and supply reliability materially determine competitive positioning. In other words, the winners will be those who can combine regulatory foresight, supply resilience and targeted commercialization to capture disproportionate share.
Human Fibrinogen Market
Why 2026 is a turning point
-
Regulatory expansion and label dynamics — Recent regulatory actions have broadened permissible uses of fibrinogen concentrates beyond congenital deficiency into acquired fibrinopenia scenarios, notably in perioperative and trauma contexts. These approvals materially enlarge addressable use cases and shift the value proposition from a rare-disease replacement therapy to a perioperative haemostasis tool.
-
Reimbursement clarity — Coding and payment developments (for example HCPCS J7179 assignment and Medicare/Medicaid schedule updates effective for CY 2025) create clearer commercial pathways in the U.S. Market-access teams must translate these coding windows into hospital reimbursement strategies to unlock inpatient adoption.
-
Product and presentation innovation — New presentations that simplify reconstitution and administration are reducing friction at the point of care, improving uptake in fast-paced surgical and trauma settings. Expect product usability to be a near-term differentiator, particularly where hospitals prioritize time-to-hemostasis.
-
Supply-side constraints — Plasma-derived fibrinogen concentrates remain dependent on regulated plasma collection and fractionation processes, which involve multi-month timelines from donor to finished product. The typical 7–12 month lead-times for plasma collection and fractionation introduce supply-risk considerations that should drive strategic decisions around inventory, contract manufacturing and vertical integration.
What PW Consulting’s report delivers (practical, transaction-ready outputs)
-
Market sizing and scenarios — Base-year market maps and three forward-looking scenarios (conservative, base, accelerated) with transparent assumptions and sensitivity runs keyed to clinical adoption, reimbursement policy shifts, and new approvals.
-
Commercial playbook — Evidence-generation templates, hospital procurement negotiation frameworks, and P&L impact models that translate unit adoption into realistic revenue and EBITDA outcomes under different contracting environments.
-
Supply-chain risk matrix — Detailed mapping from donor sourcing to finished dose including lead times, single-point-of-failure analysis, and mitigation options (dual-sourcing, buffer stock sizing, toll-fractionation contracts).
-
Regulatory and reimbursement tracker — Country- and region-specific milestones, coding opportunities and payer positioning playbooks designed to accelerate launch adoption and minimize coverage timelines.
-
Competitive landscaping and M&A heatmap — Company profiles, capability gaps, and acquisition targets prioritized by strategic fit (manufacturing, geographic access, clinical pipeline).
Note: This preview intentionally omits our proprietary micro-splits (regional & application-level breakouts and the underlying financial model) to protect analytic IP. Those datasets and model access are available through our full report and advisory engagements.
Competitive dynamics: what recent moves tell us
The fibrinogen market is shaped by an established set of plasma-derivative incumbents and a rising set of differentiated entrants. Key players we profile in the full study include CSL Behring, Octapharma, Shanghai RAAS, LFB Group and more recently Biotest. Recent developments underscore changing competitive levers:
-
Regulatory-driven reshuffling: Biotest’s recent approvals in Europe and the U.S. for a fibrinogen concentrate (late 2025 approvals and U.S. authorization in December 2025) reconfigure competitive supply options in core markets and increase available clinical alternatives for clinicians and hospitals.
-
Product presentation as a front-line battleground: Octapharma’s U.S. launch of a 2‑gram presentation with a reconstitution device (January 2026) signals that ease-of-use and dose flexibility will be key differentiators in perioperative and emergency settings.
-
Regional players with scale: Established plasma fractionators in Asia and Europe continue to leverage integrated plasma networks and local regulatory familiarity to defend and expand share—particularly in markets where in-country plasma sourcing reduces lead times and cost.
Strategically, these moves imply that near-term initiatives should prioritize: (1) securing supply lines and flexible presentations; (2) accelerating evidence that supports use in acquired bleeding; and (3) designing reimbursement strategies that convert coding clarity into hospital formulary adoption.
Strategic actions for 2026 (prioritized roadmap)
-
Secure supply and reduce lead-time exposure — Execute multi-year procurement contracts and develop buffer stock strategies; evaluate toll-fractionation partnerships and contingency arrangements with licensed plasma centers.
-
Invest in presentation & logistics — Fast-track development or licensing of simplified reconstitution devices and pre-measured presentations to increase uptake in OR/trauma settings.
-
Regulatory & market-access playbook — Map approval pathways for label expansion into acquired fibrinopenia in prioritized markets; align clinical trials and real-world evidence to payer endpoints that support reimbursement and hospital formulary decisions.
-
Commercial segmentation — Prioritize accounts where coding and reimbursement clarity enable quicker adoption (e.g., hospitals with high case volumes and integrated procurement cycles). Tailor distribution models between specialty distributors and direct hospital contracting.
-
M&A and partnership scouting — Target assets that fill manufacturing gaps, add plasma collection capacity, or provide complementary hemostasis tools that strengthen perioperative bundles.
-
Evidence generation — Build pragmatic trials and registry pathways that demonstrate time-to-hemostasis and transfusion-sparing benefits; translate outcomes into cost-per-case analyses for hospital CFOs.
-
Risk management — Monitor donor-supply trends, regulatory changes to plasma collection rules, and potential trade disruptions; model scenarios that stress-test inventory against demand surges in trauma or pandemic contexts.
How to use this preview and next steps
This briefing illustrates the strategic stakes and directional market economics that should guide 2026 planning. If your priorities include transaction screening, market-entry sequencing, commercial rollout planning or supply‑chain resilience, our full report supplies the actionable datasets, proprietary forecasts and playbooks that convert these insights into executable plans.
PW Consulting’s full Human Fibrinogen Market study includes the complete financial model, granular regional and application splits, competitor scorecards, regulatory timelines and a toolkit of commercial templates. For leadership teams preparing budgets, evaluating M&A targets or seeking to operationalize a fibrinogen strategy in 2026, our advisory engagements pair these deliverables with scenario workshops to translate insight into decisions.
Contact PW Consulting to review the full dataset, schedule a tailored briefing, or commission a bespoke strategic due diligence package that aligns the fibrinogen opportunity with your portfolio and operational capabilities.
For detailed analysis of this topic, please visit the official page: Human Fibrinogen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com