

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Peptide Cancer Vaccine Market to Hit USD 263.9M by 2032, 18.5% CAGR

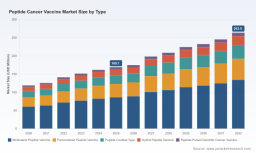
Peptide Cancer Vaccine Market — Strategic Imperatives for 2026 (PW Consulting Preview)
The peptide cancer vaccine market is passing an inflection point. After five years of sustained development and an increasingly sophisticated clinical pipeline, the market has moved from fragmented R&D activity into a near-term commercialization horizon. This preview summarizes why our full Peptide Cancer Vaccine Market report is a must-read for executives making resource-allocation and go-to-market decisions in 2026. It demonstrates the analytical depth behind our conclusions while intentionally withholding detailed segment-level tables and price forecasts to preserve the value of the full report.
Peptide Cancer Vaccine Market
Market snapshot: scale, trajectory and concentration
Using 2025 as the base year, PW Consulting’s topline market model shows the peptide cancer vaccine market expanding strongly from the early 2020s into the next decade. The market grew substantially through the 2020–2025 historical window and, driven by accelerating late‑stage clinical activity and improving regulatory throughput, is projected to continue expanding through our 2026–2032 forecast period at a compound annual growth rate of 18.5%. By 2032 the market reaches a materially larger commercial opportunity versus 2025, reflecting both product approvals and early adoption in defined oncology niches.
Peptide Cancer Vaccine Market
Despite this growth, market structure remains fragmented. The combined share of the top commercial/clinical players is in the low-to-mid twenties percent range for the leading groups, indicating healthy opportunity for new entrants and partnerships but also suggesting that first-mover advantages and IP fences will be decisive where they exist.
Peptide Cancer Vaccine Market
Why 2026 is strategic for corporate decision-makers
- Transition from R&D to commercialization: 2026 is the year when several vaccines currently in late Phase 1/Phase 2 will yield survival and disease-free survival readouts that materially affect regulatory and payer conversations. Companies must choose now whether to accelerate manufacturing scale-up, lock in commercial partnerships, or conserve capital for additional trials.
- Reimbursement and market access are still open questions: No peptide-based cancer vaccine has been licensed for marketing in the United States, creating a clear reimbursement gap. Organizations that shape the early value narrative and secure outcomes-based arrangements will gain durable advantage.
- Regulatory signal volatility: The FDA’s approval rate for novel peptide vaccines has improved recently, but overall clinical attrition after Phase II remains a limiting factor. Firms that can demonstrably reduce translational risk through biomarkers or adaptive trial design will shorten time-to-reimbursement.
- Manufacturing economics matter: Peptide vaccines are, by nature, relatively low-toxicity and cost-effective to manufacture with high stability—advantages that favor scalable CDMO strategies and enable flexible pricing approaches in a constrained payer environment.
What PW Consulting’s full report delivers (actionable content)
Our full Peptide Cancer Vaccine Market study is built to inform executable strategy, not just to summarize trends. Key deliverables include:
- Proprietary market sizing and forecast model (base year 2025; forecast period 2026–2032) with configurable scenarios and downloadable input/output sheets.
- Pipeline tracker and R&D heatmaps showing indication focus, development stage, biomarker linkage, and expected milestone timing across all active peptide vaccine programs.
- Competitive intelligence dossiers on leading and emerging players, including development strategy, IP position, manufacturing arrangements, and partnering behavior.
- Regulatory and reimbursement playbooks: strategic templates for evidence generation, HTA submissions, and outcomes-based contracting consistent with U.S. and major international frameworks.
- Commercialization playbooks with customer segmentation, likely early-adopter oncology centers, and pricing sensitivity scenarios tied to payer willingness-to-pay assumptions.
- Manufacturing and supply-chain assessment: CDMO selection criteria, scale-up risk matrix, and cost-of-goods (COGS) modeling under multiple production technologies.
- Decision-support tools: invest/partner/exit decision trees, NPV sensitivities keyed to survival readouts, and go/no-go thresholds for late-stage programs.
Competitive landscape — strategic takeaways on core players
The clinical-stage competitive set is heterogeneous: companies pursue diverse peptide formats (multivalent, personalized, cocktail and hybrid constructs, and dendritic cell-pulsed approaches) and disease strategies. Below we summarize strategic implications from selected leaders in the space.
- Elicio Therapeutics (Boston, MA) — Elicio’s lymph node-targeted amphiphile platform and lead program ELI-002 targeting mKRAS-mutated cancers have delivered notable clinical signals. Updated Phase 1 follow-up data reported extended median overall survival and meaningful relapse-free survival in minimal residual disease populations, and subsequent Phase 2 reporting documented robust antigen-specific T cell responses in nearly all evaluable patients. Strategic implication: Elicio’s data create a near-term pathway to a differentiated label in mutation-defined populations and strengthen its negotiating position with CDMOs and potential commercialization partners. Competitors should prepare for scenario-based responses: combinations, biomarker pooling, or licensing discussions.
- OSE Immunotherapeutics (Paris, France) — With multi-peptide therapeutic candidates such as OSE2101, the company presented positive topline maintenance-phase results in pancreatic cancer and has mapped a Phase 3 plan in NSCLC for populations with secondary resistance to immunotherapy. Strategic implication: OSE demonstrates a pragmatic approach—deploying vaccines as maintenance or sequence therapy—reducing the bar for clinical benefit in hard-to-treat settings. This suggests a commercially attractive entry route for vaccine platforms: add-on or maintenance indications that complement standard cytotoxic or targeted therapy.
- TapImmune (Houston, TX) — Focused peptide-based vaccines such as HER2/neu-targeted programs position TapImmune for vertical play in biomarker-rich oncology segments (e.g., HER2-positive disease). Strategic implication: Niche, high-unmet-need segments with established biomarker infrastructure may be the fastest path to adoption, particularly when the vaccine can be paired with existing standards of care.
- OncoPep (Boston, MA) — Developers of multi-peptide therapeutic vaccines targeting tumor-associated antigens (e.g., PVX-410) highlight another credible route: specialization in discrete hematologic or solid tumor indications with predictable clinical endpoints. Strategic implication: Discipline in indication selection and early payer engagement around endpoints will be crucial.
Industry dynamics that should drive strategic choices in 2026
- Regulatory opportunity and risk: Improved early approval rates for novel peptide vaccines indicate regulators’ increasing comfort with modality-level safety and mechanism, but attrition beyond Phase II remains a material risk. Companies should prioritize adaptive trials and biomarker-enriched cohorts to reduce late-stage failure.
- Payer uncertainty: The absence of licensed peptide vaccines in the U.S. generates a reimbursement gap; companies must build real-world evidence and engage payers early to inform pricing and outcomes-based contract parameters.
- Manufacturing advantage: Peptide chemistry lends itself to lower toxicity and predictable COGS; firms that lock-in flexible, high-quality CDMO capacity will preserve margin advantages during commercialization.
- Combination strategies: Vaccines are most likely to reach clinical and commercial success when combined with checkpoint inhibitors, targeted agents, or as maintenance after induction—each combination carries distinct evidence and payer implications that should be modeled now.
Practical strategic moves for executives
- Prioritize biomarker investments that increase the probability of late-stage success and payer acceptance.
- Develop manufacturing partnerships with flexible scale-up options and dual-sourcing to mitigate single-point-of-failure risks.
- Design evidence generation that targets regulatory endpoints and payer-relevant outcomes simultaneously (i.e., OS/DFS plus health economics and real-world endpoints).
- Structure commercial partnerships early where capital constraints exist: regional licensing, co-promotion, and outcomes-based payment pilots can accelerate market access without full commercial build-out.
- Prepare financial scenarios across conservative, base, and accelerated adoption curves—our report includes ready-to-use templates calibrated to clinical milestone timings.
Next steps — how to use the full PW Consulting report in 2026 planning
For boards, corporate development teams, and BU leaders preparing budgets and R&D roadmaps for 2026, the full report is designed to be operational. It provides the segmentation detail, regional models, pricing sensitivities, and competitor intelligence that underpin defensible investment cases and partnership negotiations. By combining market sizing, clinical pipelines, reimbursement roadmaps, and CDMO assessments into one decision-support package, PW Consulting enables leaders to convert scientific promise into commercial reality with quantifiable risk controls.
To preserve the commercial utility of our analysis, this preview omits granular segmentation tables and certain model outputs. If you are preparing strategic choices in 2026—capital allocation, licensing, or clinical strategy—accessing the full report will give you the calibrated datasets and tactical playbooks required to act with confidence.
For detailed analysis of this topic, please visit the official page: Peptide Cancer Vaccine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com