

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Decorative HPL Market to Hit USD 18.04 Billion by 2032, 5.5% CAGR

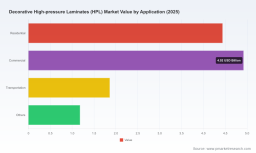
Decorative High‑pressure Laminates (HPL) Market: Strategic Intelligence Briefing for 2026 Decision‑makers
As global demand for decorative High‑pressure Laminates (HPL) continues its steady recovery from pandemic disruption, leaders facing 2026 strategic choices need an evidence‑based playbook that links product, compliance and supply‑chain actions to profit outcomes. PW Consulting’s new market study — anchored on a 2025 base year and a seven‑year outlook to 2032 — synthesizes macro growth, regulatory stress‑tests, raw‑material risk mapping, and competitor motions into a single actionable resource. At the market level, our topline projection implies a mid‑single digit compound annual growth rate (CAGR) of approximately 5.5% across the forecast horizon, taking the market from an evaluated global size in 2025 to a materially larger industry by 2032. For executives building 12–36 month plans in 2026, that trajectory translates into both predictable expansion opportunities and discrete transition risks that require immediate planning.
Decorative High-pressure Laminates (HPL) Market
Why this study matters to your 2026 playbook
- Regulatory timing is compressing product roadmaps. Key administrative milestones in major markets — notably new REACH emission limits coming into force and North American low‑emission mandates — create hard deadlines for product reformulation, testing, and certification. Delay translates into lost sales access and higher rework costs.
- Raw‑material exposure is concentrated. Melamine‑formaldehyde chemistry underpins the majority of decorative HPL formulations; the industry remains susceptible to feedstock volatility and regional price shocks that can compress margins within a single quarter.
- Design and sustainability are now purchase determinants. End‑user preference is shifting toward low‑emission, biosourced and certified surface products. Recent product launches and certifications from leading manufacturers signal that sustainability credentials are becoming baseline requirements for both commercial and residential channels.
- Market structure favors focused scale plus niche differentiation. The sector exhibits moderate consolidation — a competitive landscape where top global players hold meaningful share but substantial regional and specialty opportunities remain for agile challengers.
What PW Consulting’s report delivers (practical content)
- Top‑down and bottom‑up market sizing and a clear forecast framework (2026–2032) that quantifies the growth path under baseline, downside and accelerated adoption scenarios.
- Price, cost and margin models that translate feedstock price paths into P&L impacts for common product grades; sensitivity matrices enable rapid what‑if modeling for procurement and pricing teams.
- Regulatory impact assessment and compliance playbook: timelines, certification pathways, passthrough options, and estimated implementation cost buckets for key jurisdictions.
- Supply‑chain mapping and raw‑material supplier risk scoring, including alternative resin pathways and strategic sourcing options to mitigate single‑source exposure.
- Detailed competitor benchmarking and capability matrices (manufacturing footprint, design portfolio, sustainability certifications, product innovation cadence), coupled with scenario‑driven threat analysis.
- Go‑to‑market playbooks for OEMs, distributors and branded manufacturers: channel economics by customer segment, SKU rationalization guidance and targeted pricing tactics.
- M&A and partnership heatmap: regional white spaces, attractive asset archetypes (capacity, IP, distribution) and valuation heuristics for deal origination teams.
- Executive dashboards and slide packs ready for board and investor briefings that translate technical inputs into strategic options.
Competitive landscape — who’s moving and why it matters
The report profiles the industry’s most influential manufacturers and distils the strategic implications of their recent moves. Public and private leaders are taking three distinct approaches: (1) scale‑led product breadth and distribution, (2) sustainability and certification as market entry barriers, and (3) technical premiumization for architectural and exterior use cases.
Decorative High-pressure Laminates (HPL) Market
- Formica Group (United States) — maintains category leadership through a broad design portfolio and recent sustainability credentials. Their USDA biobased certification underscores how certification can be leveraged as both a product differentiator and a market access lever in institutional procurement.
- Wilsonart LLC (United States) — doubling down on design innovation while foregrounding recycled content and low‑emission offerings. Their new no‑repeat woodgrain and natural color launches signal continued investment in higher‑value decors that sustain margin premium.
- EGGER Group & Pfleiderer Group (Europe) — competing on multi‑layer performance and catalog depth; European firms are also responding to continental regulatory tightening with accelerated testing and portfolio rationalization.
- Greenlam Industries — demonstrates how regional manufacturing scale plus design localization (recent catalogue updates) support faster go‑to‑market in high‑growth Asia Pacific corridors.
- Fundermax, Trespa, Abet, Arpa, Panolam — represent differentiated plays: high‑end architectural surfaces, exterior cladding, biosourced product variants, and integrated systems solutions. Each brand’s certification, texture innovation and targeted applications provide a roadmap for niche premiumization.
From a concentration standpoint, the market is neither a pure commodity oligopoly nor fully fragmented: top players hold meaningful share yet the space remains contestable for focused entrants and value‑added regional specialists. The operational takeaway is clear — competing solely on cost is a narrowing path; competing on certified low‑emission propositions, unique decors and integrated service models yields more durable returns.
Decorative High-pressure Laminates (HPL) Market
Regulatory and raw‑material dynamics to prioritize in 2026
- EU REACH tightening (effective August 2026): harmonized limits for formaldehyde emissions require product validation and labelling changes. Manufacturers must finalize reformulation and testing calendars now to avoid market disruption.
- North American low‑emission standards: U.S. federal and state regimes are increasing compliance complexity for exported products; product lines intended for the U.S. market should be pre‑qualified against these regimes.
- Resin and feedstock risk: melamine‑formaldehyde remains predominant. Price volatility and regional supply shocks (e.g., recent formaldehyde price spikes) necessitate multi‑sourcing, contracting strategies and consideration of alternative chemistries where feasible.
- Certification as market entry control: Biosourced and post‑consumer recycled certifications are rapidly becoming table stakes in certain institutional segments — they also unlock premium pricing and longer contract tenures.
A pragmatic six‑step playbook for 2026
- Implement a prioritized compliance roadmap: map SKUs to regulatory timelines, allocate testing budgets, and fast‑track certifications for high‑margin SKUs.
- Stress‑test margins using PW Consulting’s price/cost models: identify SKUs that can carry price increases versus those requiring reformulation or discontinuation.
- Negotiate strategic resin contracts with flexibility clauses and alternative supplier development to blunt single‑quarter shocks.
- Pursue targeted product premiumization: combine certified low‑emission claims with distinctive textures and design exclusives for commercial and architectural buyers.
- Rebalance the go‑to‑market mix: expand channel partnerships in segments adopting certified HPL fastest, and concentrate direct sales where specification control yields higher margins.
- Scan M&A selectively for capacity, specialty grades (compact/exterior HPL) or design IP that accelerate compliance and market entry rather than merely adding commodity volume.
Why PW Consulting’s analysis should be at the center of your 2026 planning cycle
This report is intentionally operational: it moves beyond broad trend description to deliver calibrated, executable options. Our methodology integrates plant‑level supply data, proprietary price and margin models, stakeholder interviews across the value chain, and regulatory stress‑testing under multiple scenarios. The result is a decision support toolkit that helps commercial, procurement and corporate development teams prioritize investments, price defensively, and define M&A screens that create immediate strategic optionality.
We deliberately withhold granular segment tables, regional breakdowns and subscription‑level forecasts from this briefing to encourage focused engagement with the full dataset. The market intelligence you need to set 2026 budgets, M&A targets and compliance timelines is contained in the full report and the accompanying decision decks.
Next steps
- Request a tailored executive briefing to map our forecast scenarios to your product portfolio.
- Commission a rapid compliance gap assessment for HPL SKUs destined for European and North American markets.
- Engage our M&A team to develop a short‑list of target archetypes aligned to your strategic thesis (capacity, sustainability credentials, or design IP).
For teams ready to convert forecast insight into tactical action in 2026, PW Consulting’s Decorative HPL market study delivers the prioritized intelligence and tools required to protect margins, secure market access and seize differentiated growth. Contact our industry practice to schedule a demonstration of the datasets and scenario models referenced in this briefing.
For detailed analysis of this topic, please visit the official page: Decorative High-pressure Laminates (HPL) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com