

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,2-Pentanediol Market to reach USD 281.2M by 2032 at 6.5% CAGR

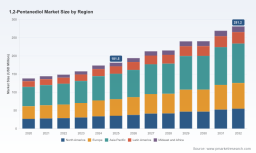
1,2-Pentanediol Market — Strategic Outlook for 2026 Corporate Decision‑Making
Executive snapshot
The 1,2-pentanediol market has transitioned from a niche specialty chemical into a strategic ingredient class for personal care, pharmaceutical formulations and select industrial applications. Our base-year sizing (2025) and a seven-year forecast (2026–2032) show continued expansion: the market grew steadily from 2020 through 2025 and, under our central scenario, is expected to expand at a compound annual growth rate (CAGR) of 6.5% across the forecast window. By 2032 the market is forecast to be materially larger than the 2025 base, a dynamic that will influence sourcing, product roadmaps and M&A activity through 2026 and beyond.
1,2-Pentanediol Market
Why this report matters for 2026 strategies
- Resource allocation and portfolio prioritization: A clear view of projected market growth and demand pockets enables leadership to prioritize R&D and commercial resources toward formulations and grades likely to deliver the highest return on invested capital over the next three years.
- Supply‑chain risk management: Volatile petrochemical feedstocks and regional disruptions are already transmitting price and lead‑time pain into pentanediol supply. Firms that proactively hedge, diversify feedstock exposure, or secure offtake from biobased suppliers will gain a relative cost and reliability advantage in 2026.
- Sustainability positioning: The rise of biobased grades and verified upcycling routes changes buying criteria for major OEMs in cosmetics and household care. Understanding supplier capabilities and certification pathways is now a strategic imperative.
- Regulatory and compliance planning: The product’s multifaceted use cases (cosmetics, pharma, food-contact adjacencies) mean layered regulatory requirements; early investment in dossier preparation shortens time‑to‑market for new formulations.
- M&A and partnership timing: With a market that is growing at a mid‑single-digit CAGR and concentrated supply at the top end, 2026 presents selective acquisition and JV opportunities to secure capacity or strategic technologies.
What this study delivers (practical content for commercial teams)
- Comprehensive market sizing and trend maps from 2020–2025 (historical base) and detailed forecasts for 2026–2032, including scenario variants for upside/downside demand and price trajectories.
- Demand-driver diagnostics: granular analysis of formulation trends in cosmetics/personal care, pharmaceutical excipient adoption, and niche industrial applications — with actionable implications for product managers and sales leaders.
- Supply‑side intelligence: supplier capacities, technology nodes (petrochemical vs. biobased routes), and a modular model that simulates capacity additions, plant lead times and utilization under multiple demand scenarios.
- Raw‑material sensitivity and pricing playbooks: modelled linkages between input feedstock moves (n‑pentene, naphtha, LPG derivatives) and downstream pentanediol cost curves, with risk mitigation levers to deploy in procurement.
- Regulatory matrix and certification pathways: a practical roadmap for dossier development, safety testing priorities, and timelines to meet cosmetic and pharmaceutical regulator expectations across key jurisdictions.
- Commercial playbooks: go‑to‑market options, segmentation strategies, and prioritized customer targets — all designed for fast execution by business development and marketing teams.
- Investment and M&A screening toolkit: shortlists and valuation frameworks calibrated to the market’s growth profile and competitive concentration, including integration and capacity optimization checklists.
Macro and industry dynamics shaping near‑term strategy
- Feedstock volatility: Price and availability of petrochemical precursors (notably n‑pentene derivatives) remain a primary cost driver. Historical data through 2025 shows episodes where feedstock swings materially altered producer margins; our sensitivity models quantify these impacts and suggest threshold levels where contract renegotiation or buyouts become necessary (Industry Market Data, May 2025).
- Geopolitical shocks: Conflict‑related disruptions in the Middle East have intermittently impacted flows of naphtha, LPG and gas‑derived feedstocks, producing short‑term volatility spikes. Procurement teams should build scenario triggers that link regional risk indicators to procurement actions (Analysts Insights Report, April 2026).
- Feedstock sourcing & certification constraints: Transitioning to biobased or upcycled feedstocks can improve ESG credentials but extends supplier qualification timelines due to certification bottlenecks and traceability requirements; planning these qualification pipelines well ahead of launch is now a best practice (Analysts Insights Market Report, June 2026).
- Regulatory complexity: A multi‑jurisdictional, sometimes hexagonal, regulatory environment for use in cosmetics and pharmaceutical applications necessitates harmonized safety dossiers and cross‑functional governance within companies (Koyon Chemical Blog, December 2025).
Competitive landscape — what market leaders are doing
The incumbent supplier set blends multinational formulators with regional chemical producers. Leading players are pursuing three strategic moves: (1) expanding biobased capacity, (2) integrating up the value chain into formulation services, and (3) securing differentiated sustainability credentials to win specification slots at major brand owners.
1,2-Pentanediol Market
- Symrise AG (Holzminden, Germany) — Symrise has positioned Hydrolite® 5 and Hydrolite® 5 green as multifunctional cosmetic ingredients manufactured via dedicated biobased facilities in multiple geographies. Recent strategic actions include the commissioning of a biobased production unit in Granada, Spain (September 2025) and public recognition for its upcycling approach (award, October 2025). For buyers, Symrise offers the combination of scale and sustainability claims that shorten internal approval cycles for brand teams.
- Evonik Industries AG (Essen, Germany) — Evonik’s dermosoft® Pentiol eco targets customers seeking a vegetable‑derived alternative to petrochemical grades. Evonik’s strategy centers on substituting petrochemical feedstocks in personal care while leveraging its formulation expertise to embed pentanediol into higher‑margin ingredient systems.
- Aurora Chemical Co., Ltd. (Yantai, China) — A vertically capable supplier with multiple production bases and a strong R&D focus, Aurora supports global distribution needs and fast customer qualification cycles for cosmetic applications. Their regional footprint makes them a common partner for price‑sensitive customers seeking reliable supply across Asia and beyond.
- Shandong Yino Biologic Materials Co., Ltd. (Liaocheng, China) — Operating dedicated biobased pentanediol capacity, the company is an important regional supplier for both cosmetics and industrial applications, particularly where local certification and supply proximity matter.
Market structure and competition — implications for 2026 planning
The supply base is neither atomistic nor monopolistic: a limited list of established suppliers controls a material portion of global capacity, yet there remains room for specialized entrants focused on biobased credentials or on servicing underserved industrial pockets. For buyers, this translates into negotiating leverage when multiple suppliers can meet technical specs; for suppliers, it creates incentive to differentiate on sustainability, service levels, or integrated formulation capabilities.
1,2-Pentanediol Market
Actionable recommendations for 2026
- Lock strategic supply early: Given documented supplier qualification delays for biobased feedstocks, begin supplier audits, third‑party verification and offtake negotiations in H1–H2 2026 for launches planned in 2027–2028.
- Implement feedstock stress testing: Run procurement stress tests that map feedstock price thresholds to margin erosion and identify at‑what points to invoke contract hedges, diversion options or pass‑through pricing.
- Pursue selective co‑development: Negotiate formulation co‑development with suppliers who can offer verified sustainability claims; this shortens the commercialization cycle and reduces regulatory friction.
- Prioritize regulatory readiness: Invest in cross‑functional dossier teams to preempt staggered approval timelines when entering pharmaceutical adjacencies or novel cosmetic claims.
- Prepare M&A scorecards: Use our acquisition playbook to identify targets with complementary capacities, feedstock flexibility or niche formulation expertise; valuations should explicitly model integration capex and certification timelines.
- Adopt scenario‑based pricing: Use the report’s interactive pricing model to develop customer‑facing escalation and rebate mechanisms that protect margin while remaining competitively priced.
How to convert insight into action
This report is delivered with downloadable models, scenario simulators and a supplier short‑list tailored to commercial, procurement and corporate development teams. We intentionally present a high‑level strategic view here to demonstrate the report’s scope and practical value; the full document contains the detailed segment breakouts, supplier capacity tables, pricing ladders and the interactive financial models that enable rapid decision execution.
Next steps
For executives planning capital allocation, procurement leaders building supplier qualification roadmaps, or commercial teams preparing product launches in 2026, the full PW Consulting 1,2‑Pentanediol Market report contains the specific datasets, contract negotiation playbooks and supplier‑by‑application matrices needed to move from strategy to execution. Access to the complete report and the interactive tools is available on our web portal, where subscribers can also request bespoke scenario runs tailored to their company’s portfolio and geography.
For detailed analysis of this topic, please visit the official page: 1,2-Pentanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com