

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: UV Lamp Market to Reach USD 1,177M by 2032 at 14.9% CAGR

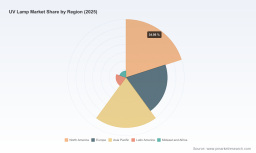
UV Lamp Market 2026: Strategic Imperatives for Leaders — A PW Consulting Industry Brief
Executive snapshot
As organizations finalize 2026 investment plans, the UV lamp market presents both clear growth trajectories and concentrated areas of strategic risk. Our baseline modelling — using 2025 as the base year and drawing a five‑year historical view (2020–2025) — shows the market expanding from a notable sub‑quarter‑billion USD in 2020 to roughly USD 450 million in 2025, before accelerating through the forecast horizon. By 2032 our scenario suite points to market size in excess of USD 1.1 billion under the central case, underpinned by a forecast CAGR of approximately 14.9% for the 2026–2032 period. Market concentration remains modest: the top three players account for roughly one quarter of market revenue, and the top five just over one quarter — a structure that creates pockets of competitive leverage and ample opportunity for disruption.
UV Lamp Market
Why this matters for 2026 decision‑makers
-
Portfolio prioritization. Rapid growth and technology divergence mean capital allocation decisions made in 2026 will determine competitiveness for the next technology cycle. Whether to accelerate LED‑centric R&D, retrofit legacy mercury systems, or pursue hybrid offerings is a balance of regulatory trajectory, unit economics, and go‑to‑market timing.
UV Lamp Market -
Regulatory timing. Several near‑term regulatory events create binary outcomes for incumbent positions. Firms that sequence certification, disposal capabilities, and product roadmaps to align with evolving bans and exemptions will avoid stranded inventory and capture premium pricing for compliant systems.
UV Lamp Market -
Supplier and raw‑material risk. The dependence of conventional lamp performance on factors such as mercury vapor pressure and supply of specialty components (e.g., quartz sleeves for water‑treatment systems) necessitates proactive supply‑chain interventions in 2026 that extend beyond traditional procurement playbooks.
-
M&A and partnership windows. The modest top‑line concentration means targeted acquisitions and strategic partnerships can materially move market share. 2026 is a pivotal year to secure technology access or expand channel reach before LED components and system integration converge.
What PW Consulting’s UV Lamp Market research delivers
This report is designed as an actionable playbook for executives and investors. We combine rigorous market sizing with operational tools to convert insight into decisions. Key practical deliverables include:
-
Reconciled market model (2020–2032): granular topline and demand drivers, with scenario variants for regulatory shocks, LED adoption rates, and water/air/food disinfection demand elasticity.
-
Investment case templates: three prioritized use‑cases (product R&D acceleration, aftermarket service expansion, strategic M&A) with IRR/PP metrics and sensitivity to component pricing and adoption curves.
-
Procurement and supplier risk matrix: supplier concentration, critical material dependencies (including quartz and mercury handling), and recommended contractual clauses for volume and quality assurance.
-
Regulatory tracker and compliance playbook: timelines, regional divergence, and operational steps to align manufacturing, labeling, transport and disposal practices with evolving laws.
-
Go‑to‑market & channel playbook: application‑specific GTM blueprints (water, air, surface, food/beverage segments) with suggested product architectures, pricing ladders, and pilot KPIs.
-
Technology roadmap and IP posture analysis: comparative unit economics between mercury‑based lamps and UV‑C LED modules, lifetime and maintenance profiles, and recommended R&D prioritization.
-
Executive dashboard & early‑warning scorecard: leading indicators (component lead times, RoHS exemption status, certification backlogs) to trigger tactical pivots.
Competitive landscape — who to watch
The market contains a mix of specialized manufacturers, systems integrators, and vertically integrated players. Our competitive mapping focuses on capability clusters rather than raw market share figures, providing a clearer view of where incumbent strengths and vulnerabilities lie:
-
American Ultraviolet (Indiana, USA): strong in industrial UV curing systems and lamp assemblies. Recent trade show activity in early 2025 and 2025 industry conferences underscores a continued focus on curing and industrial partnerships — useful signals for channel and OEM collaboration strategies.
-
IST METZ (Germany): positioned where high‑performance lamp and LED system engineering meets industrial automation. Announced system advancements in early 2026 that suggest an emphasis on higher‑throughput curing and disinfection platforms.
-
Silanna UV (Brisbane, Australia): an LED specialist with recent product introductions (mid‑2026 TO‑39 flat window packages) that accelerate UV‑C LED module integration for disinfection and sensing. Their cadence is a bellwether for component miniaturization and rapid module adoption.
-
UV Resources (Santa Clarita, CA) and VIQUA (Canada): both show deep water‑treatment product portfolios and aftermarket services — important players for utilities and municipal procurement pipelines.
-
Excelitas Technologies and Dr. Hönle AG: established brands with broad UV curing and lamp businesses that can leverage scale for industrial adoption; their positioning makes them natural acquirers or consolidators in mature segments.
-
First Light Technologies and UVMedico: niche providers focused on disinfection applications, with UVMedico’s medical orientation signaling higher compliance and certification competencies.
Recent firm‑level activities — trade shows, product launches, and press releases — show a market in which legacy lamp suppliers and LED specialists are accelerating product roadmaps simultaneously. For executives, this means defensive and offensive moves should be considered in parallel: protect installed bases while building LED pathways.
Policy and technology crosswinds shaping outcomes
-
RoHS exemption timing: the pending expiry of certain EU exemptions for mercury vapor UV lamps in late 2026/early 2027 creates a clear regulatory inflection. Firms selling into European markets must model compliance costs and retrofit timelines now to avoid forced product withdrawals or margin compression.
-
Hazardous waste classification: in key markets such as the U.S., mercury lamps are subject to universal waste handling rules for transport and disposal. This increases end‑of‑life costs and can alter customer purchasing decisions in favor of lower‑disposal‑cost alternatives.
-
Performance sensitivity to raw materials: conventional lamp UV output is sensitive to mercury vapor pressure and requires components such as quartz sleeves for higher‑output water‑treatment systems. These are not trivial supply considerations — they are performance levers for engineering teams and procurement levers for sourcing teams.
Strategic scenarios for 2026 planning
We recommend that management teams develop playbooks for three plausible scenarios — these are included in the PW report and can be used directly in board discussions:
-
Conservative transition: slower LED adoption, regulatory glide paths extended. Prioritize aftermarket services, retrofit kits, and incremental efficiency gains in mercury lamp lines while selectively investing in LED pilots.
-
Accelerated LED adoption: rapid module cost declines and expedited regulatory restrictions. Accelerate LED platform investments, secure long‑lead components, and pursue bolt‑on M&A to access module IP and channel reach.
-
Regulatory shock: restrictive bans and higher disposal costs in core markets. Implement contingency stock strategies, establish compliant disposal services (to monetize waste management), and fast‑track compliant product conversions.
Practical next steps for executives
-
Run a two‑quarter test of LED vs. conventional offers in a controlled channel to collect real price elasticity and maintenance data; use this to update your unit economics in Q3 2026.
-
Audit supply agreements for mercury, quartz, and LED die supply; introduce clauses for substitution, volume flex, and performance warranties aligned to regulatory timelines.
-
Map installed base by geography and application; develop retrofit/upgrade bundles with predictable service economics to protect revenue streams during transitions.
-
Identify 3–5 high‑value M&A or partnership targets (technology, channel, or disposal services) and open diligence tracks before H2 2026.
-
Embed the PW Consulting early‑warning dashboard into monthly executive reporting to operationalize regulatory and supply‑chain triggers.
What we intentionally withhold here — and why
To preserve the value of the full market intelligence package, specific regional and application split percentages and detailed supplier market shares are not disclosed in this brief. Those segment‑level allocations and asset‑level financials are core deliverables in the full report and are necessary for transaction due diligence and site‑level go‑to‑market planning. If your 2026 strategy depends on precise regional demand curves, unit economics by application, or target vendor revenue breakdowns, the complete report provides those datasets together with exportable models.
Final note — timing is material
With the market on a high‑teens growth trajectory into the next decade, 2026 is not merely another planning year — it is a pivot window. Decisions on R&D prioritization, supply‑chain locking, compliance investments, and M&A executed now will disproportionately influence competitive positioning as LED and regulatory forces converge. PW Consulting’s UV Lamp Market research equips executives with the scenario modelling, tactical playbooks, and supplier intelligence needed to convert this market inflection into durable advantage.
For detailed analysis of this topic, please visit the official page: UV Lamp Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com