

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogen Sulfide Removal Market to Reach USD 2,447.06M in 2026 at 5.5% CAGR

Hydrogen Sulfide Removal Market: Strategic Outlook for 2026 Decision‑Makers
Introduction — why this briefing matters
As companies confront tightening emissions rules, volatile feedstock chemistry and an increasingly cost‑conscious capital market, hydrogen sulfide (H2S) management has moved from engineering footnote to board‑level priority. PW Consulting’s latest Hydrogen Sulfide Removal Market study (base year 2025) synthesizes seven years of historical behavior (2020–2025) and provides a forward projection through 2032. The objective of this briefing is to crystallize the strategic value of that study for executives planning capital allocation, technology selection and M&A in 2026 — showing what to act on now and why deeper, transaction‑grade detail in the full report is a practical advantage.
Hydrogen Sulfide Removal Market
Market trajectory in macro terms
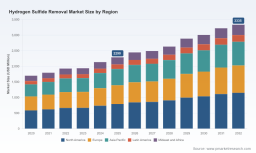
The market for H2S removal solutions has expanded steadily from a market size of USD 1,700 million in 2020 to USD 2,290 million in 2025 (base year). Our consolidated forecast projects continued growth through the next decade, with the market tracking a compound annual growth rate (CAGR) of approximately 5.5% and reaching roughly USD 3,335 million by 2032. The near‑term (2026) projection continues this momentum, reflecting a confluence of compliance-driven demand, rising gas processing throughput in select basins, and cost optimization programs across biogas and wastewater operations.
Hydrogen Sulfide Removal Market
What is driving growth — the structural dynamics
- Regulatory pressure and safety limits: Stricter discharge and exposure standards are non‑discretionary drivers. U.S. NESHAP and European directives are pushing operators toward sub‑10 ppm discharge thresholds in many contexts, while occupational safety ceilings (OSHA) and local air district advisories tighten acceptable ambient concentrations. These rules catalyze investment in reliable H2S abatement across refineries, gas processors and municipal facilities.
- Feedstock and operating economics: As the energy mix evolves, operations are receiving more variable, sulfur‑bearing feedstocks (e.g., high‑H2S produced water, variable biogas from AD facilities). Operators are balancing upfront CAPEX for regenerative media or liquid redox systems against recurring chemical and disposal OPEX — a tradeoff central to procurement and engineering decisions.
- Technology differentiation: Solutions range from scavengers and adsorbents to regenerative liquid redox processes and integrated recovery units. Technology performance now competes on lifecycle cost, waste footprint, footprint scalability and operational resilience under fluctuating sulfide loads.
- Commercial and transactional forces: Service‑based contracting, modular skid deployment and vendor‑provided consumables shift risk profiles and cashflow patterns. Private equity interest in midstream and environmental services is amplifying M&A activity and accelerating consolidation in adjacent service segments.
Regulatory and safety context that shapes commercial choices
- National and regional emissions standards are converging on lower permitted H2S concentrations in fuel gas and atmospheric discharges, increasing the technical bar for abatement systems.
- Occupational exposure rules — notably low ceiling limits and strict peak caps — make reliable real‑time monitoring and fast‑acting remediation mandatory elements of project specifications.
- Local community thresholds in some jurisdictions are forcing earlier engagement on odor control and continuous ambient monitoring, which in turn influences selection of treatment technology and reporting infrastructure.
Competitive landscape — practical implications for sourcing and partnership
The supplier base is diverse and commercially active. Market concentration metrics indicate a moderately fragmented market (CR3 ~25%, CR5 ~30%), which means there is space for both global incumbents and agile niche providers. The next 18 months will be shaped by productization of new chemistries, field‑proven process variants and commercial models that shift lifecycle economics from CAPEX to OPEX.
Hydrogen Sulfide Removal Market
- Global service players: Longstanding oilfield and gas service companies continue to leverage scale and integrated offerings (adsorbent chemistries, catalysts and full‑system supply). These suppliers are attractive partners where turnkey installation, spare parts logistics and cross‑commodity relationships matter.
- Technology specialists and scaleups: Smaller innovators are pushing liquid redox, novel scavengers and low‑waste chemistries to solve niche, high‑sulfide problems or to serve distributed biogas and wastewater markets. Their case studies often show outsized operational savings but require careful due diligence on long‑term reagent availability and service coverage.
- Recent, market‑moving developments: Two illustrative examples from 2026 highlight how quickly vendor differentiation can shift: a major liquid‑redox supplier announced a successful field trial in a Permian production environment reporting sustained >99% removal without solid waste, and a technology provider published a case study showing seven‑figure monthly chemical cost savings at a high‑H2S produced water site. These events accelerate adoption cycles for low‑waste and low‑OPEX solutions and should be read as leading indicators for procurement managers and investors.
What PW Consulting’s report delivers — practical, transaction‑grade tools
Our full study goes beyond directional narrative. For executives making 2026 decisions, the report is structured to directly support procurement, engineering and corporate development workflows. Key deliverables include:
- Validated market sizing and 2026–2032 scenario models (base year 2025), with transparent assumptions so finance teams can re‑run sensitivities against different CAPEX/OPEX mixes.
- Technology performance matrices and lifecycle TCO templates that benchmark regenerative vs non‑regenerative approaches under variable sulfide loading, chemical price volatility and waste‑disposal constraints.
- Supplier benchmarking dashboards (commercial coverage, reagent supply security, installed base health, service SLAs) and a procurement playbook for RFP design that prioritizes outcomes over product specs.
- Regulatory impact maps and compliance timelines tailored to North American, European and APAC jurisdictions, with escalation triggers for operators exposed to tightening local thresholds.
- Investment and M&A decision frameworks: target screening filters, integration risk checklists and earn‑out structures calibrated to technology obsolescence and consumables dependence.
- Operational playbooks and case studies showing how companies have realized chemical and disposal savings, shortened interlocks and reduced downtime through swapped chemistries, reagent optimization and improved process controls.
To preserve the commercial value of the intelligence and to respect client confidentiality, the report’s granular segmentation (regional, application and technology splits) and supplier‑level financials are available only in the full dataset and online portal. This executive briefing highlights the themes; the attached online toolkit supplies the numeric granularity decision teams require.
How executives should act in 2026 — prioritized recommendations
- Immediate (0–6 months): Run a rapid TCO comparison for any upcoming retrofit or replacement projects, explicitly modelling reagent supply risk and disposal cost escalations. Favor technologies with demonstrable low waste footprints where community monitoring and local rules are tightening.
- Near term (6–18 months): Convert short‑term chemical purchasing into performance contracts where feasible. Use supplier scorecards to shift from unit‑price buying to outcome‑based SLAs that cover reagent performance and residuals handling.
- Portfolio strategy (18–36 months): For companies with multiple sites, standardize on a small set of vetted technologies to reduce spares complexity and simplify operator training. For investors, screen targets with proven field trials and validated cost‑of‑ownership reductions.
- Regulatory readiness: Incorporate forward‑looking regulatory scenarios into project approval workflows. If operating in jurisdictions with aggressive ambient thresholds, prioritize early deployment of continuous monitoring and control logic that integrates with H2S abatement systems.
Closing: the strategic reading list
H2S removal is no longer a purely technical procurement item; it is a strategic lever that affects compliance, OPEX, balance‑sheet treatment and community relations. PW Consulting’s Hydrogen Sulfide Removal Market study provides a pragmatic, finance‑ready foundation for 2026 decisions — combining market trajectories, regulatory vectors and supplier dynamics with the decision tools operators and investors need to act decisively.
For the full numerical breakdown, downloadable models and supplier scorecards that support procurement RFPs and M&A diligence, please access the full report and online portal. The granular segmentation and vendor financials are intentionally withheld from this preview to preserve the analytical value of the subscription package and to enable tailored briefings for transaction teams.
For detailed analysis of this topic, please visit the official page: Hydrogen Sulfide Removal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com