

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tertiary Dodecyl Mercaptan Market to Reach USD 584 Million by 2032

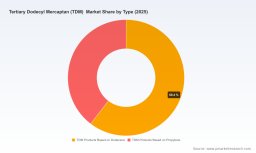
Tertiary Dodecyl Mercaptan (TDM) Market Outlook 2026 — Strategic Intelligence for Executive Decision‑Making
As PW Consulting’s lead industry analyst, I present an executive introduction to our Tertiary Dodecyl Mercaptan (TDM) market study designed to inform high‑stakes corporate decisions in 2026. This preview surfaces the evidence, competitive framing, and regulatory contours that matter most to producers, buyers, and financial sponsors — while intentionally withholding granular segmentation datapoints that are available in the full report to protect the commercial value of our insights.
Tertiary Dodecyl Mercaptan (TDM) Market
Why TDM matters in 2026
TDM sits at the intersection of synthetic rubber chemistry, polymer performance control, and several specialty chemistries used across automotive, industrial, and consumer applications. After a steady recovery through 2020–2025, the global TDM market reached a meaningful scale in our base year (2025) and is projected to expand at a mid‑single‑digit compound annual growth rate (5.8% CAGR) through the 2026–2032 forecast horizon. Measured on a revenue basis in USD Million, the market has grown from the low‑hundreds in 2020 to nearly four‑hundred million by 2025, with a trajectory that points toward a market approaching six‑hundred million by 2032.
Tertiary Dodecyl Mercaptan (TDM) Market
For senior executives, that combination of scale and steady growth signals two competing priorities: (1) protect margin through operational excellence and regulatory compliance, and (2) capture upside by selectively participating in higher‑value segments where purity, low‑odor, or formulation expertise command premiums. The balance between those priorities will define winning strategies in 2026.
Tertiary Dodecyl Mercaptan (TDM) Market
Market trajectory — what the top‑line numbers tell you
-
Historical momentum (2020–2025): The sector recovered and consolidated after pandemic disruption, demonstrating resilient end‑market demand and improving feedstock economics for key producers.
-
Near‑term outlook (2026): Growth continues as polymer producers and formulators intensify demand for controlled polymerization agents and specialty mercaptans; our 2026 forecast reflects that ongoing expansion.
-
Medium‑term view (through 2032): At an approximate 5.8% CAGR from the 2025 base, cumulative market growth creates a larger addressable opportunity for differentiated products and integrated value chains.
Regulatory dynamics and operational risk
Regulation is a primary driver of commercial risk and capital allocation in the TDM landscape. Key regulatory facts that must inform any 2026 plan include:
-
Occupational exposure limits: In the United States, OSHA maintains a stringent permissible exposure limit for TDM, underscoring the need for robust workplace controls and monitoring.
-
Chemical registrations and compliance obligations: European authorities have documented large volumes of organosulfur registrations, and REACH continues to place organosulfur chemistries under restriction review and authorization pathways.
-
Compliance gap prevalence: Industry indicators show a notable share of global TDM producers face environmental and emissions compliance challenges related to sulfur‑handling and reporting.
Implication for 2026 decisions: executives must budget for compliance capex and embed regulatory scenario planning into capital allocation, M&A due diligence, and supplier selection. Non‑compliance is no longer a localized operations issue — it is a strategic threat to market access in key geographies.
Demand drivers, product differentiation, and feedstock dynamics
Demand for TDM is shaped by three structural vectors:
-
Polymerization control needs: TDM’s role as a chain transfer agent in styrenic and butadiene systems remains the primary industrial application — demand tracks polymer production cycles and formulation complexity.
-
Purity and odor performance: Higher‑purity grades and low‑odor formulations are displacing commodity grades in specialty applications such as coatings, adhesives, and certain engineered polymers.
-
Feedstock and manufacturing platforms: Producers that can flex between different feedstocks and deliver consistent quality are advantaged — product platforms based on different olefinic feeds affect cost, supply security, and impurity profiles.
Strategic takeaway: margin capture in 2026 will be a function of both feedstock flexibility and the ability to commercialize higher‑value product attributes (purity, odor profile, documentation for regulatory/food‑contact/pharma channels where applicable).
Competitive landscape — who matters and why
The TDM market exhibits notable concentration at the top, creating a competitive dynamic where a small number of global chemical majors and specialized regional producers shape pricing, innovation, and contractual norms. Our concentration metrics indicate a highly consolidated supplier base, with the largest firms collectively controlling a substantial portion of market supply.
Core industry participants profiled in the report include:
-
Chevron Phillips Chemical Company LLC (Houston, Texas) — Produces branded TDM used as a chain transfer agent to support SBR, ABS, and other polymer syntheses. Strengths: scale manufacturing, integrated feedstock access, and established commercial channels into major polymer producers.
-
Arkema S.A. (Colombes, France) — Offers both commodity and low‑odor grades for polymerization control. Strengths: formulation expertise, specialty product positioning, and access to European technical markets.
-
ISU Chemical Co., Ltd. (Ulsan, South Korea) — Focuses on high‑purity (>98%) TDM as reaction intermediates for ABS, SBR, and coatings. Strengths: high‑purity manufacturing capabilities and strong regional integration with Asian polymer production.
-
Sanshin Chemical Industry Co., Ltd. (Osaka, Japan) — Specialty producer targeting polymer emulsions and synthetic rubber applications. Strengths: niche technical service, close customer partnerships, and bespoke product development for specialty formulations.
Competitive implications for 2026:
-
Scale vs. specialty trade‑off: Large integrated players will continue to defend share through scale and feedstock cost advantage, while smaller specialized producers compete on purity, odor control, and technical service.
-
Consolidation opportunities: Given the concentration at the top, there is room for strategic bolt‑on acquisitions focused on specialty grades, geographic access, or regulatory compliance capabilities.
-
Customer segmentation: Polymer majors will increasingly bifurcate suppliers — awarding high‑volume contracts to large producers while sourcing differentiated grades from specialists.
Practical, decision‑ready takeaways for 2026 planning
Executives and investment committees should orient 2026 strategies around three parallel initiatives:
-
Risk mitigation and compliance readiness: Prioritize capital projects and operating procedures that address emissions, worker safety, and documentation required for market access, particularly in jurisdictions with REACH‑style authorizations.
-
Value capture through product segmentation: Develop a clear portfolio strategy that separates commodity supply (cost/availability focus) from premium, high‑purity offerings (margin/technical support focus). Investments in downstream application testing and co‑development can justify premium pricing.
-
Supply chain and commercial playbook: Reassess supplier contracts for flexibility on feedstock pass‑throughs, build dual‑sourcing where feasible, and incorporate regulatory exit clauses to limit exposure to territory‑specific compliance changes.
What PW Consulting’s full report delivers
Our comprehensive study is intentionally designed to move beyond headline trends and equip commercial teams with executable materials for 2026. Key deliverables include:
-
Detailed demand forecasts by application and regional markets (2026–2032) with scenario sensitivity to regulatory shifts and feedstock price volatility.
-
Supplier capability maps and a buyer’s playbook that rank vendors on purity, odor profile, compliance posture, and supply continuity.
-
Regulatory risk heatmaps and capex impact models that quantify the balance sheet and operational consequences of compliance pathways.
-
M&A screening templates and integration checklists tailored to specialty vs. commodity acquisition targets.
-
Contract negotiation tools and pricing indexation recommendations that reflect the current cost‑and‑supply structure in TDM value chains.
Note: This preview omits the granular regional and application splits that commercial teams rely on for procurement and market prioritization. Those detailed segmentations, supplier scores, and unit‑level forecasts are included only in the full report to preserve actionable competitive advantage.
Final synthesis — framing 2026 decisions
Entering 2026, TDM represents a maturing chemical class: large enough to demand industrial‑grade supply strategies, yet fragmented enough at the product level to reward technical differentiation. Our top‑line numbers show a clear and steady expansion from 2020 through the 2025 base year and into the forecast period; this creates both growth opportunities and regulatory responsibilities that will determine winners and laggards.
For boards and executive teams, the immediate priorities are clear: secure compliant, cost‑efficient supply; stratify the product portfolio; and accelerate targeted investments (or partnerships) that enable premium positioning in high‑value end uses. For private equity and corporate development teams, the landscape favors acquisitive moves that combine regulatory competence and specialty capability with efficient feedstock access.
Accessing the full intelligence
PW Consulting’s full TDM market study contains the granular segmentation, supplier benchmarking, and financial models needed to operationalize the strategic directions outlined above. To obtain the detailed data, scenario models, and supplier scorecards referenced in this preview, please visit our report page or contact our client services team. The full report is the single resource that converts the 5.8% CAGR and the market scale we identify into concrete, executable decisions for 2026.
For detailed analysis of this topic, please visit the official page: Tertiary Dodecyl Mercaptan (TDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com