

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aluminium Welding Wires Market to Hit USD 630M by 2032 at 5.5% CAGR

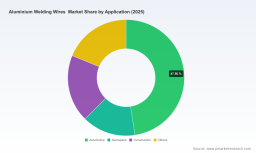
Aluminium Welding Wires Market — Strategic Imperatives for 2026
As aluminium continues to displace heavier materials across transportation, marine and industrial fabrication, the market for aluminium welding wires has matured from a niche consumable into a strategic input with direct consequences for product weight, safety and manufacturing throughput. PW Consulting’s Aluminium Welding Wires Market study (base year 2025; historical 2020–2025; forecast 2026–2032) equips decision‑makers with the market intelligence they need to translate this structural shift into competitive advantage. The study quantifies a market that expanded from roughly USD 325 million in 2020 to USD 432 million in 2025, and which we project to grow at a steady 5.5% CAGR to reach the vicinity of USD 630 million by 2032.
Aluminium Welding Wires Market
Why this report matters for 2026 corporate strategy
-
Input economics and supply assurances are board‑level issues. Recent volatility in aluminium feedstock pricing highlights how raw material dynamics can quickly erode margins and shift sourcing calculus. Our report integrates commodity sensitivity analysis to help procurement, manufacturing and finance leaders model supply shocks and hedging strategies.
Aluminium Welding Wires Market -
Product differentiation now rests on metallurgy and logistics, not just price. Advances in alloy formulations, packaging and certified lot traceability are redefining value in a market where feedability, porosity control and regulatory compliance determine whether a wire is specified in high‑value applications.
Aluminium Welding Wires Market -
Investment and M&A activity requires forward‑looking clarity. A market with mid‑single digit CAGR and moderate concentration among leading suppliers creates both consolidation opportunities and niches for specialized entrants — our analysis highlights where scale matters and where technical differentiation buys premium positioning.
Data‑driven view: size, growth and concentration
PW Consulting’s topline numbers anchor the study. The aluminium welding wires market was approximately USD 432 million in 2025 and is forecast to grow at 5.5% annually through 2032 to approach USD 630 million. These macro trajectories are complemented by concentration metrics that show a market where the largest three players control a meaningful share of demand and the top five expand that lead further — a structure that favors integrated manufacturers with quality systems, technical services and secure logistics.
Market dynamics — what is changing, and why it matters
-
Raw material pressure. Aluminium benchmarks have moved sharply: prices reached USD 3,598.50 per tonne on 5 June 2026, a near‑47% year‑over‑year rise. That kind of input shock forces manufacturers to revisit alloy selection, scrap reclamation, and pass‑through pricing mechanisms. Our scenario models quantify margin and price elasticity outcomes under differing commodity paths.
-
Regulatory and certification premium. End‑users in shipbuilding, aerospace and critical transport systems increasingly demand traceable, standards‑compliant supplies. Suppliers that can certify lot traceability to recognized specifications win preference in risk‑averse procurement processes; our benchmarking assesses the certification readiness of incumbent and emerging suppliers.
-
Product and packaging innovation. Practical innovations — from larger spools that reduce changeover downtime to digital quality‑assurance tools — are changing total cost of ownership. For example, product launches in 2026 have emphasized productivity (longer run‑time spools), digital risk detection (weld defect prevention tools), and alloy reformulation (removal of hazardous additives). We quantify productivity gains and calculate payback periods for these innovations.
-
Health, safety and sustainability drivers. The removal of toxic additives and a move toward fully documented supply chains is not just ethical; it reduces regulatory exposure and downtime risks. The report profiles how health‑driven product changes alter supplier competitiveness and procurement specifications.
What the PW Consulting study contains — practical, actionable modules
-
Market sizing and forecasting (2020–2032) with scenario sensitivity to aluminium price, trade policy and capital investments in end‑use sectors.
-
Supply‑chain heatmap covering feedstock sourcing, continuous casting and finishing capacity, and logistics chokepoints. This includes supplier risk indices and contingency playbooks for procurement teams.
-
Pricing and margin matrix that correlates alloy type, spool format and certification status to realized selling price and gross margins.
-
Commercial playbooks for OEMs, distributors and contract manufacturers, with go‑to‑market approaches by capability (e.g., integrated producers vs. specialty brokers).
-
Competitive intelligence dossiers: company profiles, product portfolios, recent developments and capability maps (see competitive highlights below). These dossiers translate public disclosures and proprietary checks into acquisition targets, partnership candidates and competitive threat assessments.
-
Implementation toolkits: procurement RFP templates, production changeover calculators, and an ROI framework for capital investments in spool equipment and quality analytics.
Competitive landscape — strategic takeaways from leading players
The market’s competitive architecture blends integrated regional manufacturers with global brands supplying certified alloys and consumables. Our competitive analysis synthesizes company disclosures, patent signals and recent product activity to reveal strategic postures.
-
Nexal Aluminum (Canada) : positions itself as a premium, fully integrated North American manufacturer with an emphasis on high‑volume robotic and MIG/TIG applications. Recent updates in 2026 stress feedability and low porosity alloys, and management has highlighted the removal of certain hazardous additives as a differentiator. Strategic implication: a vertically integrated supplier like Nexal can protect customers from feedstock volatility and sell a quality premium to OEMs moving to aluminium‑intensive designs.
-
Berkenhoff GmbH (Bedra, Germany) : known for a wide alloy range and corrosion‑resistant solutions, and now adding digital risk‑prevention tools to its offering. Bedra’s WeldGuard launch signals a move from product supplier to lifecycle risk manager — a model that OEMs and shipyards could adopt to reduce rework costs.
-
Lincoln Electric (United States) : leverages a fully integrated facility and deep service capability to serve shipbuilding and other critical sectors where secure supply and metallurgical support are decisive. Their strength is in trust and technical services rather than price leadership.
-
ESAB (United States) : offers traceable, certified product lots and has brought productivity‑focused spool formats to market. Certification and traceability are important purchase criteria in regulated industries; ESAB converts that requirement into a commercial advantage.
-
NS ARC (United States) : focuses on specialty high‑strength, crack‑resistant alloys for demanding fabrication use cases, playing to niches where metallurgical performance outbids commoditized offerings.
-
Sumitomo Electric Industries (Japan) : brings continuous casting scale and process control to volume shipbuilding and automotive supply chains, offering a different risk profile centered on manufacturing consistency and throughput.
Recent developments as strategic signals
-
Product catalog and alloy positioning by established players signal continued competition on metallurgical differentiation for automotive and marine robotics.
-
Innovations in spool sizes and packaging (aimed at reducing downtime) create an opportunity for distributors and end‑users to reconfigure inventory and material‑handling costs.
-
Digital quality tools that detect welding risks before they occur are emerging as an adjacent service that can be monetized or licensed — suppliers that embed such services into channel agreements create stickier customer relationships.
Strategic recommendations for 2026 decision‑makers
-
For manufacturers: prioritize alloy and process R&D that reduces sensitivity to aluminium price spikes and improves feedability for automation. Evaluate larger spool formats and integrated quality analytics to increase TCO advantage.
-
For OEMs: re‑specify procurement frameworks to include traceability, certified lot numbers and condition‑based changeover triggers rather than purely price‑based awards.
-
For distributors: develop value‑added services (kitting, inventory-as-a-service, on‑site spool change logistics) to differentiate from online commodity channels.
-
For investors and private equity: seek opportunities in specialty alloy processors and digital quality suites that can be bolt‑on acquisitions to established wire manufacturers, capturing margin expansion through services and certification premiums.
How to convert insight into action
PW Consulting’s Aluminium Welding Wires Market study is built as a practical playbook: beyond market projections and competitor snapshots, it contains executable templates for procurement RFPs, a supplier risk matrix, and capital ROI calculators for spooling and automation investments. The research is intentionally selective in public excerpts to preserve commercial advantage — detailed sub‑segment breakdowns, granular regional and application splits, and company‑level revenue estimates are reserved for the full report and bespoke advisory engagements.
Next steps
If your 2026 strategy hinges on securing low‑cost, high‑quality aluminium welding wire supply, or on monetizing product and service innovations in a consolidating market, this study provides the triangulated intelligence you need. Contact PW Consulting for the full dataset, the supplier scorecard, and a tailored workshop to translate insights into a prioritized implementation roadmap.
For detailed analysis of this topic, please visit the official page: Aluminium Welding Wires Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com