

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Resistant Starch Market Poised to Reach USD 261.6M by 2032 with 7.85% CAGR - PW Consulting

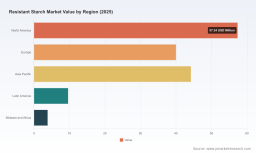
Resistant Starch Market — Strategic Preview for 2026 Decision-Making
As companies prepare budgets and strategic roadmaps for 2026, the resistant starch market presents a compelling mixture of steady volume growth, profitable product adjacencies and meaningful supply-side complexity. PW Consulting’s latest market study (base year 2025) documents a resilient expansion: global market revenue rose from USD 121.8 Million in 2020 to USD 155.0 Million in 2025 and is projected to reach USD 261.6 Million by 2032 under a 7.85% CAGR for the 2026–2032 forecast window. This preview distils the study’s most consequential commercial implications while intentionally omitting the granular segment tables and proprietary splits — the full dataset and models are available in the complete report.
Resistant Starch Market
Why resistant starch matters for 2026 strategy
-
Nutrition-driven demand: Resistant starch has moved from niche functional claims to mainstream reformulation programs — fiber fortification, sugar reduction and glycaemic modulation are now routine brief items for R&D and NPD teams. Ingredient manufacturers who can demonstrate clinical evidence or clean-label positioning capture outsized commercial interest.
Resistant Starch Market -
Profit-margin arbitrage: Manufacturers can command premium positioning in bakery, snacks, clinical nutrition and select beverage formats when resistant starch delivers textural parity while improving fiber content and calorie density. This creates scope for value capture across private labels and branded launches.
Resistant Starch Market -
Supply-chain nuance: The market depends on concentrated feedstock and specialized processing. Commercial buyers will increasingly need contracting strategies and operational flexibility to manage input-price volatility and capacity tightness.
Market trajectory in context
The headline numbers above tell a consistent story: a mid-single-digit-to-high-single-digit compound growth rate as resistant starch moves from formulation adjunct to primary solution in sugar-reduction and fiber-enrichment programs. The transition between 2025 (USD 155.0 Million) and 2026 (USD 163.34 Million) shows near-term momentum; the mid-term pathway to USD 261.6 Million by 2032 reflects both adoption in new applications and incremental price/mix improvements driven by differentiated product portfolios.
Supply dynamics and input risks
-
Feedstock concentration: Corn starch remains the dominant industrial feedstock for resistant starch production, representing the largest share of global starch output. This concentration creates a direct linkage between corn-market dynamics and resistant-starch supply economics.
-
Price sensitivity: Transaction prices for corn starch in 2025 were observed in the range of USD 1.64–1.79 per kg across major suppliers. Even modest shifts in corn wet‑milling demand can transmit to raw material cost curves; short-run contractions in wet-milling volumes have historically influenced national corn prices by notable cents-per-bushel ranges.
-
Regulatory overlay: Air emissions and particulate regulations are non-trivial for wet‑milling and starch processing facilities. Recent enforcement actions and regulatory settlements in the sector illustrate a compliance-cost vector that buyers and producers must account for in site selection, contracting and total cost of ownership analyses.
-
Capacity investments: New facilities and expansions announced in 2025 signal supplier intent to meet growing food-and-beverage demand; however, lead times for investment and process qualification mean that capacity tightness may persist in early 2026 for certain formats and grades.
Competitive landscape — what incumbents are doing
The market structure is moderately concentrated: the three largest players account for a meaningful share of industry revenues while the five largest approach a dominant position. That concentration delivers advantages in scale, formulatory know-how and channel relationships, but it also creates competitive openings for specialists and regional players with narrow technical platforms.
-
Cargill, Incorporated — leveraging proprietary product families across high-amylose and modified tapioca chemistries, Cargill is targeting both mainstream food applications and higher-value pharmaceutical/prebiotic segments. Recent product introductions emphasize prebiotic benefits and multi-market positioning.
-
Ingredion Incorporated — focused on clinically-backed launches and multi-format portfolios, Ingredion’s activity underscores the commercial premium for substantiation in glycaemic response and sugar-reduction applications. Their 2025 launches further signal the commercialization pipeline for next‑generation resistant starches.
-
Archer Daniels Midland (ADM) — ADM brings large-scale starch processing and texturization capabilities, positioning resistant starch as a functionality play for texture and stability in complex formulations.
-
Tate & Lyle — building on clean-label and specialty starches, Tate & Lyle is expanding organic and low-FODMAP variants and executing capacity upgrades to support demand for differentiated, label-friendly solutions.
-
Regional and specialist players — Grain Processing Corporation, MGP Ingredients and dedicated prebiotic producers are exploiting niches in bakery, gluten-free and gut-health formulations, respectively. These firms often offer agile co‑development models attractive to product teams pursuing rapid shelf trials.
Collectively, incumbent investments — from organic portfolio extensions to new production facilities — are crystallizing a two-speed market: large suppliers consolidating breadth and scale, and specialist innovators capturing technical niches and clinical-claims leadership.
Recent commercial signals (what 2025 activity implies for 2026)
-
Product launches backed by clinical evidence are accelerating adoption in sugar‑reduced and clinical nutrition segments. Expect buyers to prioritize ingredients with human-data packages in supplier selection criteria.
-
Portfolio and capacity expansions announced in 2025 indicate supply-side responsiveness; however, qualification cycles at co‑packers and OEMs mean that commercial availability for new grades will be staggered across 2026.
-
Regulatory and environmental compliance events in the sector emphasize the need for supplier due diligence beyond price — assessing permit status, emissions mitigation investments and forward CAPEX plans will be essential for contract risk management.
Strategic imperatives for 2026 decisions
-
Lock-in differentiated supply: For brands planning multi-market launches, prioritize multi-year supply agreements with volume-flex provisions and technical support for scale-up to mitigate qualification delays.
-
Invest in clinical and sensory proof-points: Product claims tied to glycaemic response, prebiotic benefits or digestive tolerance materially increase commercial acceptance — either fund those studies or partner with suppliers that have them.
-
Model feedstock risk into pricing: Use scenario-based cost models reflecting realistic ranges for corn starch and wet‑milling demand shocks; require pass-through terms or hedging clauses in supplier contracts where appropriate.
-
Pursue bolt-on M&A selectively: Given the market’s concentration and the value of proprietary grades, acquisitive strategies targeting specialty producers (R&D-rich but capacity-limited) can accelerate capability building.
-
Build formulation bridges: R&D playbooks that translate resistant starch grades into production-line process windows and consumer sensory outcomes reduce launch risk and shorten time-to-shelf.
Risk scenarios to stress-test
-
Raw-material deflation or substitution that compresses supplier margins and triggers competition on price rather than differentiation.
-
Stricter environmental regulation or permit revocations that reduce regional processing capacity and re-route trade flows, elevating logistics cost and qualification timelines.
-
Scientific or regulatory reversals around health claims that would require reformulation or repositioning of existing products.
What the full PW Consulting report delivers
PW Consulting’s comprehensive study goes beyond market sizing. For decision-makers planning 2026 actions, the report provides:
-
A validated market-sizing model (historical 2020–2025 base year 2025; forecast 2026–2032) with scenario toggles for volume, price and mix.
-
Commercially actionable supplier benchmarking including product-grade matrices, capacity maps, technology readiness levels and recent capex activity.
-
Go-to-market playbooks for manufacturers and brand owners — pricing mechanics, contract templates, co‑pack qualification checklists and launch timetables.
-
Formulation impact tools — recipe-level cost and sensory calculators to compare resistant starch substitution pathways versus alternative fibers.
-
Regulatory and claims guidance by major jurisdiction and pathways to substantiate physiological claims for glycaemic modulation and digestive benefits.
-
Investor and M&A intelligence — target screening, valuation multiples observed in adjacent specialty ingredient deals, and diligence checklists focused on supply and regulatory exposure.
-
A client-ready slide deck and an Excel model licensed for internal use, enabling bespoke scenario analysis for procurement and R&D teams.
Concluding perspective
For 2026 strategy cycles, resistant starch is no longer an experimental ingredient — it is a strategic lever for nutrition-led product differentiation, cost-in-use optimization and premiumization. The market’s steady CAGR and projected doubling in revenue potential over the next seven years create both opportunities and obligations: secure differentiated supply, insist on clinical and technical evidence, and embed feedstock risk into commercial agreements.
PW Consulting’s full report provides the granular segmentation, supplier-level data and Excel models that companies need to translate these implications into executable 2026 plans. For firms that intend to launch or scale resistant-starch-based products next year, the cost of delayed supplier qualification or absent clinical evidence now materially exceeds incremental procurement savings. The complete study is available on our website for organizations seeking the underlying datasets, proprietary segmentation and implementation tools that inform confident, time-sensitive decisions.
For detailed analysis of this topic, please visit the official page: Resistant Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com