

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Orthotics Insoles Market to Reach USD 338.79M by 2032 at 6.9% CAGR

Orthotics Insoles Market 2026: Strategic Imperatives for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a high-level primer on our latest Orthotics Insoles Market research (base year: 2025). This briefing outlines why our study is essential for executive teams planning resource allocation, product roadmaps, and M&A activity in 2026. It showcases the analytical depth that underpins the full report while intentionally withholding detailed segment-level datapoints—those actionable tables and model outputs are available in the complete publication.
Orthotics Insoles Market
Executive snapshot: why this market matters in 2026
The orthotics insoles market has moved from a niche clinical product set into a dynamic cross-section of medical devices, consumer wellness, and digital health. On a macro basis, the market grew from under USD 170 Million in 2020 to approximately USD 215 Million in 2025 (USD Million, base year 2025), and is projected to expand at a compound annual growth rate (CAGR) of 6.9% through our forecast window (2026–2032). By 2032, the market is expected to exceed USD 330 Million. These topline dynamics create an attractive environment for both product innovators and supply-chain integrators, but the pace of value capture will depend on strategic positioning across clinical validation, regulatory access, and channel execution.
Orthotics Insoles Market
Key market dynamics driving 2026 decisions
- Clinical-to-consumer convergence: Medical-grade functionality (pressure redistribution, offloading, diabetic foot prevention) is increasingly expected in premium consumer products. Providers and manufacturers that can credibly straddle both regulated medical segments and direct-to-consumer channels can expand addressable demand and margin capture.
- Regulatory and reimbursement gravity: Reimbursement frameworks and medical coding materially affect commercial viability for supplier segments focused on therapeutics. For instance, current U.S. pathways (including HCPCS coding conventions and Medicare policies for therapeutic shoes and inserts) mean go-to-market strategies must be aligned with supplier enrollment, prescription workflows, and billing frequency constraints.
- Material & manufacturing differentiation: Advances in thermoplastics, EVA formulations, and composite carbon fiber manufacturing are reducing unit cost variability and enabling lighter, higher-performance insoles. At the same time, additive manufacturing and CAD-driven production are compressing lead times for customized solutions, shifting competition from pure cost to time-to-fit and data-enabled personalization.
- Channel fragmentation and concentration: The market exhibits a mix of global brand leaders, regional specialists, and vertically integrated OEM/ODM producers. While top firms command meaningful recognition, overall concentration remains moderate—making strategic consolidation and selective vertical integration attractive options for acquirers seeking scale or margin improvement.
Segmentation & opportunity themes (what you need to map)
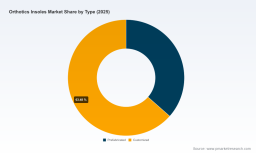
Our full study breaks the market into the familiar lenses—type (prefabricated vs. customized), material composition, application (medical, sports & athletics, personal/wellness), and region. Rather than reproducing segment share tables here, consider the strategic implications that emerge across these blades:
Orthotics Insoles Market
- Prefabricated vs. Customized: Prefabricated products scale through distribution, retail, and e‑commerce; customized insoles command higher ASPs and clinical stickiness. Identify which model aligns with your IP, manufacturing footprint, and sales channels before committing to factory investments.
- Material mix strategy: Thermoplastics and advanced composites are warping the cost-performance curve. Material selection is a lever for differentiating on weight, durability, and thermoformability—critical for athletes and post-surgical rehabilitation alike.
- Application-led go-to-market: Medical channels demand clinical evidence and reimbursement navigation; sports and wellness channels prioritize performance metrics and brand partnerships. Hybrid product strategies need separate commercialization playbooks for each funnel.
- Geo-market entry sequencing: Market access is not only about demand density but also regulatory pathways, supplier ecosystems, and payer structures. A phased entry that prioritizes regulatory-compliant product families can protect margin and learning cycles.
Competitive landscape: profiles and strategic levers
The competitive field includes long-established clinical suppliers, specialized technology firms, and large-scale OEMs—each pursuing distinct strategies that inform tactical responses by challengers and incumbents alike. Our report includes a supplier matrix and capability scoring; below is an analytical synthesis of representative players and their strategic positioning:
- FootMaster (China): A wholesale manufacturer with long-standing CE and ISO credentials. Strengths: scale in volume production, breadth of SKU families, and cost competitiveness. Strategic risk: margin pressure if shifting to branded premium segments without clinical differentiation.
- Ideastep (China): An OEM/ODM focused on custom, medical-grade insoles with both FDA and CE clearances. Strengths: regulatory credentials, diabetic/orthopedic specialization, and presence at clinical industry forums. Strategic opportunity: monetizing IP through licensing and co-branded clinical programs.
- 3BU Technology (China): CAD-to-production OEM/ODM with ISO 9001 certification and a focus on sports and functional use. Strengths: rapid prototyping and vertical manufacturing. Strategic lever: integration of digital foot-scanning ecosystems to move up the value chain.
- Foamwell (China): International-trade oriented supplier with multi-country production bases and social/environmental certifications. Strengths: diversified supply footprint and compliance credentials; this lowers geopolitical production risk for global buyers.
- Össur (Iceland): Clinical device provider with motion lab capabilities and custom orthotics. Strengths: premium clinical brand and strong clinician relationships; ideal for partnerships with healthcare systems and rehabilitation centers.
- Superfeet (US): Premium prefabricated brand with broad retail distribution. Strengths: channel reach and consumer brand loyalty; faces pressure from digitally-enabled custom players targeting the same premium consumer segment.
- Orpyx Medical Technologies (Canada): Developer of sensory insoles with regulatory registrations focused on diabetic foot management. Strengths: tech-enabled clinical differentiation—recent product launches underscore the rise of "sensory + intervention" devices in high-risk patient subsets.
- FootBalance Korea: Specializes in custom 3D orthotics and post-surgery rehabilitation soles. Strengths: advanced scanning and rehab-centered product design, positioning it well for partnerships with orthopedic clinics and sports medicine networks.
Recent competitive moves underscore two themes: (1) product innovations that tie clinical efficacy to consumer usability (e.g., next-gen sensory insoles for ulcer prevention), and (2) OEM/ODM players amplifying their certification portfolios and catalog visibility at major industry congresses. These trends raise the bar on clinical evidence, supply integrity, and service delivery models.
Regulation, reimbursement and certification—practical implications
- Reimbursement navigation: In the United States, Medicare coverage rules—and related HCPCS coding—affect procurement timing and margin realization for therapeutic insoles. Firms pursuing medical channels should model billing frequency, supplier enrollment timelines, and coinsurance impacts into commercial forecasting.
- Regulatory posture: FDA and CE pathways remain critical for medical claims. Market entrants should map their product families to device classifications early, and plan clinical evidence generation accordingly to avoid go-to-market delays.
- Certification as table-stakes: ISO 13485/9001 and other third-party certifications are increasingly required by institutional buyers and distribution partners; possession of these credentials shortens procurement cycles and reduces perceived risk.
What the full PW Consulting report delivers (practical outputs)
Our full research package is designed for C-suite, corporate development, product, and commercial teams who need executable insights in 2026. Deliverables include:
- Comprehensive market model (historical 2020–2025; forecast 2026–2032) with scenario sensitivity (price, reimbursement, and adoption curves).
- Go-to-market playbooks tailored to the medical, sports, and consumer channels—covering pricing, distribution, and sample clinical evidence packages.
- Supplier benchmarking and cost stack analysis for OEM/ODM selection, including capacity maps and certification overlays.
- Regulatory and reimbursement decision trees with milestone timelines for major markets, and a coding/reimbursement mapping for therapeutic product families.
- M&A screening: short-listing of potential acquisition targets by capability gaps (manufacturing scale, clinical tech, channel access) and a pre-built valuation sensitivity model.
- Risk heatmap and integration playbook addressing supply-chain resilience, certification continuity, and post-deal integration challenges.
Note: while this primer highlights thematic findings, our detailed segmentation tables and the accompanying regional/application share analyses—critical for tactical decisions—are reserved for the full report. This ensures that decision-ready numbers and vendor scorecards are accessible to serious buyers and subscribers.
How to use these insights in 2026 planning cycles
- Product roadmap prioritization: Use the report’s material-performance and usage-cluster matrix to decide where to invest R&D—e.g., sensory integration for high-risk medical patients vs. lightweight composites for athletic lines.
- Commercial channel allocation: Allocate sales and marketing spend to channels where reimbursement and brand premium converge, and reserve direct-to-consumer experiments for differentiated, data-enabled products.
- M&A and partnership scouting: Apply our candidate filters to identify targets that provide missing capabilities—custom manufacturing, regulatory clearance, or distribution breadth—with clear earnout structures tied to integration milestones.
- Risk mitigation: Implement certification audits and multi-sourcing strategies outlined in our supplier playbook to immunize revenue plans from regulatory and production shocks.
Concluding perspective
The orthotics insoles market in 2026 is shaped by clinically-driven product innovation, evolving reimbursement realities, and a supply base that mixes global scale with regional specialization. Our market model—capturing the 2020–2025 historical base and projecting forward at a 6.9% CAGR—shows a market with meaningful runway to 2032, but with winners determined by execution in regulation, clinical validation, and channel orchestration.
For executive teams evaluating entry, expansion, or consolidation, PW Consulting’s full Orthotics Insoles Market report provides the quantitative backbone, tactical playbooks, and vendor intelligence needed to convert strategic intent into commercial outcomes. To access the detailed segment tables, vendor scorecards, and the full set of actionable templates, please refer to our subscription portal or contact our research desk for an executive briefing.
For detailed analysis of this topic, please visit the official page: Orthotics Insoles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com