

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Honeycomb Sandwich Market to Hit USD 344.8M by 2032 at 6.98% CAGR

Honeycomb Sandwich Material Market: Strategic Imperatives for 2026 Decision‑Making
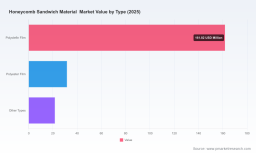
As global supply chains reset and materials technology converges with increasingly stringent safety and performance standards, honeycomb sandwich materials have moved from a niche engineering commodity to a strategic input across aerospace, semiconductor manufacturing, construction, and advanced packaging. PW Consulting’s new market study—anchored on a 2025 base year—projects continued expansion at a compound annual growth rate of 6.98% through the 2026–2032 forecast window, taking the market from roughly USD 215 million in 2025 to an expected USD 345 million by 2032. For executives making 2026 capital allocation, sourcing, and product road‑map choices, the findings are immediately actionable: the upside is meaningful, but the pathway is uneven and requires calibrated strategic responses.
Honeycomb Sandwich Material Market
Why this report matters for 2026 decisions
- Translate growth into profit: Understand where structural demand will justify capacity expansion versus where margin will be squeezed by raw‑material inflation and commoditization.
- De‑risk supply exposure: Identify which sourcing levers mitigate volatility in key inputs and which supplier relationships materially reduce lead‑time and qualification risk.
- Prioritize regulatory and certification investment: Map certification timelines (FST, ISO testing, and sector‑specific standards) to product launches and procurement cycles.
- Inform M&A and partnership choices: Distinguish tuck‑in targets, licensing plays, and co‑development partners that accelerate entry into high‑growth end markets.
What PW Consulting’s Honeycomb Sandwich Material study delivers
- Market sizing and a robust forecast model (2026–2032) with scenario sensitivity to raw material trajectories and demand shocks.
- Supply‑chain maps and supplier heat‑maps across raw materials, core production, surface skins, and adhesive systems.
- Regulatory and compliance matrix: actionable checklist (FAR, EN, SOLAS, ISO 12579, GB/T, ECSS guidance) aligned to application cohorts.
- Technology and materials road‑map showing substitution risks, TRL (technology readiness level) curves, and time‑to‑qualification for thermoplastic, aluminum and composite cores.
- Competitive benchmarking and strategic profiles of leading and regional players, plus an M&A/partnership tracker updated through Q1–Q2 2026.
- Commercial playbooks: go‑to‑market templates, procurement negotiation scripts, and scorecards for supplier qualification.
- Plug‑and‑play Excel model and executive dashboards for scenario planning—built for boardroom stress‑testing.
Key market dynamics shaping 2026
The market’s near‑term trajectory is governed by three overlapping dynamics: raw‑material cost swings, regulatory complexity, and application concentration in high‑performance segments.
Honeycomb Sandwich Material Market
- Raw‑material pressure and sourcing realignment: Aluminum foil costs experienced significant inflationary pressure during 2022–2024 (industry sources indicate mid‑teens to low‑double‑digit percentage moves), driven by energy and trade policy shifts. Suppliers have reacted by diversifying upstream sourcing and, in some cases, redesigning core and face‑sheet laminates to reduce aluminum content or shift to polymer films. Our sensitivity scenarios show that sustained elevated aluminum prices materially compress margins for traditional aluminum honeycomb products and accelerate adoption of thermoplastic and film‑based cores where performance trade‑offs are acceptable.
- Regulatory and qualification hurdles: End markets—particularly aerospace and mass transit—continue to require rigorous flame, smoke and toxicity (FST) compliance and mechanical qualification (e.g., ISO 12579). Regional standards and tightening VOC limits in adhesive systems (notably in China) are forcing reformulation toward water‑based adhesives and earlier engagement with certification bodies. Additionally, aerospace supply rules such as the ECSS handbook on inserts and joints impose design constraints that must be addressed at the prototyping phase, increasing time‑to‑market if not anticipated.
- Application concentration and margin divergence: While demand from mature industries remains steady, a large proportion of near‑term incremental demand is concentrated in a few high‑value applications—advanced aerospace structures, semiconductor wafer handling and IC packaging. These segments demand bespoke specifications, higher testing, and tighter supplier chains; they also support premium pricing for qualified suppliers. Conversely, commoditized applications see price pressure and require scale or vertical integration to sustain margins.
Competitive landscape — strategic positions to watch
The honeycomb sandwich market remains comparatively fragmented; top incumbents account for a small share of total volume, leaving room for regional specialists and technology licensors to influence outcomes.
Honeycomb Sandwich Material Market
- EconCore N.V. (Leuven, Belgium): With the ThermHex continuous thermoplastic honeycomb process, EconCore is pushing a licensing and modular manufacturing model that lowers unit costs for thermoplastic cores and accelerates localized production. Their visibility at industry shows and licensing strategy positions them as a catalyst for wider thermoplastic adoption—particularly where design cycles favor rapid prototyping and part consolidation.
- Hexcel Corporation (Dublin, California, USA): The company remains the dominant force in aerospace‑grade honeycomb cores and sandwich structures. Recent activities—trade show showcases, aerospace supplier awards, and investment in an applications center with NIAR—signal a deliberate strategy to lock in aerospace platform programs and accelerate qualification cycles for next‑generation composite sandwich structures.
- The Gill Corporation (Covina, California, USA): Specializing in aluminum cores and sandwich panels, Gill maintains strength in industrial, rail and marine segments where durable, metallic cores remain preferred. Their product breadth keeps them competitive in regulated markets requiring metal‑based fire performance.
- Alucoil, Corex, Liming and regional specialists: These producers combine localized manufacturing, customization capabilities and standards participation to serve architectural and industrial construction, rail and marine. Chinese manufacturers are increasingly influential through participation in national standards and export strategies—an important dynamic for firms evaluating competitive pressure and qualification timelines in Asia.
- Pacific Panels and Samia Canada: Focused on custom and validated assemblies for cleanrooms, display and construction, these players underscore a market where application‑specific integration (skins, adhesives, finishing) offers differentiation beyond core geometry.
Recent corporate signals are meaningful: EconCore’s presence with ThermHex licensing at major trade events is accelerating discussions around decentralized core production; Hexcel’s supplier accreditation and the NIAR applications center represent a strategic push to own qualification pathways for aerospace tier programs. For buyers and investors, those moves alter the calculus of supplier selection and the value of in‑house testing capabilities.
Strategic playbook for 2026 (prioritized actions)
- Lock in critical inputs via blended contracts: Use a mix of short‑dated index‑linked contracts and strategic long‑term supply agreements to balance price risk and availability for aluminum foil and high‑performance polymer films.
- Invest in certification early: For any product targeting aerospace, rail or semiconductor handling, allocate budget for FST and ISO mechanical testing in Q3–Q4 2026 to avoid year‑long qualification delays.
- Pursue modular, regionalized manufacturing: Favor licensing or partnership models (e.g., ThermHex) for faster local capacity ramp and lower logistics risk—especially where lead times and trade friction add cost.
- Differentiate through systems integration: Move up the value chain by offering integrated sandwich assemblies (cores + skins + certified adhesives), which capture higher margins and create stickier customer relationships.
- Target high‑value application corridors: Prioritize business development in semiconductor wafer handling and aerospace interior/structural programs where certification barriers protect pricing.
- Scan for M&A selectively: Seek bolt‑on targets that fill capability gaps (testing, automated lamination, regional footprint) rather than generalist volume plays in commoditized segments.
Methodology snapshot — how our numbers were built
The report synthesizes historical shipment data (2020–2025), vendor price indices, primary interviews with manufacturers and OEMs, and end‑market demand models. We ran sensitivity scenarios on raw‑material inflation and application adoption rates to produce a central forecast (6.98% CAGR) and conservative/optimistic tails. The market concentration analysis used public filings, primary supplier surveys and trade data to map competitive intensity and opportunity pockets.
To preserve strategic value for clients, we have deliberately withheld exhaustive regional and application‑level splits in this executive overview. The full report contains detailed regional and application segmentation, downloadable data tables, and an interactive model that allows you to stress‑test outcomes for specific procurement strategies and capital investments.
Next steps — what to read and who to call
If your 2026 priorities include capacity decisions, supplier consolidation, certification spending, or M&A in honeycomb sandwich materials, PW Consulting’s full study provides the granular segmentation and playbook templates your team will use to execute. The window to secure favorable supplier terms and align qualification roadmaps is narrow—planning decisions taken in 2026 will determine market share and margin outcomes for the next innovation cycle.
Access the full research package for the complete data tables, regional and application splits, supplier heat‑maps, and the scenario model. Our team is available for executive briefings, custom sensitivity runs, and discrete diligence support to accelerate your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Honeycomb Sandwich Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com