

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Metallurgical Coke Market at USD 212.5B in 2025, 3.68% CAGR to 2032

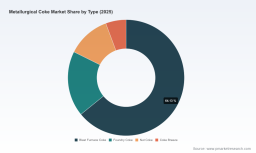
Metallurgical Coke Market: Strategic Outlook for 2026 Decision Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, executive-level introduction to our latest Metallurgical Coke Market study. This briefing is designed to equip senior management, procurement leads, corporate development teams, and industrial investors with the strategic context they need to prioritize decisions for calendar-year 2026 — and to understand why deeper, transaction-ready intelligence from the full report will be essential to execute those decisions with confidence.
Metallurgical Coke Market
Market snapshot — headline macro view
The metallurgical coke market has shown steady expansion through the early 2020s. Our base-year calibration is 2025, when global industry revenues approached USD 212.5 Billion. Historical momentum between 2020 and 2025 reflects a combination of resilient demand from primary metallurgical end-users and recovery in capital-intensive supply chains. Looking forward, our modeled baseline projects a continuation of mid-single-digit expansion through the 2026–2032 forecast window, with a compound annual growth rate of 3.68% and an end‑period market size that reflects a material, though measured, expansion of the addressable market.
Metallurgical Coke Market
Near-term year-to-year dynamics are not uniformly linear — the market exhibits episodic upticks tied to capacity restarts, trade-policy shifts, and episodic supply disruptions — and our forecast layers those drivers into scenario analyses. For 2026, PW Consulting models a modest growth inflection from 2025 levels, followed by periods of stronger expansion where regional restarts and merchant trade flows align with steel sector demand cycles.
Metallurgical Coke Market
Why this study matters for 2026 corporate strategy
- Procurement and contract strategy: With a market characterized by moderate growth and meaningful upstream concentration, the structure of off-take agreements, pricing formulas and indexation will materially influence margin performance. Companies that proactively redesign contract tenors and index clauses in 2026 will capture cost advantages.
- Capital allocation and plant economics: Regulatory-driven compliance costs, retrofits, and end‑of‑life decisions for aging coke ovens require calibrated investment timing. Our analysis quantifies payback sensitivities across retrofit versus replacement options under alternative regulatory and pricing scenarios.
- M&A and JV targeting: Consolidation signals are persistent where merchant producers and integrated steelmakers seek feedstock security or merchant-market exposure. The report identifies tactical approaches to value accretion in bolt-on acquisitions and strategic JVs without disclosing our proprietary target rankings in this preview.
- Risk management and hedging: Volatility in coking coal inputs and episodic trade-policy shocks argue for a revised hedging playbook in 2026 that pairs physical coverage with financial instruments and supplier diversification.
Key market dynamics shaping 2026 decisions
- Feedstock and supply-chain tightness: Metallurgical coal remains the single most consequential upstream input. In markets such as the U.S., metallurgical coal consumption for coke-making remains material and supply dependencies influence merchant coke pricing and availability. Companies that map coal-to-coke cost curves and secure coal-to-coke integrated pathways will enjoy durable margin resilience.
- Regulatory tightening: Recent rulemaking has increased emissions compliance obligations for coke ovens in several jurisdictions, raising operating and capital costs for existing assets. These regulatory changes compress margins for high-emission assets and accelerate decision points on retrofits, idle-to-retire choices, or investments in emissions-control technology.
- Trade policy and import controls: Country-specific measures introduced in 2025 — aimed at boosting domestic self-sufficiency — have already altered trade flows and merchant inventory strategies. Import restrictions and quotas change arbitrage windows and can produce short-term regional price dislocations that persist into 2026 unless matched by new supply commitments.
- Decarbonization and technology pathways: The coke value chain faces growing pressure to reduce scope 1 and scope 2 emissions. Emerging low‑carbon coke production approaches and electrification-adjacent investments present a strategic fork for market participants: retrofit existing assets or secure low‑carbon supply via procurement and offtake contracts.
Competitive landscape — practical implications for partners and rivals
The metallurgical coke market demonstrates moderate concentration: the top three companies account for a majority share of merchant and integrated supply, with the top five expanding that concentration further. This structure gives leading producers meaningful pricing influence while leaving space for nimble merchant players to capitalize on localized demand dislocations.
- Integrated steelmakers (example profiles): Integrated producers that operate their own coke-making assets combine feedstock security with internal demand capture. These firms face trade-offs between selling surplus product into merchant markets and retaining supply for captive blast furnace operations. Their strategic choices in 2026 around internal allocation will materially affect merchant availability.
- Independent merchant producers (example profiles): Independent coke suppliers with diversified plant portfolios and export capabilities remain pivotal to steelmakers and foundries without captive supply. Their strategic posture in contracting — particularly with longer-term offtakes and pricing mechanisms — will determine their resilience to raw-material volatility.
- Regional single-supplier contexts: In certain jurisdictions, single large producers anchor local industrial ecosystems. These players can act as strategic chokepoints for regional metals and mining operations, influencing local bargaining dynamics and downstream investment behavior.
- Recent commercial moves: Strategic supply agreements executed in late 2025 reflect an industry preference for multi-year supply security; such contracts are shaping merchant availability going into 2026 and reducing near-term spot liquidity.
What PW Consulting’s full report provides — the operational toolkit
This research is built as a decision-support product for 2026 execution. It is explicitly practical, not academic. The full deliverable includes:
- Dynamic market-sizing and demand-supply models (2020–2032) with scenario toggles and downloadable model files so clients can run their own stress tests;
- Cost-curve benchmarking for coke production, inclusive of coal input pricing, plant-specific operating cost sensitivities, and break-even maps for retrofit versus replacement;
- Supplier scorecards and a negotiation playbook that align counterparty risk, environmental compliance status, and logistics exposure to contract structuring recommendations;
- Regulatory impact assessments and compliance roadmaps that translate recent rule changes into capital and operating cost forecasts across jurisdictions;
- Transaction readiness materials: valuation levers for M&A, a buy-side diligence checklist, and an integration value-capture template;
- Proprietary regional flow maps and merchant-trade monitoring tools to identify arbitrage windows and inventory risk pockets (note: core segment-level tables and granular regional/applicational splits are available in the full report portal only);
- Executive briefings and scenario-based decision playbooks tailored to steelmakers, independent producers, commodity traders, and financial sponsors.
Scenario outlook and recommended playbook for 2026
PW Consulting models three primary scenarios for the 2026 strategic horizon: baseline (moderate growth and stable trade flows), constrained-supply (episodic outages and tighter merchant availability), and accelerated-decarbonization (policy-driven capex and market premium for low-carbon supply). Each scenario produces distinct implications:
- Baseline: Prioritize renegotiation of existing indexation clauses and extend selective medium-term offtakes to smooth price exposure while maintaining optionality to capture upside in spot markets.
- Constrained-supply: Secure physical supply via diversified suppliers and strategic inventory agreements; accelerate investments in captive feedstock integration; reassess counterparty credit in supply contracts.
- Accelerated-decarbonization: Fast-track low-carbon procurement strategies and prioritize retrofits where economically viable; consider premium pricing strategies for lower-emissions supply or partner in low-carbon technology pilots.
For 2026, decision-makers should implement a two-layered approach: (1) tactical near-term moves to hedge against supply volatility and regulatory surprises; (2) strategic repositioning to capture structural value through vertical integration, targeted M&A, and low-carbon differentiation.
Conclusion — how to use this briefing
This introduction distills the strategic contours that will most influence metallurgical coke markets and corporate outcomes in 2026. It demonstrates our analytical depth while reserving the proprietary, segment-level intelligence that operational teams require to finalize contracts, capital budgets, and transaction plans. For companies preparing bidding strategies, procurement redesigns, or acquisition screening in 2026, the full PW Consulting study provides the interactive models, supplier-by-supplier diligence, and regulatory impact quantification necessary to move from strategy to execution.
To access the complete dataset, segmented forecasts, supplier scorecards, and downloadable financial models that underpin these strategic recommendations, please refer to the full report on our website — where the actionable tables and granular intelligence are provided to licensed subscribers and transaction clients.
For detailed analysis of this topic, please visit the official page: Metallurgical Coke Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com