

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Neo & Challenger Banks set for 7.95% CAGR through 2032

Neo and Challenger Bank Market 2026: Strategic Primer for Decision-Makers
As PW Consulting’s senior strategy team, we present an executive primer for leaders preparing 2026 strategic moves in the Neo and Challenger Bank market. This market is no longer a fringe experiment — it is a structural element of the global banking landscape. Our latest study, built on a 2025 base and a seven-year forecast, synthesizes market sizing, competitive positioning, regulatory dynamics, and hands-on playbooks that translate insights into actionable choices. This article outlines why the study matters for 2026 decisions, highlights the forces shaping value capture, and teases the targeted operational guidance you’ll find in the full report.
Neo and Challenger Bank Market
Executive snapshot: why this market matters in 2026
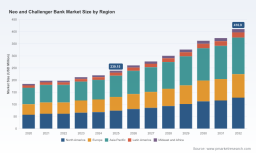
Between 2020 and 2025 the Neo and Challenger Bank sector demonstrated steady expansion, and our forecast projects a sustained compound annual growth rate (CAGR) of approximately 7.95% through the 2026–2032 period. Put simply: this is a growing, maturing market where scale economics begin to matter more than novelty. For corporates, incumbents, fintech investors, and technology vendors, that means opportunities to consolidate, to vertically integrate services, and to rationalize portfolios around profitable product lines.
Neo and Challenger Bank Market
Importantly, the market exhibits moderate concentration: the top three providers account for roughly one-third of industry revenue, while the top five approach the mid-forties in share. That mix — meaningful leader advantage but room for challengers — creates a competitive calculus where smart positioning and focused capabilities unlock disproportionate returns.
Neo and Challenger Bank Market
What 2026 strategic choices look like — four immediate themes
- Scale vs. specialization: As growth normalizes, the value of scale (distribution, product breadth, payments rails) competes directly with the value of specialization (SME lending, embedded banking, crypto-native services). Boards must decide whether to fund scale-up or double-down on narrow, high-margin niches.
- Regulatory arbitrage and compliance as product: Regulatory regimes and supervision intensity differ across jurisdictions, but the trend is clear: digital-only banks increasingly face scrutiny on deposit costs, liquidity modelling, and operational resilience. Firms that operationalize regulatory compliance into a repeatable product — compliance-as-a-service for partners or hardened tech stacks for rapid licensing — will convert regulatory cost into a competitive moat.
- Profitability pathways: Higher funding costs and deposit repricing have compressed margins for many digital-first banks. 2026 is the year firms either pivot to more stable revenue streams (credit card interchange, B2B balance sheet services, payments clearing partnerships) or demonstrate clear unit economics on customer acquisition and lifetime value.
- M&A and partnership calculus: With mid-level concentration and differentiated capabilities across geographies, 2026 will be an inflection point for bolt-on acquisitions and strategic alliances. Well-timed M&A can accelerate market entry or augment underserved product vectors faster than organic investment.
Market dynamics and regulatory context
The macro picture is multidimensional. Across Europe, regulators have catalogued an expanding cohort of digital-only banks and tracked growing market share (notable growth in share of sector assets over recent years). At the same time, euro-area digital banks have accumulated substantial balance-sheet presence — a reminder that digital challengers are now material counterparties in the banking system. Central banks and supervisors are actively reassessing deposit cost pass-through, macroprudential buffers, and operational oversight for purely digital players.
In the United States, market structure complexity — thousands of chartered banks, diverse state-level rules, and an entrenched branch network — raises market entry friction and elevates the premium for go-to-market sophistication. New entrants in the U.S. must combine product innovation with granular regulatory navigation to win scale.
Collectively, these dynamics mean that a 2026 strategy cannot be product-first only; it must integrate regulatory read-ahead, funding strategy, and operational resilience into product design. Firms that treat regulation as an input to product development — rather than an afterthought — gain a durable edge.
Competitive landscape: who matters and why
Our research maps a diverse set of incumbents and challengers across geographies and business models — from digital-native mass-market players to focused SME lenders and platform incumbents expanding into banking. Key active participants include:
- Nubank (São Paulo): A digital-first regional champion that demonstrates how scale in Latin America can be achieved through simple UX, localized products, and broad financial-service bundling.
- Revolut (London): A feature-rich product leader focused on multi-currency, payments, and international expansion — illustrative of the cross-border fintech playbook.
- Monzo, Starling, Tandem, N26, Bunq (Europe): Diverse European challengers that have each chosen distinct mixes of retail, business, and specialty services — together they reveal the plural routes to profitability in regulated markets.
- Chime, SoFi, Robinhood, Ally (United States): U.S.-based digital operators that spotlight the necessity of broad product ecosystems (investing + lending + accounts) to lift unit economics in a crowded and costly market.
- Judo Bank (Australia): An example of a challenger focusing on SME banking and relationship-based lending in a domestic market.
Recent strategic moves underscore the second-order dynamics your 2026 decisions must consider: product integration (crypto trading features and card-to-card rails), geographic expansion into attractive adjacent markets, and a shift from pure consumer propositions toward embedded and commercial offerings. These moves are not isolated product launches — they reveal strategic priorities: deepening customer engagement, diversifying revenue, and strengthening deposit and payments franchises.
What the full PW Consulting report delivers (practical, not academic)
Our market study is engineered for executives and investment committees who need to act in 2026. It goes beyond headline forecasts and high-level narratives to provide operationally relevant deliverables, including:
- Strategic playbooks for four archetypal players (scale-first challengers, niche specialists, incumbent digital transformations, and platform integrators) with decision trees and funding scenarios.
- Regulatory readouts and playbooks — mapping licensing pathways, supervisory expectations, and deposit-cost sensitivity analyses to inform funding strategies and liquidity stress-testing.
- Commercial growth levers — customer acquisition sequencing, pricing experiments, API/open-banking go-to-market templates, and partnerships frameworks to accelerate embedded banking revenue.
- M&A and partnership roadmaps — value-creation templates, integration checklists, and red-flag diagnostics to evaluate targets quickly and reduce execution risk.
- Financial model blueprints — unit-economics templates and scenario models calibrated to the sector’s growth profile and cost environment, enabling rapid “what-if” analysis.
- Competitive benchmarking and case studies — comparative diagnostics of product stacks, distribution channels, and operational resilience practices across the market’s notable participants.
To preserve the actionable advantage for our clients, the report deliberately withholds confidential segment-level tables and proprietary regional breakdowns from public summaries. The purpose is not opacity for its own sake, but to ensure readers engage directly with the full intelligence package when making binding strategic decisions.
Implications for 2026 planning cycles
- Investment committees: Prioritize opportunities that de-risk funding and exhibit clear path-to-profit under rising deposit-cost scenarios. Use our scenario templates to stress-test ROIC across acquisition channels.
- Product leaders: Embed regulatory constraints into your product roadmaps and prioritize features that generate recurring revenue streams (e.g., subscription-based business accounts or embedded payments fees).
- M&A teams: Target tuck-ins that deliver distribution access or core competencies (risk modelling, payments rails) rather than headline user counts alone.
- Technology vendors: Focus on hardening compliance, scaleability, and observability in your offerings — these are procurement filters of digital banks increasingly focused on operational resilience.
How to use this primer — and what to expect next
This primer is intended to catalyze three actions in your 2026 playbook: (1) run a rapid portfolio triage using the frameworks provided, (2) adopt regulatory-forward product roadmaps for any market-entry, and (3) fast-track M&A diligence around clearly defined capability gaps. The full PW Consulting study supplies the models, datasets, and red-team scenarios you need to move from deliberation to execution.
If your priorities include evaluating a new market entry, recalibrating customer-acquisition budgets, or building an M&A pipeline, the full report contains the precise forecasts, segmented analyses, and step-by-step playbooks required to make a confident decision. Our public summary intentionally showcases the analytical depth while reserving the granular segmentation and proprietary worksheets for report subscribers and consulting clients.
Closing
The Neo and Challenger Bank market in 2026 is a field of converging forces: maturity in product offerings, heightened regulatory attention, and continued but disciplined growth. Leaders who integrate regulatory foresight, disciplined funding strategy, and focused product monetization will claim the next wave of value. PW Consulting’s Neo and Challenger Bank Market study is designed to be the operational backbone of those decisions — a toolkit that moves teams from strategy through to measurable execution.
For detailed analysis of this topic, please visit the official page: Neo and Challenger Bank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com