

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
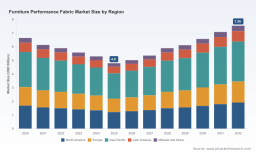
PW Consulting: Furniture Performance Fabric Market to Reach USD 7.56B by 2032 at 6.7% CAGR

Furniture Performance Fabric Market: Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused intelligence brief on the Furniture Performance Fabric market designed to inform high-stakes decisions in 2026. This sector—spanning indoor and outdoor upholstery for residential, commercial and contract applications—has just completed a pivotal five-year cycle and is poised for a sustained recovery. Our analysis synthesizes recent regulatory changes, raw-material drivers, supplier capacity moves, and commercial demand dynamics to surface the practical implications every executive must act on this year.
Furniture Performance Fabric Market
Macro picture: why 2026 is a turning point
After a multi-year contraction that culminated in a low baseline in 2025, the market is forecast to resume growth through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 6.7%. That trajectory translates to a materially larger market by the early 2030s relative to the 2025 baseline, driven by a convergence of factors: resilient furniture demand in key end markets, faster adoption of engineered stain- and abrasion-resistant textiles, and renewed supplier investment in capacity and domestic production. For corporate planners, 2026 represents the point at which tactical moves—supply reconfiguration, product portfolio prioritization, and standards-aligned product development—have a disproportionate impact on medium-term share and margin performance.
Furniture Performance Fabric Market
Market dynamics shaping near-term strategy
-
Standards and compliance are rising to the top of procurement criteria. In 2025–2026, major industry guidelines were updated to impose stricter durability and cleanability requirements for upholstery fabrics. These updates influence specification sheets for commercial, outdoor and public seating segments, and increase the cost of non-compliant substitution. Manufacturers and brand owners should assume tougher entry requirements for new SKUs and expect R&D and certification timelines to factor into product launch schedules.
Furniture Performance Fabric Market -
Raw-material volatility is a structural input risk. Upstream movements—such as a notable quarter-on-quarter increase in polyester filament yarn prices recorded in 2025, and a persistent premium for high-tenacity rPET relative to virgin PET—are reshaping supplier cost curves. Procurement teams need scenario-based sourcing playbooks that combine longer-term contracts, selective on-shoring, and targeted substitution strategies to insulate gross margins while meeting sustainability commitments.
-
Domestic capacity investments are creating competitive differentiation. Recent expansions by incumbent suppliers to increase specialty yarn and fabric throughput indicate a tactical pivot toward shortening lead times and mitigating international logistics risk. For brand owners, partner selection in 2026 should weigh domestic supply options more heavily when time-to-market, inventory turns, and service levels are critical.
-
Consolidation and concentrated incumbency alter negotiating dynamics. The market displays clear top-tier leadership in performance fabrics, which translates into differentiated access to proprietary chemistries, seasoned product development teams, and co-development opportunities. Smaller suppliers remain relevant for niche textures or local service, but the balance of power favors established specialist brands for large-scale commercial programs.
Competitive landscape: what the leading players reveal about strategic direction
Industry leaders continue to differentiate on three axes: proprietary material science, go-to-market breadth (residential vs. contract vs. outdoor), and manufacturing footprint. Representative examples from the competitive set illustrate these strategic postures:
-
Flagship proprietary brands with in-house fiber capability. Leaders that control upstream yarn capabilities and solution-dye processes are using that vertical control to optimize colorfastness, UV resistance and lifecycle footprint—attributes increasingly required by commercial specifications and outdoor furniture standards.
-
Specialist fabric makers focused on stain- and moisture-performance. Some suppliers have leaned into advanced finishing chemistries to deliver stain-blocking, moisture-barrier and odor-control functionalities. These features are becoming table stakes in hospitality and healthcare seating segments, and they materially change refurbishment economics for institutional buyers.
-
Furniture brands integrating proprietary washable-performance textiles. Major OEMs are embedding their own performance fabric lines into core upholstery products to lock in specification consistency and protect weighted margins. This trend warrants a closer look from fabric suppliers seeking to compete on co-development or white-label arrangements rather than commoditized selling.
Recent public moves underscore these themes: a specialty yarn plant expanded to support nearshore production; industry associations updated test protocols and outdoor performance guidance; and standardization efforts raised the bar on abrasion and cleanability. Each development tightens the window for reactive strategies and rewards proactive alignment between procurement, product development, and compliance teams.
What PW Consulting’s Furniture Performance Fabric report delivers
Our full market study is engineered as an operational playbook for 2026. It contains:
-
Scenario-driven financial models projecting demand and pricing under multiple macro assumptions across the 2026–2032 forecast window, enabling sensitivity analysis for margin planning and M&A valuation.
-
Supplier heat maps and capability audits that evaluate leading fabric makers on technical competencies, certification readiness, domestic capacity, and innovation pipelines—structured for rapid supplier shortlisting.
-
Product development playbooks aligning material choices, finishing routes and testing protocols to the latest standards and real-world cleaning regimens, accelerating time-to-certification for new offerings.
-
Procurement levers and negotiation frameworks that translate raw-material volatility signals into contract terms, indexation clauses, and hedging alternatives applicable to both spot and strategic sourcing.
-
Competitive attack and defense strategies for market-entry, premiumization, and private-label collaboration—complete with case templates for commercial pilots and channel rollouts.
-
Risk matrices and regulatory trackers that map compliance timeframes and certification costs against product launch calendars to mitigate non-compliant inventory exposure.
Actionable implications for 2026 executives
-
Re-benchmark procurement contracts now. With upstream feedstock moves still reverberating, renegotiating volume bands, indexation formulas and lead-time commitments should be prioritized. Establish dual-track sourcing with domestic backup suppliers for critical programs.
-
Prioritize standards-driven product updates. Update specification templates to reflect the newest furniture and outdoor fabric guidelines. Invest in third-party testing cycles early to avoid costly redesigns after tender windows close.
-
Differentiate through certified durability. Position premium lines around verified abrasion and cleanability outcomes. In commercial accounts, total cost of ownership arguments tied to longer life and lower maintenance will unlock higher price realization.
-
Use nearshoring as a tactical pricing and resilience lever. Evaluate the trade-offs between landed cost and inventory carrying cost—domestic capacity expansions by key suppliers create a timely opportunity to shorten replenishment cycles without sacrificing unit economics.
-
Build a sustainability-forward materials roadmap. With recycled high-tenacity yarn commanding a premium and sustainability criteria entering procurement scorecards, define clear substitution pathways and costed transition plans tied to product families.
-
Scan M&A and JV opportunities focused on technology and capacity. The recovery phase favors bolt-on acquisitions that bring proprietary chemistries, test labs, or domestic footprint. Consider small, high-synergy deals to accelerate certification and shorten product launch timelines.
Where PW Consulting adds immediate value
In 2026, decision speed and specificity matter. PW Consulting combines proprietary forecast models, validated supplier intelligence and standards-compliance timelines to convert market direction into executable plans. Whether you need a supplier shortlist for a major commercial project, a costed pivot to higher-performance constructions, or an M&A target screen keyed to nearshore capacity, our report supplies the structured inputs and playbook templates executives use to act with confidence.
Final note: why you should read the full report
This briefing intentionally illustrates the strategic contours of the Furniture Performance Fabric market while reserving the granular segment-level breakdowns, supplier scorecards and downloadable financial models for the full report. Those elements—critical for underwriting investments, pricing ladders, and procurement decisions—are presented with source-level transparency and interactive Excel tools on the report page. For executives who intend to lock in market share during the 2026 recovery, the full dataset and scenario toolkit are indispensable.
Contact PW Consulting to access the complete Furniture Performance Fabric market study and receive a tailored executive briefing that maps the findings to your product portfolio and supply chain priorities.
For detailed analysis of this topic, please visit the official page: Furniture Performance Fabric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com