

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Refrigerant Compressors Market to Reach USD 344.8M by 2032 at 5.25% CAGR

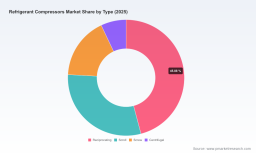
Refrigerant Compressors Market: Strategic Outlook for 2026
As organizations set priorities for 2026 capital allocation, product roadmaps and regulatory compliance, a rigorous and actionable understanding of the refrigerant compressors market is essential. PW Consulting’s latest study — using 2025 as the base year and projecting through 2032 — synthesizes historical performance (2020–2025) and forward scenarios to give leaders a decision-grade view. The market grew from roughly USD 163.15 Million in 2020 to USD 215.0 Million in 2025 and is forecast to reach approximately USD 234.31 Million in 2026 on a compounded annual growth rate (CAGR) of 5.25% over the forecast horizon, ultimately approaching USD 344.8 Million by 2032. This trajectory reflects structural shifts in refrigerant selection, efficiency requirements, and product architectures that will dictate winners and losers in the coming five years.
Refrigerant Compressors Market
Why this research matters for 2026 decisions
-
Regulatory inflection points are already reframing competitive advantages. Tighter GWP limits and new safety standards mean product portfolios built on yesterday’s refrigerants or architectures will likely require significant redesign or face restricted market access.
Refrigerant Compressors Market -
Technology adoption cycles are shortening. Investments in variable-speed drives, transcritical CO2 platforms and controls integration are becoming minimum viable investments rather than optional differentiators.
Refrigerant Compressors Market -
Market concentration is high — the top three players control a substantial share and the top five an even larger proportion — which shapes pricing power, aftermarket dynamics and M&A opportunities for both incumbents and challengers.
-
Supply chain reconfiguration and facility-level decisions made in 2026 will affect cost and delivery profiles well into the 2030s. Early movers that align manufacturing footprints with refrigerant and efficiency trends will extract outsized returns.
What the report delivers — practical content for immediate action
We designed the study as a practitioner’s toolkit for product, commercial and investment teams. Highlights include:
-
Robust market-sizing and demand modelling methodology that reconciles bottom-up OEM production data with top-down installed-base and replacement cycles for 2020–2032.
-
Scenario analyses that map regulatory and technology-driven pathways — and their P&L impact — under conservative, baseline and accelerated transition assumptions.
-
Technology and product roadmaps identifying where R&D dollars are most likely to protect margins (e.g., variable-speed integration, CO2 transcritical systems, high-temperature scrolls).
-
Commercial playbooks: channel strategies, pricing levers, and aftermarket capture approaches that translate market trends into revenue improvement initiatives.
-
Supply chain risk heatmaps and recommended actions across sourcing, capacity expansion and inventory policies to harden operations against raw material and logistics volatility.
-
A curated set of KPIs and investment criteria to support capital allocation, M&A screening and joint-venture negotiations.
Competitive landscape: capacities, strategies and recent moves
The refrigerant compressors sector shows clear signs of consolidation and technological differentiation. Market concentration metrics underscore this reality: the top three firms account for a dominant portion of market share, and the top five combine for an even higher proportion, shaping an environment where scale and technology leadership matter for access to key OEM channels and retrofit programs.
-
Copeland (St. Louis, Missouri): Focused on scroll platforms, Copeland’s 2026 product introductions — a variable-speed scroll paired with an EV4 variable frequency drive platform and a transcritical CO2 scroll with dynamic vapor injection — demonstrate a two-track approach: energy optimization and readiness for low-GWP refrigerants. For competitors and customers, the implication is clear: variable-speed and transcritical-capable platforms are becoming procurement check-boxes.
-
Bitzer SE (Sindelfingen, Germany): Long-established in reciprocating and scroll hermetic machines, Bitzer’s emphasis at trade events on natural refrigerants and data-center cooling highlights a strategic pivot toward high-growth, specialized cooling segments where natural refrigerant expertise is a differentiation driver.
-
Embraco / Nidec (Bento Gonçalves / Kyoto): Embraco’s heritage in hermetic piston and scroll units, now under the wider Nidec portfolio, places it in a strong cross-regional position to serve both residential and commercial channels — particularly where integrated OEM relationships matter.
-
Danfoss (Nordborg, Denmark): With investments in next-generation high-temperature scrolls and heat-pump-focused products, Danfoss is positioning to capture share as heating electrification and heat-pump adoption accelerate.
-
GEA (Düsseldorf, Germany): The company’s recent expansion of a reciprocating compressor assembly line in Izmir indicates an operational strategy to align capacity with demand in food & beverage and industrial refrigeration accounts.
-
Lennox International and Mueller Industries : Lennox drives channel-led strategies in residential and commercial HVAC, while Mueller’s upstream component exposure underscores the importance of vertical supply relationships in controlling cost and lead time.
Taken together, these moves show the market bifurcating: scale-focused incumbents doubling down on broad portfolios and localized capacity, while innovation-led players target niche, high-growth subsegments. Strategic responses in 2026 must therefore be calibrated to whether your objective is scale, niche leadership, or a hybrid approach.
Regulation and standards: the new baseline for product strategy
The policy environment has materially accelerated transition timetables. Key developments that shape near-term strategic choices include:
-
EPA’s finalized 700 GWP limit for many commercial and residential heating & cooling units effective January 1, 2025.
-
EU’s F-gas Regulation banning new stationary refrigeration equipment with GWP 150 or higher from 2025 onward — a definitive market closure for many legacy refrigerant platforms.
-
Updates under the EPA SNAP program and evolving safety standards (e.g., expanded UL requirements for flammable refrigerants and ASHRAE Standard 15 updates) that raise compliance complexity and certification timelines.
Implications for 2026: product roadmaps must incorporate compliance-driven redesign cycles; procurement must pre-qualify suppliers for safe-handling certifications; and market-entry timing must be aligned with equipment certification and field-retrofit windows. The cost of non-compliance is market exclusion rather than mere penalty risk.
Technology and go-to-market dynamics
Three technology themes dominate the strategic conversation:
-
Variable-speed integration and advanced controls — enabling energy savings and peak-load management.
-
Adoption of low-GWP and natural refrigerants, including transcritical CO2 architectures and engineered solutions for flammable refrigerants — both require design and materials changes as well as updated testing protocols.
-
Digital services — remote monitoring, predictive maintenance and service monetization are evolving from differentiators into expected capabilities in commercial and industrial accounts.
Commercially, OEM and retrofit channels will reward suppliers who bundle hardware with services and certification support. Pricing power will cluster around players who can demonstrate certified, efficient solutions with reliable service networks.
Six strategic imperatives for 2026
-
Prioritize portfolio compliance: accelerate phase-outs of high-GWP platforms and fast-track certification for low-GWP replacements.
-
Invest in variable-speed and control integration now — delays increase retrofit risk and reduce competitiveness in energy-sensitive accounts.
-
Align manufacturing footprints with refrigerant transition timelines to avoid stranded capacity; consider capacity partnerships where near-term demand is uncertain.
-
Build aftermarket and service-led revenue streams to stabilize margins as new equipment price competition intensifies.
-
Pursue targeted M&A for capability gaps (e.g., control electronics, safety certification expertise, natural refrigerant manufacturing know-how).
-
Implement scenario-driven capital allocation linked to regulatory milestones to protect downside while preserving upside optionality.
How to use this briefing — and what’s deliberately withheld
This article is designed to surface the strategic implications of our modelling and to demonstrate the depth of the full PW Consulting study. For decision-makers preparing budgets, R&D roadmaps or M&A pipelines in 2026, the full report provides the necessary compartmentalized detail: granular segment sizing, regional demand curves, technology adoption timing by application, supplier scorecards and primary-sourced pricing matrices. In keeping with our “preview” objective, we intentionally refrain from publishing the core sub-segment breakouts and region/application-level financials here — those details are available in the full report and the downloadable data appendix.
If your 2026 choices include product redesign, capacity decisions, or pursuing acquisition targets, the full study will provide the empirical inputs, scenario simulations and playbooks required to make them defensible and executable.
Next steps
Leaders preparing for 2026 should: request the full report to access the complete data model and appendices; commission a bespoke scenario run tied to your portfolio; and convene a cross-functional steering team to operationalize the six strategic imperatives outlined above. PW Consulting stands ready to provide tailored workshops, acquisition screening and hands-on integration plans to convert insight into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Refrigerant Compressors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com